Low Voltage Switchgear Market Size & Share 2026-2035
Report ID: GMI243
|
Published Date: September 2026
|
Report Format: PDF/Excel/Dashboard/Platform
Download Free PDF
Explore our licensing options:
Low Voltage (LV) Switchgear Market Size
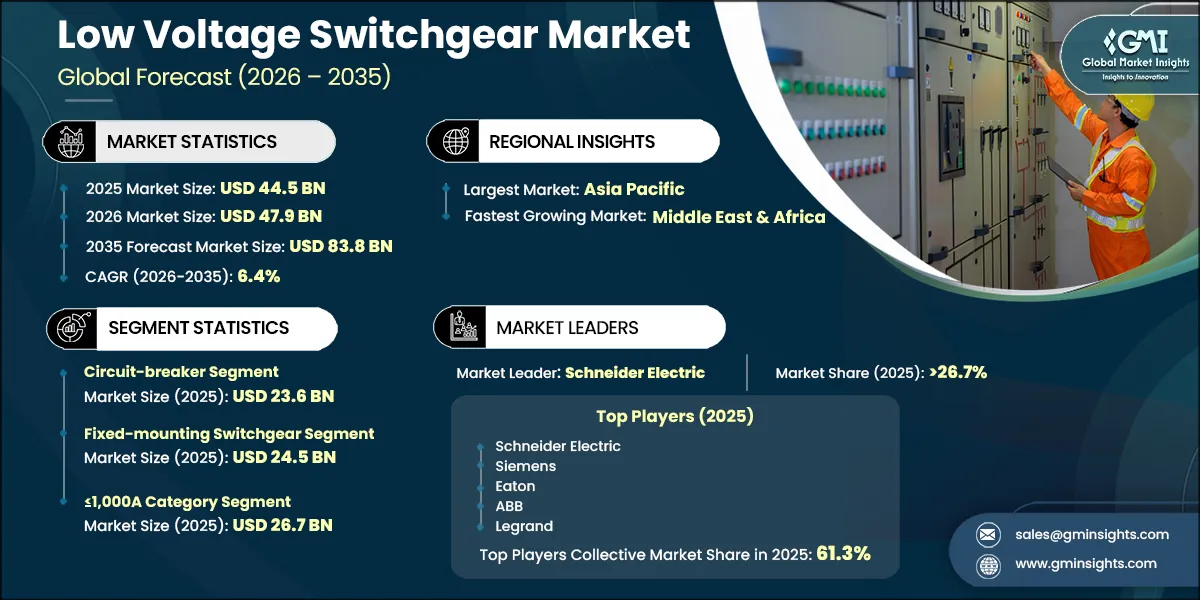
The Low Voltage (LV) Switchgear Market was valued at USD 44.5 billion in 2025 and is estimated to reach USD 47.9 billion in 2026, growing at 6.4% CAGR (2026–2035) to reach USD 83.8 billion by 2035.
The market encompasses electrical equipment, panels, and assemblies rated up to 1,000V AC or 1,500V DC for protection, control, isolation, and power distribution. Replacement of aging distribution assets is converging with new grid, renewable-energy, industrial-electrification, and critical-facility projects, shifting procurement toward equipment that combines protection performance, maintainability, and digital visibility.
GMI Analyst View
Based on our primary research discussions with leading switchgear OEMs and utility procurement teams, the global Low Voltage (LV) Switchgear Market reached an installed-base volume of approximately 4,100 thousand units (switchgear panels and assemblies) in 2025. We view this installed base as evidence that demand is supported by both new-build electrification and replacement activity, creating a more resilient procurement profile than reliance on a single end market would imply.
Low Voltage (LV) Switchgear Market Trends, Growth Drivers & GMI Forecast Outlook
Investment in distribution resilience and renewable integration is broadening demand, while higher material costs, field-labor constraints, and certification requirements shape the timing and profitability of deployment. The resulting market favors suppliers able to pair verified assemblies with faster engineering, installation support, and connected protection capabilities.
Key Drivers
Driver
Evidence signal
Market-demand implication
GMI forecast condition
Grid modernization investment
Global grid investment reached USD 400 billion per year in 2025 [1]
Utility-grade LV switchgear panels, circuit breakers, and distribution assemblies are integral to substation and distribution-grid upgrade programs, expanding procurement volumes across regional network operators
Sustained USD 400 billion+ in annual global grid capex through 2025 supports above-trend growth in utility and distribution-channel LV switchgear demand over the near-to-mid forecast horizon
Renewable energy capacity build-out
585 GW of renewable capacity was added globally in 2024, with annual growth of 15.1% [2]
Every new solar, wind, and energy-storage asset requires LV switchgear at the interconnection point, protection panel, and distribution board, expanding deployment in generation-adjacent applications
Continued record renewable additions keep LV switchgear demand from power-generation and interconnection customers structurally elevated
Digital switchgear adoption and IEC 61439 smart-integration cycle
Evolving IEC 61439 certification, together with adoption of IoT-enabled circuit breakers, is accelerating platform-level product refresh
Smart assemblies combine protection, measurement, and communication, supporting premium equipment and service opportunities
OEMs with certified smart platforms and established energy-management, SCADA, and building-management integration capture a disproportionate premium product mix
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
Grid reinforcement is increasingly tied to distribution-network modernization rather than isolated equipment replacement. Utilities need assemblies that accommodate distributed generation, changing load profiles, and remote operating requirements. This favors configurable protection architectures, sensing capability, and standardized interfaces that can be deployed across repeatable upgrade programs without compromising field-serviceability.
Renewable projects create a distinct requirement for LV protection at conversion, collection, and interconnection points. The commercial effect reaches beyond the initial installation: solar, storage, and wind assets require protection coordination, isolation capability, and maintainable distribution infrastructure throughout their operating lives. Suppliers with credible AC and DC portfolios are therefore better placed to participate across project stages.
Data-center campuses and automated industrial sites add another high-specification channel. The International Energy Agency expects global data-center electricity demand to rise from approximately 415 TWh in 2024 to around 945 TWh by 2030, intensifying the need for robust facility-level distribution architecture [4]. In these settings, uptime requirements strengthen the case for engineered, modular, and digitally monitored assemblies rather than basic commodity panels.
Key Restraints
Restraint
Evidence signal
Market-demand implication
GMI forecast condition
Elevated copper input costs
COMEX copper averaged USD 4.22 per pound in 2024, 9% higher than 2023 [3]
Elevated copper prices compress manufacturer margins and raise procurement prices for conductor-intensive assemblies
Price pass-through could constrain volume growth in cost-sensitive sub-distribution and commercial fit-out segments during 2026–2029
Qualified-installer workforce shortage
Approximately 10,000 electricians retire or change careers annually in the United States, compared with about 7,000 new entrants [7]
Installation delays and labor premiums reduce the volume that can be realized from strong project backlogs
Persistent installer shortfalls compress near-term demand realization in grid-expansion and industrial brownfield projects
IEC 61439 compliance complexity and evolving DC certification
Type-tested verification requirements apply to individual assembly configurations, while DC-related sub-parts remain under revision
Certification adds design, testing, and commercialization burdens, particularly for smaller suppliers and novel configurations
Additional certification investment may slow DC SKU launches and pressure margins during the transition period
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
Copper exposure is commercially significant because busbars, contacts, and related current-carrying components are integral to switchgear design. Procurement contracts with long delivery windows can leave manufacturers and buyers exposed to material-cost movement between specification and installation. Scale, supply agreements, engineering standardization, and value-added configuration options will influence which suppliers can preserve margins without losing bid competitiveness.
Installer scarcity affects conversion from equipment orders to commissioned projects. Modular and factory-tested assemblies can mitigate site-work intensity, but they also shift more value toward suppliers with engineering capacity, documentation discipline, and installation-support capabilities. This raises the importance of delivery execution alongside product availability.
Certification remains an essential safety and market-access requirement rather than a discretionary technical feature. As switchgear becomes more connected and DC applications expand, suppliers must manage a larger configuration burden. The challenge may reinforce the position of manufacturers with established testing programs, while limiting rapid entry by smaller fabricators.
GMI Analyst View
We believe the central forecast question is less about the existence of electrification demand than about the industry's ability to convert project pipelines into installed capacity. Suppliers that reduce engineering friction, lead times, and field-labor dependence should be better positioned to capture demand as procurement shifts toward more complex assemblies.
Low Voltage (LV) Switchgear Market Segment Analysis
By Protection
The Low Voltage (LV) Switchgear Market's circuit-breaker segment generated USD 23.6 billion in 2025 and is expected to account for 55.4% of the market by 2035. Circuit breakers benefit from demand for adjustable protection, coordinated fault management, and digitally enabled monitoring in industrial and utility environments. Their role expands where operators prioritize maintainability and selective protection over the lower initial cost of passive alternatives.
Fuses held 26.0% of the market in 2025 and are projected to reach USD 18.8 billion by 2035. Fuses remain relevant where simple, economical overcurrent protection is sufficient, especially in price-sensitive distribution applications. Their relative position is challenged where facilities seek monitoring, reset capability, and service continuity.
Fuse-switch disconnectors represented 8.5% of the market in 2025 and are projected to grow at 6.3% CAGR (2026–2035). The combination of isolation and overcurrent protection supports compact industrial feeder and motor applications. Demand is reinforced where panel space is constrained and procurement teams value integrated functionality.
Switch disconnectors with fuse generated USD 3.3 billion in 2025 and are anticipated to grow at 7.5% CAGR (2026–2035). This category is aligned with applications requiring reliable isolation and protection in a single arrangement, including renewable-energy and charging-infrastructure installations. Its growth profile reflects the increasing value placed on compact, serviceable field configurations.
By Product
Fixed-mounting switchgear generated USD 24.5 billion in 2025 and is expected to account for 51.9% of the market by 2035. Fixed equipment remains suited to mainstream distribution installations where capital discipline and standardized layouts outweigh the need for frequent in-service device replacement. It retains a large installed base but faces a mix shift toward more accessible configurations in critical-load environments.
Plug-in switchgear held 32.0% of the market in 2025 and is projected to reach USD 27.8 billion by 2035. The format enables faster replacement and maintenance with less disruption to the broader assembly. This makes it particularly relevant to facilities where continuity of operations is central to the purchasing decision.
Withdrawable-unit switchgear generated USD 5.8 billion in 2025 and is forecast to grow at 8.1% CAGR (2026–2035). Withdrawable designs address maintenance access and arc-flash risk in higher-specification installations. Their momentum indicates that uptime, safety, and maintainability are increasingly valued alongside initial equipment cost.
By Rated Current
The ≤1,000A category generated USD 26.7 billion in 2025 and is expected to account for 57.2% of market revenue by 2035. This band serves the broad base of commercial, light-industrial, and sub-distribution requirements. Its scale reflects the volume of installations that need standardized protection across buildings, smaller facilities, and distributed electrical loads.
The >1,000A to ≤5,000A category held 32.0% of the market in 2025 and is expected to grow at 7.1% CAGR (2026–2035). Demand in this range is linked to concentrated loads in industrial plants, data centers, and charging hubs. Higher-capacity assemblies can simplify distribution architecture and support the consolidation of protection functions.
The >5,000A category generated USD 3.6 billion in 2025 and is forecast to grow at 7.9% CAGR (2026–2035). High-current equipment is increasingly relevant to major industrial power centers and large grid-related upgrades. Its above-market trajectory reflects the electrification of load-intensive assets and the need for fewer, more capable assemblies.
By Voltage Rating
The ≤250V category generated USD 16.9 billion in 2025 and is expected to account for 36.2% of the market by 2035. This range remains central to light-commercial and residential-adjacent distribution needs. Its share profile reflects the faster relative growth of more demanding industrial, utility, and renewable-linked electrical systems.
The >250V to ≤750V category held 48.0% of the market in 2025 and is projected to reach USD 40.5 billion by 2035. This voltage band supports a wide mix of industrial three-phase distribution, motor control, and commercial power systems. Product breadth and compatibility across OEM portfolios reinforce its large role in the market.
The >750V category generated USD 6.2 billion in 2025 and is expected to grow at 7.7% CAGR (2026–2035). Equipment at the upper end of the LV range benefits from expanding DC bus architectures in solar, storage, and other high-capacity systems. The category requires rigorous engineering and certification, raising the relevance of proven suppliers.
By Current
AC switchgear generated USD 36.9 billion in 2025 and is expected to account for 79.0% of the market by 2035. AC infrastructure remains the core demand base for conventional power distribution, motor control, and commercial electrical systems. Its continuing dominance reflects the scale and longevity of installed alternating-current networks.
DC switchgear held 17.0% of the market in 2025 and is forecast to grow at 9.0% CAGR (2026–2035). DC adoption is supported by solar PV, energy storage, fast charging, and selected data-center architectures. As these applications scale, DC protection is becoming a more routine design consideration rather than a specialist exception.
By Application
Distribution generated USD 15.1 billion in 2025 and is expected to account for 32.0% of market revenue by 2035. Distribution applications benefit from the large and diverse installed base of commercial buildings, light-industrial facilities, and residential complexes. Demand is tied to both new construction and the replacement of aging feeder and sub-panel equipment.
Substation applications held 23.0% of the market in 2025 and are projected to reach USD 20.1 billion by 2035. Grid modernization raises the value of substation-grade LV assemblies that support monitoring, remote switching, and changing power-flow requirements. These projects favor suppliers able to meet utility engineering and qualification expectations.
Motor-control applications generated USD 8.0 billion in 2025 and are forecast to grow at 6.0% CAGR (2026–2035). Factory automation, process industries, mining, and water-treatment assets continue to require dependable motor protection and control. The segment's performance is therefore linked to industrial capital expenditure and modernization cycles.
Sub-distribution held 15.0% of the market in 2025 and is projected to reach USD 13.4 billion by 2035. Commercial construction and the electrification of building services underpin sub-distribution demand. The category remains sensitive to project budgets, installation capacity, and material-price pass-through.
Power factor correction generated USD 4.5 billion in 2025 and is expected to grow at 7.5% CAGR (2026–2035). Rising non-linear loads and power-quality requirements increase the need for corrective equipment in commercial and industrial networks. This creates a targeted opportunity for suppliers combining protection expertise with power-management capability.
GMI Analyst View
We see the most consequential mix shift occurring in configurations that solve for uptime, safety, and DC integration rather than in basic volume categories. Manufacturers with credible withdrawable, high-current, digitally connected, and DC-capable portfolios are better positioned to improve revenue quality as customers specify more sophisticated electrical architectures.
Low Voltage (LV) Switchgear Market Regional Analysis
North America Low Voltage (LV) Switchgear Market Analysis
The Low Voltage (LV) Switchgear Market in North America generated USD 14.9 billion in 2025 and is projected to reach USD 26.4 billion by 2035. Grid hardening, data-center construction, industrial automation, and manufacturing investment create a diverse regional demand base. The market favors suppliers that can meet domestic project schedules while supporting increasingly engineered electrical-system requirements.
U.S.
The U.S. generated USD 9.9 billion in 2025 and is projected to reach USD 17.6 billion by 2035. Utility programs, hyperscale campuses, and electrified infrastructure projects sustain demand for protection and distribution equipment. Customer requirements increasingly emphasize delivery assurance, modularity, and field-service capability.
Canada
Canada held 18.1% of the North American market in 2025 and is expected to grow at 6.2% CAGR (2026–2035). Hydroelectric development, mining electrification, and activity around data infrastructure support demand. Procurement is shaped by geographic complexity and the need for dependable equipment across dispersed industrial and utility assets.
Mexico
Mexico generated USD 2.3 billion in 2025 and is expected to account for 14.4% of the North American market by 2035. Nearshoring is expanding demand from automotive, electronics, and consumer-goods manufacturing. Industrial investment is supplemented by commercial construction and ongoing requirements for sub-distribution equipment.
Europe Low Voltage (LV) Switchgear Market Analysis
Europe held 21.1% of the global market in 2025 and is projected to reach USD 16.8 billion by 2035. Distribution-grid modernization, industrial decarbonization, and rigorous compliance expectations support demand for type-tested and digitally capable assemblies. The region's procurement culture rewards documented performance, established channel support, and lifecycle-service capability.
Germany
Germany generated USD 1.7 billion in 2025 and is projected to reach USD 3.0 billion by 2035. Grid balancing, renewable integration, and automation investment across manufacturing maintain a diversified demand profile. The market is suited to suppliers with strong technical documentation and industrial customer relationships.
UK
The UK held 11.5% of the European market in 2025 and is forecast to grow at 6.8% CAGR (2026–2035). Offshore wind, data-center activity, and infrastructure investment support switchgear demand. Projects increasingly prioritize resilient, efficient electrical distribution and maintainable protection equipment.
France
France generated USD 976 million in 2025 and is projected to account for 10.7% of the European market by 2035. Building renovation, mobility infrastructure, and power-system investment provide several demand channels. Suppliers must navigate a market where quality, standards compliance, and installed-base service remain important differentiators.
Italy
Italy held 9.5% of the European market in 2025 and is projected to reach USD 1.7 billion by 2035. Renewable investment and replacement demand in established manufacturing clusters support the market. Local engineering knowledge and responsive channels can be important in fragmented project environments.
Spain
Spain generated USD 660 million in 2025 and is expected to grow at 6.0% CAGR (2026–2035). Solar deployment and grid modernization underpin demand for distribution and interconnection equipment. The opportunity is strengthened by projects that require equipment capable of managing changing generation patterns.
Asia Pacific Low Voltage (LV) Switchgear Market Analysis
Asia Pacific held 36.6% of global revenue in 2025 and is projected to reach USD 32.0 billion by 2035. The region combines large-scale grid investment, industrial development, urban construction, and renewable deployment. Its breadth creates room for both global OEMs and domestic suppliers, although pricing, certification, and channel requirements differ substantially across national markets.
China
China generated USD 8.6 billion in 2025 and is expected to account for 45.9% of the Asia Pacific market by 2035. Grid modernization, renewable capacity deployment, and charging-network expansion sustain high procurement volumes. Market participants must balance scale and delivery capacity with a competitive domestic supplier environment.
India
India held 13.2% of the Asia Pacific market in 2025 and is expected to grow at 11.5% CAGR (2026–2035). Industrial investment, electrification programs, renewable procurement, and commercial development create a strong growth environment. The opportunity favors product portfolios that address both cost sensitivity and demanding infrastructure applications.
Japan
Japan generated USD 1.5 billion in 2025 and is projected to reach USD 2.4 billion by 2035. Grid resilience, precision manufacturing, and distributed-energy integration support replacement and upgrade demand. Reliability, long lifecycle performance, and qualification credentials remain central to supplier positioning.
South Korea
South Korea held 5.8% of the Asia Pacific market in 2025 and is projected to grow at 6.1% CAGR (2026–2035). Semiconductor, display, and data-center investments require dependable power-distribution infrastructure. Demand is skewed toward technically capable assemblies that support high-load, high-availability operations.
Australia
Australia generated USD 489 million in 2025 and is projected to reach USD 930 million by 2035. Renewable projects, mining electrification, and utility investment broaden the demand base. Remote-project execution and harsh operating conditions increase the value of serviceability and robust engineering.
Latin America Low Voltage (LV) Switchgear Market Analysis
Latin America held 3.5% of global revenue in 2025 and is projected to reach USD 3.1 billion by 2035. Demand is concentrated in large national markets but is supported more broadly by renewable investment, grid expansion, and industrial development. Economic volatility and financing conditions can influence project timing, making supplier flexibility important.
Brazil
Brazil generated USD 878 million in 2025 and is projected to reach USD 1.8 billion by 2035. Electrification initiatives, manufacturing activity, and renewable-energy development support a wide range of distribution requirements. Local market coverage and application-specific engineering are material competitive considerations.
Argentina
Argentina held 14.0% of the Latin American market in 2025 and is expected to grow at 5.4% CAGR (2026–2035). Grid rehabilitation and energy-infrastructure work provide a baseline for demand, although macroeconomic conditions can affect the pace of capital deployment. Suppliers with flexible commercial structures may be better positioned to manage timing risk.
Middle East & Africa Low Voltage (LV) Switchgear Market Analysis
Middle East & Africa generated USD 2.4 billion in 2025 and is forecast to grow at 8.7% CAGR (2026–2035). Diversification programs, urban development, industrial projects, and electrification needs create a growth-oriented market. Project execution, specification standards, financing, and local service capability vary considerably across the region.
Saudi Arabia
Saudi Arabia generated USD 641 million in 2025 and is projected to reach USD 1.7 billion by 2035. Large-scale development, industrial investment, and renewable programs support demand across utility, commercial, and industrial channels. The scale of planned projects rewards suppliers able to provide qualified products and reliable execution support.
UAE
The UAE held 20.0% of the Middle East & Africa market in 2025 and is expected to grow at 10.9% CAGR (2026–2035). Data centers, premium real estate, renewable installations, and industrial facilities support demand for higher-specification assemblies. International compliance and digital-capability requirements can influence vendor selection.
Turkey
Turkey generated USD 288 million in 2025 and is expected to account for 9.9% of the Middle East & Africa market by 2035. Industrial production and renewable investment support steady demand, while the country's position across regional trade routes supports infrastructure activity. Market participation requires sensitivity to local procurement dynamics and price positioning.
South Africa
South Africa held 9.1% of the Middle East & Africa market in 2025 and is projected to reach USD 370 million by 2035. Grid rehabilitation, independent-power projects, and mining electrification sustain demand. Equipment reliability and service support are important where operating continuity is critical.
Egypt
Egypt generated USD 168 million in 2025 and is expected to grow at 8.5% CAGR (2026–2035). Urban-development projects, energy infrastructure, and renewable awards create opportunities across multiple end uses. Procurement performance will depend on project financing and suppliers' ability to support large, multi-stage installations.
GMI Analyst View
We interpret the regional mix as a shift toward markets where electrification is still being built out alongside demand in mature regions focused on replacement and modernization. OEMs that tailor product specification, channel coverage, and service models to local execution realities should have a clearer path to converting regional growth into durable share gains.
Low Voltage (LV) Switchgear Market Share & Competitive Landscape
The Low Voltage (LV) Switchgear Market share structure is moderately concentrated: Schneider Electric, Siemens, Eaton, ABB, and Legrand together held 61.3% in 2025. Scale matters because global OEMs can combine certification depth, broad product portfolios, established distribution, and service infrastructure, while regional fabricators often compete through responsiveness, customization, and price.
Schneider Electric held 26.7% market share in 2025. Its competitive position is reinforced by integrated energy-management and connected-protection offerings that allow customers to link switchgear with facility, industrial, and utility operating systems. This platform orientation is particularly relevant where customers prioritize visibility, lifecycle management, and coordinated electrical infrastructure.
Siemens held 9.7% market share in 2025. The company competes through a broad electrical-products portfolio and a strong Smart Infrastructure position, addressing requirements from standard distribution through more digitally enabled installations. Its strength lies in the ability to pair protection equipment with adjacent automation, monitoring, and building-infrastructure capabilities.
Eaton held 8.6% market share in 2025. Its emphasis on electrical infrastructure, engineered solutions, and critical-power applications positions it well in data-center, utility, and industrial opportunities. Eaton completed the acquisition of Fibrebond in April 2025, expanding its ability to offer pre-integrated modular power enclosures for these end markets [6].
ABB & GE Vernova remains major participant through their electrification portfolio, including air circuit breakers, molded-case circuit breakers, and compact protection devices. Its position is supported by established industrial and utility relationships, as well as a portfolio that addresses smart-power and building-distribution requirements.
Fuji Electric, Mitsubishi Electric, Toshiba, LS Electric, HD Hyundai Electric, and Hyosung Heavy Industries bring strong positions in Asian industrial, utility, and manufacturing environments. Their regional footprint, factory-automation relationships, and broad electrical-equipment capabilities support participation in switchgear projects requiring local engineering and service access.
Bharat Heavy Electricals and CG Power and Industrial Solutions are significant participants in India, where domestic manufacturing relationships, infrastructure procurement, and electrification investment shape competitive access. Their market relevance is linked to the ability to serve both industrial and utility-facing requirements.
E+I Engineering, IEM, G&W Electric, Lucy Group, nVent, Ormazabal, and Skema demonstrate the importance of application specialization. Competitive differentiation can stem from custom engineering, critical-power expertise, automated switching, distribution-network capability, modular power systems, or renewable-interconnection experience.
nVent completed its acquisition of the Electrical Products Group of Avail Infrastructure Solutions in May 2025, adding switchgear, enclosure, and bus-system capabilities serving utility, data-center, and renewable applications [5]. The transaction illustrates how strategic acquisitions are being used to build more integrated electrical-infrastructure offerings and to reduce execution complexity for end users.
Recent Industry Developments
nVent completes acquisition of Avail Infrastructure Solutions' Electrical Products Group (May 2025). nVent acquired the Electrical Products Group business, expanding its portfolio in switchgear, enclosures, and bus systems for power utilities, data centers, and renewable-energy installations [5].
Eaton completes acquisition of Fibrebond (April 2025). Eaton acquired Fibrebond, strengthening its capacity to deliver pre-integrated modular power-enclosure solutions to data-center, utility, and industrial customers [6].
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.
Authors: Ankit Gupta, Riya Gupta
Low Voltage Switchgear Market Scope
Low Voltage Switchgear Market Size
Low Voltage Switchgear Market Trends
Low Voltage Switchgear Market Analysis
Low Voltage Switchgear Market Share
Report Content
Chapter 1. Research Methodology
1.1 Research approach
1.2 Quality Commitments
1.2.1 GMI AI policy & data integrity commitment
1.2.1.1 Source consistency protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial list of primary sources
1.5 Data mining sources
1.5.1 Paid sources
1.5.1.1 Sources, by region
1.6 Base estimates and calculations
1.6.1 Base year calculation
1.7 Forecast model
1.7.1 Quantified market impact analysis
1.7.1.1 Mathematical impact of growth parameters on forecast
1.8 Research transparency addendum
1.8.1 Source attribution framework
1.8.2 Quality assurance metrics
1.8.3 Our commitment to trust
Chapter 2. Executive Summary
2.1 Industry 360° synopsis
2.2 Key market trends
2.2.1 Protection trends
2.2.2 Product trends
2.2.3 Rated current trends
2.2.4 Voltage rating trends
2.2.5 Current trends
2.2.6 Application trends
2.2.7 Regional trends
Chapter 3. Industry Insights
3.1 Industry ecosystem analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost structure
3.1.4 Value addition at each stage
3.1.5 Factor affecting the value chain
3.1.6 Disruptions
3.2 Industry impact forces
3.2.1 Growth drivers
3.2.1.1 Technological breakthroughs
3.2.1.2 Aging population
3.2.1.3 Expanding industrial automation
3.2.1.4 Consumer demand for personal assistants
3.2.1.5 Educational innovation
3.2.2 Industry pitfalls and challenges
3.2.2.1 High development costs
3.2.2.2 Ethical and social concerns
3.2.3 Market opportunities
3.3 Growth potential analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
3.5 Regulatory landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia-Pacific
3.5.4 Latin America
3.5.5 Middle East and Africa
3.6 Porter’s analysis
3.7 PESTEL analysis
3.8 Trade Data Analysis (Based on Paid Database)
3.8.1 Import/Export Volume & Value Trends
3.8.2 Key Trade Corridors & Tariff Impact
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company market share analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia-Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East and Africa
4.2.2 Market Concentration Analysis
4.3 Competitive analysis of major market players
4.4 Competitive positioning matrix
4.5 Key developments
4.5.1 Mergers & acquisitions
4.5.2 Partnerships & collaborations
4.5.3 New product launches
4.5.4 Expansion plans and funding
4.6 Company tier benchmarking
4.6.1 Tier classification criteria & qualifying thresholds
4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5. Market Estimates and Forecast, By Protection, 2022 – 2035 ($ Million, Units)
5.1 Key trends
5.2 Circuit Breakers
5.2.1 ACB
5.2.2 MCCB
5.2.3 MCB
5.2.4 MSP
5.2.5 MPCB
5.3 Fuse
5.3.1 Fuse-Switch Disconnector
5.3.2 Switch Disconnector with Fuse
5.3.3 Others
Chapter 6. Market Estimates and Forecast, By Product, 2022 – 2035 ($ Million, Units)
6.1 Key trends
6.2 Fixed mounting
6.3 Plug-in
6.4 Withdrawable Unit
Chapter 7. Market Estimates and Forecast, By Rated Current, 2022 – 2035 ($ Million, Units)
7.1 Key trends
7.2 ≤ 1000 Ampere
7.3 > 1000 Ampere to ≤ 5000 Ampere
7.4 > 5000 Ampere
Chapter 8. Market Estimates and Forecast, By Voltage Rating, 2022 – 2035 ($ Million, Units)
8.1 Key trends
8.2 ≤ 250 volts
8.3 > 250 volts to ≤ 750 volts
8.4 > 750 volts
Chapter 9. Market Estimates and Forecast, By Current, 2022 – 2035 ($ Million, Units)
9.1 Key trends
9.2 AC
9.3 DC
Chapter 10. Market Estimates and Forecast, By Application, 2022 – 2035 ($ Million, Units)
10.1 Key trends
10.2 Substation
10.3 Distribution
10.4 Power Factor Correction
10.5 Sub Distribution
10.6 Motor Control
Chapter 11. Market Estimates and Forecast, By Region, 2022 – 2035 ($ Million, Units)
11.1 Key trends
11.1.1 North America
11.1.1.1 U.S.
11.1.1.2 Canada
11.1.1.3 Mexico
11.1.2 Europe
11.1.2.1 UK
11.1.2.2 France
11.1.2.3 Germany
11.1.2.4 Italy
11.1.2.5 Russia
11.1.2.6 Spain
11.1.2.7 Rest of Europe
11.1.3 Asia Pacific
11.1.3.1 China
11.1.3.2 Australia
11.1.3.3 India
11.1.3.4 Japan
11.1.3.5 South Korea
11.1.3.6 Rest of APAC
11.1.4 Middle East & Africa
11.1.4.1 Saudi Arabia
11.1.4.2 UAE
11.1.4.3 Turkey
11.1.4.4 South Africa
11.1.4.5 Egypt
11.1.4.6 Rest of MEA
11.1.5 Latin America
11.1.5.1 Brazil
11.1.5.2 Argentina
11.1.5.3 Rest of Latin America
Chapter 12. Company Profiles
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Regional or domestic-only leaders not in the global top tier
Distributors and channel partners who control market access
Emerging disruptors, startups, or adjacent-industry entrants
Niche players focused on a specific application or end-use
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at[email protected]
Over 70% of our clients customize reports to fit their needs. Please tell us how you would like to customize yours below
Share Content
Add Citations
Ankit Gupta. 2026, September. Low Voltage Switchgear Market Size - By Protection, By Product, By Rated Current, By Voltage Rating, By Current, By Application, Analysis, Share, & Forecast, 2026 - 2035 (Report ID: GMI243). Global Market Insights Inc. Retrieved October 13, 2026, from https://www.gminsights.com/toc/details/low-voltage-lv-switchgear-market
Low Voltage Switchgear Market
Get a free sample of this report
Get a free sample of this report Low Voltage Switchgear Market
Is your requirement urgent? Please give us your business email for a speedy delivery!



Low Voltage (LV) Switchgear Market Size
The Low Voltage (LV) Switchgear Market was valued at USD 44.5 billion in 2025 and is estimated to reach USD 47.9 billion in 2026, growing at 6.4% CAGR (2026–2035) to reach USD 83.8 billion by 2035.
The market encompasses electrical equipment, panels, and assemblies rated up to 1,000V AC or 1,500V DC for protection, control, isolation, and power distribution. Replacement of aging distribution assets is converging with new grid, renewable-energy, industrial-electrification, and critical-facility projects, shifting procurement toward equipment that combines protection performance, maintainability, and digital visibility.
GMI Analyst View
Based on our primary research discussions with leading switchgear OEMs and utility procurement teams, the global Low Voltage (LV) Switchgear Market reached an installed-base volume of approximately 4,100 thousand units (switchgear panels and assemblies) in 2025. We view this installed base as evidence that demand is supported by both new-build electrification and replacement activity, creating a more resilient procurement profile than reliance on a single end market would imply.
Low Voltage (LV) Switchgear Market Trends, Growth Drivers & GMI Forecast Outlook
Investment in distribution resilience and renewable integration is broadening demand, while higher material costs, field-labor constraints, and certification requirements shape the timing and profitability of deployment. The resulting market favors suppliers able to pair verified assemblies with faster engineering, installation support, and connected protection capabilities.
Key Drivers
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
Grid reinforcement is increasingly tied to distribution-network modernization rather than isolated equipment replacement. Utilities need assemblies that accommodate distributed generation, changing load profiles, and remote operating requirements. This favors configurable protection architectures, sensing capability, and standardized interfaces that can be deployed across repeatable upgrade programs without compromising field-serviceability.
Renewable projects create a distinct requirement for LV protection at conversion, collection, and interconnection points. The commercial effect reaches beyond the initial installation: solar, storage, and wind assets require protection coordination, isolation capability, and maintainable distribution infrastructure throughout their operating lives. Suppliers with credible AC and DC portfolios are therefore better placed to participate across project stages.
Data-center campuses and automated industrial sites add another high-specification channel. The International Energy Agency expects global data-center electricity demand to rise from approximately 415 TWh in 2024 to around 945 TWh by 2030, intensifying the need for robust facility-level distribution architecture [4]. In these settings, uptime requirements strengthen the case for engineered, modular, and digitally monitored assemblies rather than basic commodity panels.
Key Restraints
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
Copper exposure is commercially significant because busbars, contacts, and related current-carrying components are integral to switchgear design. Procurement contracts with long delivery windows can leave manufacturers and buyers exposed to material-cost movement between specification and installation. Scale, supply agreements, engineering standardization, and value-added configuration options will influence which suppliers can preserve margins without losing bid competitiveness.
Installer scarcity affects conversion from equipment orders to commissioned projects. Modular and factory-tested assemblies can mitigate site-work intensity, but they also shift more value toward suppliers with engineering capacity, documentation discipline, and installation-support capabilities. This raises the importance of delivery execution alongside product availability.
Certification remains an essential safety and market-access requirement rather than a discretionary technical feature. As switchgear becomes more connected and DC applications expand, suppliers must manage a larger configuration burden. The challenge may reinforce the position of manufacturers with established testing programs, while limiting rapid entry by smaller fabricators.
GMI Analyst View
We believe the central forecast question is less about the existence of electrification demand than about the industry's ability to convert project pipelines into installed capacity. Suppliers that reduce engineering friction, lead times, and field-labor dependence should be better positioned to capture demand as procurement shifts toward more complex assemblies.
Low Voltage (LV) Switchgear Market Segment Analysis
By Protection
The Low Voltage (LV) Switchgear Market's circuit-breaker segment generated USD 23.6 billion in 2025 and is expected to account for 55.4% of the market by 2035. Circuit breakers benefit from demand for adjustable protection, coordinated fault management, and digitally enabled monitoring in industrial and utility environments. Their role expands where operators prioritize maintainability and selective protection over the lower initial cost of passive alternatives.
Fuses held 26.0% of the market in 2025 and are projected to reach USD 18.8 billion by 2035. Fuses remain relevant where simple, economical overcurrent protection is sufficient, especially in price-sensitive distribution applications. Their relative position is challenged where facilities seek monitoring, reset capability, and service continuity.
Fuse-switch disconnectors represented 8.5% of the market in 2025 and are projected to grow at 6.3% CAGR (2026–2035). The combination of isolation and overcurrent protection supports compact industrial feeder and motor applications. Demand is reinforced where panel space is constrained and procurement teams value integrated functionality.
Switch disconnectors with fuse generated USD 3.3 billion in 2025 and are anticipated to grow at 7.5% CAGR (2026–2035). This category is aligned with applications requiring reliable isolation and protection in a single arrangement, including renewable-energy and charging-infrastructure installations. Its growth profile reflects the increasing value placed on compact, serviceable field configurations.
By Product
Fixed-mounting switchgear generated USD 24.5 billion in 2025 and is expected to account for 51.9% of the market by 2035. Fixed equipment remains suited to mainstream distribution installations where capital discipline and standardized layouts outweigh the need for frequent in-service device replacement. It retains a large installed base but faces a mix shift toward more accessible configurations in critical-load environments.
Plug-in switchgear held 32.0% of the market in 2025 and is projected to reach USD 27.8 billion by 2035. The format enables faster replacement and maintenance with less disruption to the broader assembly. This makes it particularly relevant to facilities where continuity of operations is central to the purchasing decision.
Withdrawable-unit switchgear generated USD 5.8 billion in 2025 and is forecast to grow at 8.1% CAGR (2026–2035). Withdrawable designs address maintenance access and arc-flash risk in higher-specification installations. Their momentum indicates that uptime, safety, and maintainability are increasingly valued alongside initial equipment cost.
By Rated Current
The ≤1,000A category generated USD 26.7 billion in 2025 and is expected to account for 57.2% of market revenue by 2035. This band serves the broad base of commercial, light-industrial, and sub-distribution requirements. Its scale reflects the volume of installations that need standardized protection across buildings, smaller facilities, and distributed electrical loads.
The >1,000A to ≤5,000A category held 32.0% of the market in 2025 and is expected to grow at 7.1% CAGR (2026–2035). Demand in this range is linked to concentrated loads in industrial plants, data centers, and charging hubs. Higher-capacity assemblies can simplify distribution architecture and support the consolidation of protection functions.
The >5,000A category generated USD 3.6 billion in 2025 and is forecast to grow at 7.9% CAGR (2026–2035). High-current equipment is increasingly relevant to major industrial power centers and large grid-related upgrades. Its above-market trajectory reflects the electrification of load-intensive assets and the need for fewer, more capable assemblies.
By Voltage Rating
The ≤250V category generated USD 16.9 billion in 2025 and is expected to account for 36.2% of the market by 2035. This range remains central to light-commercial and residential-adjacent distribution needs. Its share profile reflects the faster relative growth of more demanding industrial, utility, and renewable-linked electrical systems.
The >250V to ≤750V category held 48.0% of the market in 2025 and is projected to reach USD 40.5 billion by 2035. This voltage band supports a wide mix of industrial three-phase distribution, motor control, and commercial power systems. Product breadth and compatibility across OEM portfolios reinforce its large role in the market.
The >750V category generated USD 6.2 billion in 2025 and is expected to grow at 7.7% CAGR (2026–2035). Equipment at the upper end of the LV range benefits from expanding DC bus architectures in solar, storage, and other high-capacity systems. The category requires rigorous engineering and certification, raising the relevance of proven suppliers.
By Current
AC switchgear generated USD 36.9 billion in 2025 and is expected to account for 79.0% of the market by 2035. AC infrastructure remains the core demand base for conventional power distribution, motor control, and commercial electrical systems. Its continuing dominance reflects the scale and longevity of installed alternating-current networks.
DC switchgear held 17.0% of the market in 2025 and is forecast to grow at 9.0% CAGR (2026–2035). DC adoption is supported by solar PV, energy storage, fast charging, and selected data-center architectures. As these applications scale, DC protection is becoming a more routine design consideration rather than a specialist exception.
By Application
Distribution generated USD 15.1 billion in 2025 and is expected to account for 32.0% of market revenue by 2035. Distribution applications benefit from the large and diverse installed base of commercial buildings, light-industrial facilities, and residential complexes. Demand is tied to both new construction and the replacement of aging feeder and sub-panel equipment.
Substation applications held 23.0% of the market in 2025 and are projected to reach USD 20.1 billion by 2035. Grid modernization raises the value of substation-grade LV assemblies that support monitoring, remote switching, and changing power-flow requirements. These projects favor suppliers able to meet utility engineering and qualification expectations.
Motor-control applications generated USD 8.0 billion in 2025 and are forecast to grow at 6.0% CAGR (2026–2035). Factory automation, process industries, mining, and water-treatment assets continue to require dependable motor protection and control. The segment's performance is therefore linked to industrial capital expenditure and modernization cycles.
Sub-distribution held 15.0% of the market in 2025 and is projected to reach USD 13.4 billion by 2035. Commercial construction and the electrification of building services underpin sub-distribution demand. The category remains sensitive to project budgets, installation capacity, and material-price pass-through.
Power factor correction generated USD 4.5 billion in 2025 and is expected to grow at 7.5% CAGR (2026–2035). Rising non-linear loads and power-quality requirements increase the need for corrective equipment in commercial and industrial networks. This creates a targeted opportunity for suppliers combining protection expertise with power-management capability.
GMI Analyst View
We see the most consequential mix shift occurring in configurations that solve for uptime, safety, and DC integration rather than in basic volume categories. Manufacturers with credible withdrawable, high-current, digitally connected, and DC-capable portfolios are better positioned to improve revenue quality as customers specify more sophisticated electrical architectures.
Low Voltage (LV) Switchgear Market Regional Analysis
North America Low Voltage (LV) Switchgear Market Analysis
The Low Voltage (LV) Switchgear Market in North America generated USD 14.9 billion in 2025 and is projected to reach USD 26.4 billion by 2035. Grid hardening, data-center construction, industrial automation, and manufacturing investment create a diverse regional demand base. The market favors suppliers that can meet domestic project schedules while supporting increasingly engineered electrical-system requirements.
U.S.
The U.S. generated USD 9.9 billion in 2025 and is projected to reach USD 17.6 billion by 2035. Utility programs, hyperscale campuses, and electrified infrastructure projects sustain demand for protection and distribution equipment. Customer requirements increasingly emphasize delivery assurance, modularity, and field-service capability.
Canada
Canada held 18.1% of the North American market in 2025 and is expected to grow at 6.2% CAGR (2026–2035). Hydroelectric development, mining electrification, and activity around data infrastructure support demand. Procurement is shaped by geographic complexity and the need for dependable equipment across dispersed industrial and utility assets.
Mexico
Mexico generated USD 2.3 billion in 2025 and is expected to account for 14.4% of the North American market by 2035. Nearshoring is expanding demand from automotive, electronics, and consumer-goods manufacturing. Industrial investment is supplemented by commercial construction and ongoing requirements for sub-distribution equipment.
Europe Low Voltage (LV) Switchgear Market Analysis
Europe held 21.1% of the global market in 2025 and is projected to reach USD 16.8 billion by 2035. Distribution-grid modernization, industrial decarbonization, and rigorous compliance expectations support demand for type-tested and digitally capable assemblies. The region's procurement culture rewards documented performance, established channel support, and lifecycle-service capability.
Germany
Germany generated USD 1.7 billion in 2025 and is projected to reach USD 3.0 billion by 2035. Grid balancing, renewable integration, and automation investment across manufacturing maintain a diversified demand profile. The market is suited to suppliers with strong technical documentation and industrial customer relationships.
UK
The UK held 11.5% of the European market in 2025 and is forecast to grow at 6.8% CAGR (2026–2035). Offshore wind, data-center activity, and infrastructure investment support switchgear demand. Projects increasingly prioritize resilient, efficient electrical distribution and maintainable protection equipment.
France
France generated USD 976 million in 2025 and is projected to account for 10.7% of the European market by 2035. Building renovation, mobility infrastructure, and power-system investment provide several demand channels. Suppliers must navigate a market where quality, standards compliance, and installed-base service remain important differentiators.
Italy
Italy held 9.5% of the European market in 2025 and is projected to reach USD 1.7 billion by 2035. Renewable investment and replacement demand in established manufacturing clusters support the market. Local engineering knowledge and responsive channels can be important in fragmented project environments.
Spain
Spain generated USD 660 million in 2025 and is expected to grow at 6.0% CAGR (2026–2035). Solar deployment and grid modernization underpin demand for distribution and interconnection equipment. The opportunity is strengthened by projects that require equipment capable of managing changing generation patterns.
Asia Pacific Low Voltage (LV) Switchgear Market Analysis
Asia Pacific held 36.6% of global revenue in 2025 and is projected to reach USD 32.0 billion by 2035. The region combines large-scale grid investment, industrial development, urban construction, and renewable deployment. Its breadth creates room for both global OEMs and domestic suppliers, although pricing, certification, and channel requirements differ substantially across national markets.
China
China generated USD 8.6 billion in 2025 and is expected to account for 45.9% of the Asia Pacific market by 2035. Grid modernization, renewable capacity deployment, and charging-network expansion sustain high procurement volumes. Market participants must balance scale and delivery capacity with a competitive domestic supplier environment.
India
India held 13.2% of the Asia Pacific market in 2025 and is expected to grow at 11.5% CAGR (2026–2035). Industrial investment, electrification programs, renewable procurement, and commercial development create a strong growth environment. The opportunity favors product portfolios that address both cost sensitivity and demanding infrastructure applications.
Japan
Japan generated USD 1.5 billion in 2025 and is projected to reach USD 2.4 billion by 2035. Grid resilience, precision manufacturing, and distributed-energy integration support replacement and upgrade demand. Reliability, long lifecycle performance, and qualification credentials remain central to supplier positioning.
South Korea
South Korea held 5.8% of the Asia Pacific market in 2025 and is projected to grow at 6.1% CAGR (2026–2035). Semiconductor, display, and data-center investments require dependable power-distribution infrastructure. Demand is skewed toward technically capable assemblies that support high-load, high-availability operations.
Australia
Australia generated USD 489 million in 2025 and is projected to reach USD 930 million by 2035. Renewable projects, mining electrification, and utility investment broaden the demand base. Remote-project execution and harsh operating conditions increase the value of serviceability and robust engineering.
Latin America Low Voltage (LV) Switchgear Market Analysis
Latin America held 3.5% of global revenue in 2025 and is projected to reach USD 3.1 billion by 2035. Demand is concentrated in large national markets but is supported more broadly by renewable investment, grid expansion, and industrial development. Economic volatility and financing conditions can influence project timing, making supplier flexibility important.
Brazil
Brazil generated USD 878 million in 2025 and is projected to reach USD 1.8 billion by 2035. Electrification initiatives, manufacturing activity, and renewable-energy development support a wide range of distribution requirements. Local market coverage and application-specific engineering are material competitive considerations.
Argentina
Argentina held 14.0% of the Latin American market in 2025 and is expected to grow at 5.4% CAGR (2026–2035). Grid rehabilitation and energy-infrastructure work provide a baseline for demand, although macroeconomic conditions can affect the pace of capital deployment. Suppliers with flexible commercial structures may be better positioned to manage timing risk.
Middle East & Africa Low Voltage (LV) Switchgear Market Analysis
Middle East & Africa generated USD 2.4 billion in 2025 and is forecast to grow at 8.7% CAGR (2026–2035). Diversification programs, urban development, industrial projects, and electrification needs create a growth-oriented market. Project execution, specification standards, financing, and local service capability vary considerably across the region.
Saudi Arabia
Saudi Arabia generated USD 641 million in 2025 and is projected to reach USD 1.7 billion by 2035. Large-scale development, industrial investment, and renewable programs support demand across utility, commercial, and industrial channels. The scale of planned projects rewards suppliers able to provide qualified products and reliable execution support.
UAE
The UAE held 20.0% of the Middle East & Africa market in 2025 and is expected to grow at 10.9% CAGR (2026–2035). Data centers, premium real estate, renewable installations, and industrial facilities support demand for higher-specification assemblies. International compliance and digital-capability requirements can influence vendor selection.
Turkey
Turkey generated USD 288 million in 2025 and is expected to account for 9.9% of the Middle East & Africa market by 2035. Industrial production and renewable investment support steady demand, while the country's position across regional trade routes supports infrastructure activity. Market participation requires sensitivity to local procurement dynamics and price positioning.
South Africa
South Africa held 9.1% of the Middle East & Africa market in 2025 and is projected to reach USD 370 million by 2035. Grid rehabilitation, independent-power projects, and mining electrification sustain demand. Equipment reliability and service support are important where operating continuity is critical.
Egypt
Egypt generated USD 168 million in 2025 and is expected to grow at 8.5% CAGR (2026–2035). Urban-development projects, energy infrastructure, and renewable awards create opportunities across multiple end uses. Procurement performance will depend on project financing and suppliers' ability to support large, multi-stage installations.
GMI Analyst View
We interpret the regional mix as a shift toward markets where electrification is still being built out alongside demand in mature regions focused on replacement and modernization. OEMs that tailor product specification, channel coverage, and service models to local execution realities should have a clearer path to converting regional growth into durable share gains.
Low Voltage (LV) Switchgear Market Share & Competitive Landscape
The Low Voltage (LV) Switchgear Market share structure is moderately concentrated: Schneider Electric, Siemens, Eaton, ABB, and Legrand together held 61.3% in 2025. Scale matters because global OEMs can combine certification depth, broad product portfolios, established distribution, and service infrastructure, while regional fabricators often compete through responsiveness, customization, and price.
Schneider Electric held 26.7% market share in 2025. Its competitive position is reinforced by integrated energy-management and connected-protection offerings that allow customers to link switchgear with facility, industrial, and utility operating systems. This platform orientation is particularly relevant where customers prioritize visibility, lifecycle management, and coordinated electrical infrastructure.
Siemens held 9.7% market share in 2025. The company competes through a broad electrical-products portfolio and a strong Smart Infrastructure position, addressing requirements from standard distribution through more digitally enabled installations. Its strength lies in the ability to pair protection equipment with adjacent automation, monitoring, and building-infrastructure capabilities.
Eaton held 8.6% market share in 2025. Its emphasis on electrical infrastructure, engineered solutions, and critical-power applications positions it well in data-center, utility, and industrial opportunities. Eaton completed the acquisition of Fibrebond in April 2025, expanding its ability to offer pre-integrated modular power enclosures for these end markets [6].
ABB & GE Vernova remains major participant through their electrification portfolio, including air circuit breakers, molded-case circuit breakers, and compact protection devices. Its position is supported by established industrial and utility relationships, as well as a portfolio that addresses smart-power and building-distribution requirements.
Fuji Electric, Mitsubishi Electric, Toshiba, LS Electric, HD Hyundai Electric, and Hyosung Heavy Industries bring strong positions in Asian industrial, utility, and manufacturing environments. Their regional footprint, factory-automation relationships, and broad electrical-equipment capabilities support participation in switchgear projects requiring local engineering and service access.
Bharat Heavy Electricals and CG Power and Industrial Solutions are significant participants in India, where domestic manufacturing relationships, infrastructure procurement, and electrification investment shape competitive access. Their market relevance is linked to the ability to serve both industrial and utility-facing requirements.
E+I Engineering, IEM, G&W Electric, Lucy Group, nVent, Ormazabal, and Skema demonstrate the importance of application specialization. Competitive differentiation can stem from custom engineering, critical-power expertise, automated switching, distribution-network capability, modular power systems, or renewable-interconnection experience.
nVent completed its acquisition of the Electrical Products Group of Avail Infrastructure Solutions in May 2025, adding switchgear, enclosure, and bus-system capabilities serving utility, data-center, and renewable applications [5]. The transaction illustrates how strategic acquisitions are being used to build more integrated electrical-infrastructure offerings and to reduce execution complexity for end users.
Recent Industry Developments
nVent completes acquisition of Avail Infrastructure Solutions' Electrical Products Group (May 2025). nVent acquired the Electrical Products Group business, expanding its portfolio in switchgear, enclosures, and bus systems for power utilities, data centers, and renewable-energy installations [5].
Eaton completes acquisition of Fibrebond (April 2025). Eaton acquired Fibrebond, strengthening its capacity to deliver pre-integrated modular power-enclosure solutions to data-center, utility, and industrial customers [6].
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.