
Digital Twin Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research approach
1.2 Quality Commitments
1.2.1 GMI AI policy & data integrity commitment
1.2.1.1 Source consistency protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial list of primary sources
1.5 Data mining sources
1.5.1 Paid sources
1.5.1.1 Sources, by region
1.6 Base estimates and calculations
1.6.1 Base year calculation
1.7 Forecast model
1.7.1 Quantified market impact analysis
1.7.1.1 Mathematical impact of growth parameters on forecast
1.8 Research transparency addendum
1.8.1 Source attribution framework
1.8.2 Quality assurance metrics
1.8.3 Our commitment to trust
Chapter 2. Executive Summary
2.1 Industry 360° synopsis
2.2 Key market trends
2.2.1 Offering trends
2.2.2 Solution trends
2.2.3 Deployment mode trends
2.2.4 Enterprise size trends
2.2.5 Technology trends
2.2.6 End-use trends
2.2.7 Regional trends
2.3 TAM analysis, 2026–2035
2.4 CXO perspectives: strategic imperatives
Chapter 3. Industry Insights
3.1 Industry ecosystem analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost structure
3.1.4 Value addition at each stage
3.1.5 Factors affecting the value chain
3.1.6 Disruptions
3.2 Industry impact forces
3.2.1 Growth drivers
3.2.1.1 Demand for Asset Optimization and Reduced Downtime
3.2.1.2 Cost Reduction Through Virtual Commissioning
3.2.1.3 Growing Focus on Sustainability and Energy Efficiency
3.2.1.4 Rising Digitalization Across Industries
3.2.2 Industry pitfalls and challenges
3.2.2.1 High Implementation Costs
3.2.2.2 Cybersecurity and Regulatory Compliance
3.2.3 Market opportunities
3.2.3.1 Development of Industry-Specific Digital Twin Solutions
3.2.3.2 Growing Use in Smart Cities and Urban Planning
3.2.3.3 Use in Sustainability and Energy Consumption Optimization
3.2.3.4 Expansion in Small and Medium-Sized Enterprises (SMEs)
3.3 Growth Potential Analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
3.5 Regulatory Landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia-Pacific
3.5.4 Latin America
3.5.5 Middle East and Africa
3.6 Porter’s Analysis
3.7 PESTEL Analysis
3.8 Trade Data Analysis (Based on Paid Database)
3.8.1 Import/Export Volume & Value Trends
3.8.2 Key Trade Corridors & Tariff Impact
3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
3.10 Patent Analysis
3.11 Technology & Innovation Landscape
3.11.1 Current Technology Trends
3.11.2 Emerging Technology Trends
3.12 Cost Breakdown Analysis, 2025
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company market share analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia-Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East and Africa
4.2.2 Market Concentration Analysis
4.3 Competitive analysis of major market players
4.4 Competitive positioning matrix
4.5 Key developments
4.5.1 Mergers & acquisitions
4.5.2 Partnerships & collaborations
4.5.3 New product launches
4.5.4 Expansion plans and funding
4.6 Company tier benchmarking
4.6.1 Tier classification criteria & qualifying thresholds
4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5. Market Estimates and Forecast, By Offering, 2022–2035 ($ Million, Units)
5.1 Key trends
5.2 Hardware
5.2.1 Sensors
5.2.2 Networking Devices
5.2.3 Data Storage & Computing Devices
5.2.4 Power & Support Infrastructure
5.2.5 Controllers
5.2.6 Others
5.3 Software
5.4 Services
5.4.1 Professional Services
5.4.1.1 System Integration
5.4.1.2 Training & Consulting
5.4.1.3 Support & Maintenance
5.4.2 Managed Services
Chapter 6. Market Estimates and Forecast, By Solution, 2022–2035 ($ Million)
6.1 Key trends
6.2 Process Twin
6.3 System Twin
6.4 Product Twin
Chapter 7. Market Estimates and Forecast, By Deployment Mode, 2022–2035 ($ Million)
7.1 Key trends
7.2 Cloud
7.3 On-premises
7.4 Hybrid
Chapter 8. Market Estimates and Forecast, By Enterprise Size, 2022–2035 ($ Million)
8.1 Key trends
8.2 SME
8.3 Large Enterprises
Chapter 9. Market Estimates and Forecast, By Technology, 2022–2035 ($ Million)
9.1 Key trends
9.2 Artificial Intelligence and Machine Learning
9.3 IoT and Industrial IoT (IIoT)
9.4 Augmented Reality (AR) and Virtual Reality (VR)
9.5 Blockchain
9.6 Others
Chapter 10. Market Estimates and Forecast, By End Use, 2022–2035 ($ Million)
10.1 Key trends
10.2 Manufacturing
10.3 Healthcare
10.4 Automotive and Transportation
10.5 Aerospace and Defense
10.6 Smart Cities
10.7 Energy and Utilities
10.8 Telecommunications
10.9 Others
Chapter 11. Market Estimates and Forecast, By Region, 2022–2035 ($ Million)
11.1 Key trends
11.2 North America
11.2.1 US
11.2.2 Canada
11.3 Europe
11.3.1 Germany
11.3.2 UK
11.3.3 France
11.3.4 Italy
11.3.5 Spain
11.3.6 Netherlands
11.3.7 Rest of Europe
11.4 Asia Pacific
11.4.1 China
11.4.2 India
11.4.3 Japan
11.4.4 Australia
11.4.5 South Korea
11.4.6 Rest of Asia-Pacific
11.5 Latin America
11.5.1 Brazil
11.5.2 Mexico
11.5.3 Argentina
11.5.4 Rest of Latin America
11.6 Middle East and Africa
11.6.1 South Africa
11.6.2 Saudi Arabia
11.6.3 UAE
11.6.4 Rest of Middle East and Africa
Chapter 12. Company Profiles
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Preeti Wadhwani. 2026, September. Digital Twin Market Size - By Offering, By Solution, By Deployment Mode, By Enterprise Size, By Technology, By End Use, Growth Forecast, 2026 - 2035 (Report ID: GMI2196). Global Market Insights Inc. Retrieved November 2, 2026, from https://www.gminsights.com/toc/details/digital-twin-market

Digital Twin Market
Get a free sample of this report
Digital Twin Market Size
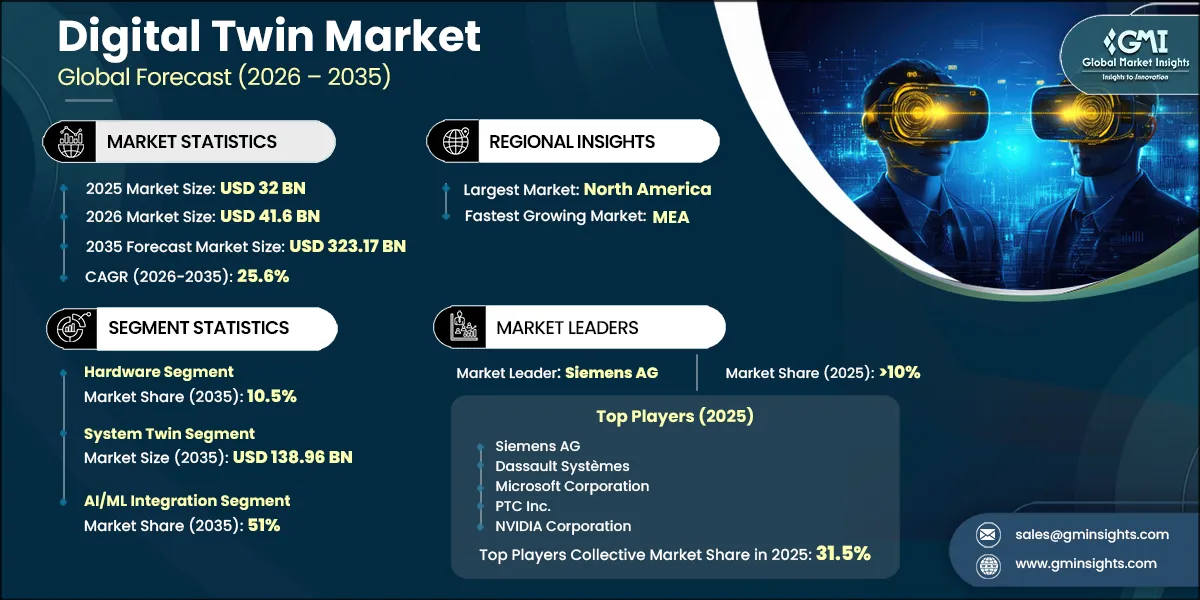
The digital twin market was valued at USD 32 billion in 2025, is forecast to generate USD 41.60 billion in 2026, will advance at a 25.6% CAGR (2026-2035), and is projected to reach USD 323.17 billion by 2035.
The digital twin market is moving from discrete engineering use cases toward persistent operational systems that connect physical assets, simulation models, and enterprise workflows. Demand is increasingly shaped by deployments that combine real-time data, AI-assisted interpretation, and lifecycle management, allowing customers to extend an initial asset-monitoring implementation across facilities, product programs, and supply chains.
GMI Analyst View
Based on input from industry leaders, we find that the digital twin market generated USD 27.00 billion in 2024. That scale indicates that enterprise procurement had moved beyond experimental spending before the forecast period, with recurring platform, integration, and managed-service commitments providing a more durable foundation for subsequent adoption.
Digital Twin Market Trends, Growth Drivers & GMI Forecast Outlook
Digital twin demand is being reshaped by the convergence of low-latency connectivity, AI-enabled simulation, and regulatory requirements for traceable product and asset data. The strongest opportunities favor platforms that can translate complex operational data into deployable decisions while meeting security, interoperability, and data-governance requirements.
Key Drivers
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Low-latency connectivity changes the commercial value of a digital twin by enabling a virtual model to reflect operating conditions closely enough to support time-sensitive decisions. This is particularly relevant in factory automation, urban infrastructure, and autonomous systems, where delayed data can limit the usefulness of simulation outputs. As connectivity improves, buyers can justify broader deployments that link assets, processes, and enterprise data rather than maintaining isolated pilots.
Platform consolidation is also reducing the burden on organizations that would otherwise assemble simulation, data-management, and AI capabilities from separate vendors. Integrated portfolios can shorten technical validation and procurement cycles, although they also raise the importance of open interfaces and migration options for customers seeking to avoid excessive dependence on a single stack.
Digital Product Passport requirements create a separate, compliance-led route to adoption. Manufacturers serving European value chains need reliable lifecycle data, provenance, and product-state visibility. Digital twin platforms can become the operating layer through which this information is governed and updated, making the opportunity less sensitive to discretionary technology budgets than conventional optimization projects.
Key Restraints
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Security is not an ancillary design consideration for a live digital twin. Connecting operational technology with enterprise systems expands the potential attack surface and places security architecture at the center of board-level deployment decisions. Operators of critical assets are therefore more likely to select suppliers that can demonstrate segmentation, identity controls, secure data flows, and credible incident-response practices. IBM identifies data-breach disruption as a material enterprise risk, reinforcing the scrutiny attached to connected operating environments [4].
The intellectual-property issue is distinct from general cyber risk. A product or process twin can contain engineering parameters, operating procedures, and performance histories that are commercially sensitive even when they do not control an asset directly. This concern supports the continued relevance of hybrid and on-premises architectures in high-value manufacturing, aerospace, defense, and other sectors where data exposure can alter a customer's competitive position [4].
Interoperability remains a practical adoption constraint because many customers operate environments built around different automation, PLM, cloud, and analytics standards. The resulting middleware and integration work can undermine an otherwise attractive business case, especially for smaller firms. Suppliers that combine broad connector libraries with proven OT integration capabilities are better positioned to convert pilots into estate-wide programs.
GMI Analyst View
We see adoption becoming increasingly selective rather than uniformly frictionless. Compliance obligations and operational urgency can accelerate buying decisions, but enterprise-scale awards will favor providers that make security, data ownership, and interoperability credible at the architectural level, not merely in product demonstrations.
Digital Twin Market Segment Analysis
By Offering
Hardware
Hardware represented 18.0% of the digital twin market in 2025 and is expected to account for 10.5% in 2035. The declining mix reflects the maturation of sensors, gateways, and edge connectivity after the first deployment phase. Hardware remains essential to physical-data capture, but differentiation increasingly migrates toward the software and services that interpret, govern, and operationalize those data streams.
Software
Software generated USD 17.28 billion in 2025 and is projected to reach USD 199.78 billion by 2035. Software is the market's principal value-capture layer because it connects simulation, visualization, AI, workflow orchestration, and digital-thread management. Platform depth, extensibility, and the ability to support multiple asset classes will shape supplier positioning as customers seek to scale beyond individual use cases.
Services
Services accounted for 28.0% of market revenue in 2025 and are forecast to grow at a 25.4% CAGR (2026-2035). Implementation, model calibration, data engineering, and managed operations remain difficult to internalize for many users. Services demand should therefore remain embedded in long-duration customer relationships, particularly where legacy equipment, fragmented data, or regulated operating environments complicate deployment.
By Solution
System Twin
System twins held 45.0% of the digital twin market in 2025 and are expected to generate USD 138.96 billion by 2035. Their position reflects the need to understand interactions among assets rather than optimize equipment in isolation. Grid operators, industrial campuses, airports, and complex facilities use system-level models where performance depends on network behavior, operational constraints, and changing conditions across interconnected components.
Product Twin
Product twins generated USD 11.20 billion in 2025 and are forecast to expand at a 25.4% CAGR (2026-2035). Product-focused demand is anchored in virtual design, engineering validation, and lifecycle feedback. Manufacturers can reduce physical iteration while using operational data to inform design changes, which makes this solution category strategically relevant to automotive, aerospace, industrial equipment, and increasingly regulated product sectors.
Process Twin
Process twins accounted for 20.0% of the market in 2025 and are projected to reach USD 72.71 billion by 2035. Process modeling is gaining importance where throughput, yield, energy consumption, and compliance must be optimized simultaneously. Its value lies in revealing operational trade-offs that asset-level monitoring alone cannot capture, especially in energy-intensive and highly controlled production settings.
By Technology
AI/ML Integration
AI/ML integration represented 40.0% of the digital twin market in 2025 and is expected to reach 51.0% by 2035. AI capabilities shift digital twins from descriptive visualization toward prediction and decision support. The commercial advantage will depend on domain-specific model performance, data quality, explainability, and the ability to embed recommendations in the customer's existing operational workflow.
IoT/IIoT
IoT/IIoT generated USD 9.60 billion in 2025 and is projected to grow at a 23.6% CAGR (2026-2035). Connected sensing remains the foundation for live synchronization, even as its growth trails higher-value intelligence layers. Buyers will continue to require robust device management, data reliability, and integration with operational systems before advanced analytics can produce trusted outputs.
AR/VR
AR/VR held 12.0% of the market in 2025 and is forecast to reach USD 43.62 billion by 2035. Immersive interfaces extend the practical use of digital twins into maintenance, field inspection, training, and collaborative design. Their adoption is strongest where personnel need to interpret complex spatial information rapidly or perform work in environments where conventional screens are less useful.
Blockchain
Blockchain accounted for 5.0% of the market in 2025 and is forecast to grow at a 20.7% CAGR (2026-2035). The technology is most relevant where traceability, provenance, and verifiable records are central to the deployment case. Its narrower addressable base reflects the integration and governance burden involved, but it can remain strategically important in regulated and security-sensitive applications.
By Deployment
Cloud
Cloud deployments accounted for 56.0% of the digital twin market in 2025 and are expected to represent 67.0% by 2035. Cloud platforms support centralized model management, scalable compute, and access to AI resources across distributed operations. Their appeal is strongest for organizations managing multiple sites or requiring collaboration across product, engineering, and operations teams.
On-Premises
On-premises deployments generated USD 8.32 billion in 2025 and are forecast to expand at a 16.3% CAGR (2026-2035). This model remains relevant where data sovereignty, air-gapped infrastructure, or critical-operating requirements limit the feasibility of a fully cloud-hosted architecture. Suppliers that can support secure local deployment without restricting lifecycle updates retain a meaningful role in sensitive accounts.
Hybrid
Hybrid deployments represented 18.0% of the market in 2025 and are projected to reach USD 64.63 billion by 2035. Hybrid architectures give customers a practical compromise between local control and cloud-scale analytics. They are particularly suited to industrial sites that must process latency-sensitive data locally while centralizing model training, long-term storage, and enterprise reporting.
By Enterprise Size
Large Enterprise
Large enterprises held 75.0% of the digital twin market in 2025 and are expected to account for 62.0% by 2035. Their installed asset bases and integration budgets continue to make them the market's largest customers. However, their procurement processes increasingly emphasize interoperability, governance, and deployment repeatability, which rewards vendors able to industrialize implementations across business units.
SME
SMEs generated USD 8.00 billion in 2025 and are forecast to grow at a 31.6% CAGR (2026-2035). The SME opportunity depends on reducing configuration and implementation complexity. Modular subscriptions, preconfigured connectors, and specialist implementation partners can lower the threshold for adoption, allowing smaller manufacturers to deploy targeted use cases before committing to a broader transformation program.
By End Use
Manufacturing
Manufacturing represented 34.0% of the digital twin market in 2025 and is projected to generate USD 92.10 billion by 2035. Manufacturers apply digital twins across product development, virtual commissioning, maintenance, production optimization, and supply-chain coordination. The sector's breadth gives it an advantage because the same platform can support multiple operational functions once reliable data pipelines have been established.
Automotive
Automotive generated USD 5.12 billion in 2025 and is expected to account for 16.0% of market revenue in 2035. Electrification, software-defined vehicles, virtual validation, and supply-chain visibility preserve the sector's demand for product and process twins. The strategic requirement is to integrate engineering simulation with production and field-performance feedback rather than run those environments separately.
Aerospace & Defense
Aerospace and defense held 14.0% of the market in 2025 and are forecast to reach USD 40.39 billion by 2035. Long asset lifecycles, exacting validation needs, and the cost of physical testing support use cases spanning design, certification, maintenance, and mission readiness. Secure architecture and controlled data access remain decisive purchasing criteria in this vertical.
Energy & Utilities
Energy and utilities generated USD 3.84 billion in 2025 and are expected to grow at a 27.2% CAGR (2026-2035). Grid modernization, asset reliability, and integration of variable generation create a strong need for models that can evaluate system behavior under changing conditions. Digital twins are valuable where operators must anticipate constraints before they become outages, safety events, or inefficient dispatch decisions.
Healthcare
Healthcare accounted for 10.0% of the market in 2025 and is expected to represent 13.5% by 2035. Healthcare adoption spans operational models for facilities and patient flow as well as simulation-led development and evaluation. Progress will depend on the ability to establish trustworthy data governance and demonstrate clinical or operational validity within demanding regulatory and care-delivery environments.
Smart Cities
Smart cities generated USD 2.24 billion in 2025 and are projected to reach USD 27.46 billion by 2035. Urban deployments combine transport, utilities, construction, emergency planning, and public-asset management. Their procurement cycles are shaped by public-sector governance and long-lived infrastructure requirements, favoring suppliers that can integrate heterogeneous systems without compromising data control.
Telecommunications
Telecommunications accounted for 4.0% of the market in 2025 and are forecast to grow at a 24.9% CAGR (2026-2035). Network twins allow operators to test changes in coverage, capacity, and configuration before physical execution. The wider rollout of advanced networks strengthens the use case for simulation-led planning and operations, particularly where live infrastructure changes would otherwise be expensive or disruptive [1].
GMI Analyst View
We believe the segment picture is best understood as an architectural reallocation of value. The market is not abandoning connectivity or simulation; rather, customers are placing more value on intelligence, interoperability, and operational execution, creating an advantage for vendors that can make complex capabilities usable outside specialist engineering teams.
Digital Twin Market Regional Analysis
North America Digital Twin Market Analysis
North America held 43.0% of the digital twin market in 2025 and is projected to generate USD 122.80 billion by 2035. The region benefits from mature industrial software adoption, substantial cloud and AI infrastructure, and demand from manufacturing, energy, aerospace, defense, and buildings. Growth will be shaped by the ability of suppliers to connect existing OT estates to secure, scalable enterprise platforms.
United States
The United States generated USD 12.16 billion in 2025 and is projected to reach USD 106.20 billion by 2035. U.S. demand combines defense digital-engineering requirements with private investment in manufacturing modernization, energy resilience, mobility, and health-system operations. Its scale also makes it a critical reference market for vendors developing verticalized solutions and partner ecosystems.
Canada
Canada accounted for 8.0% of North American revenue in 2025 and is forecast to grow at a 25.0% CAGR (2026-2035). Resource optimization, utilities modernization, and a growing implementation-services base support adoption. The market is well placed for targeted deployments that translate asset-data investments into repeatable applications for industrial and public-infrastructure operators.
Europe Digital Twin Market Analysis
Europe generated USD 8.96 billion in 2025 and is expected to account for 26.0% of the digital twin market in 2035. European demand combines an established industrial base with regulatory pressure for traceability and lifecycle-data management. Digital Product Passport requirements can give platforms a more direct role in compliance workflows, especially for manufacturers operating complex cross-border supply chains.
Germany
Germany generated USD 2.72 billion in 2025 and is projected to reach USD 25.53 billion by 2035. Automotive, machinery, and process industries provide a deep base for engineering-led twin deployments. The country's opportunity is reinforced by the need to modernize industrial data practices without disrupting the specialized production environments that underpin its export-oriented manufacturing base.
United Kingdom
The United Kingdom represented 21.4% of European revenue in 2025 and is forecast to grow at a 24.0% CAGR (2026-2035). Aerospace, advanced manufacturing, operational resilience, and health infrastructure create a diversified use-case base. Adoption will depend on translating strong engineering and software capabilities into deployments that can scale across complex institutional and supplier environments.
France
France generated USD 1.07 billion in 2025 and is projected to reach USD 10.01 billion by 2035. Aerospace, defense, energy, and public-sector infrastructure provide distinct demand channels. The market is particularly suited to high-value deployments where simulation, lifecycle control, and stringent operating standards are integrated into established industrial programs.
The Netherlands, Sweden, Italy, and Spain add further European demand through logistics, industrial automation, precision manufacturing, renewable energy, and municipal digitalization. Their diverse use cases make regional partner capability and local systems integration important to supplier expansion.
Asia Pacific Digital Twin Market Analysis
Asia Pacific accounted for 22.0% of the digital twin market in 2025 and is projected to generate USD 90.48 billion by 2035. The region's opportunity is driven by industrial automation, government-backed digitalization, smart-infrastructure investment, and increasingly capable domestic platform ecosystems. Demand patterns vary markedly by country, requiring suppliers to align product architecture and channels with national industrial priorities.
China
China accounted for 40.9% of Asia Pacific revenue in 2025 and is projected to reach USD 41.25 billion by 2035. Its extensive manufacturing base, smart-city investment, and domestic software ecosystem make China one of the largest country opportunities for industrial and urban twins. Competitive success depends on local integration capacity, data-governance alignment, and support for high-volume deployment models.
Japan
Japan generated USD 1.60 billion in 2025 and is forecast to grow at a 26.7% CAGR (2026-2035). Automotive, precision machinery, and electronics manufacturers are extending use cases from maintenance toward product development and supply-chain simulation. Established OEM-supplier networks can help diffuse adoption once successful deployment patterns are proven.
India
India represented 10.0% of Asia Pacific revenue in 2025 and is forecast to grow at a 34.5% CAGR (2026-2035). Industrial policy, digital-services capability, and urban infrastructure programs support a broadening opportunity. The pace of adoption will depend on whether providers can make implementation cost-effective for a diverse base of manufacturers and public-sector operators.
South Korea
South Korea generated USD 563.20 million in 2025 and is projected to reach USD 7.18 billion by 2035. Shipbuilding, semiconductor production, and electronics manufacturing offer sophisticated operating environments for real-time simulation. Broader growth will require solutions that extend the benefits achieved by large conglomerates into supplier and SME networks.
Australia
Australia accounted for 6.0% of Asia Pacific revenue in 2025 and is forecast to grow at a 25.0% CAGR (2026-2035). Mining and resource operations remain major adoption anchors because asset availability, safety, and remote operations materially affect economics. Buildings, energy infrastructure, and public assets create opportunities to diversify demand beyond the resource sector.
Latin America Digital Twin Market Analysis
Latin America accounted for 4.0% of the digital twin market in 2025 and is projected to generate USD 12.92 billion by 2035. The region's growth is linked to energy assets, manufacturing investment, nearshoring, and urban infrastructure. Deployment models that accommodate uneven connectivity, legacy operations, and localized service capacity will be important to converting interest into scaled contracts.
Brazil
Brazil represented 52.0% of Latin American revenue in 2025 and is projected to reach USD 7.26 billion by 2035. Offshore energy, industrial operations, agribusiness, and urban infrastructure give Brazil a broad application base. Vendors that can demonstrate asset reliability and operational efficiency gains will be better positioned than those offering generic platform narratives.
Mexico
Mexico generated USD 358.40 million in 2025 and is forecast to grow at a 24.5% CAGR (2026-2035). Nearshoring brings local production facilities into more tightly integrated North American supply chains. This creates demand for platforms that support visibility, engineering coordination, and process standardization across parent companies, suppliers, and regional plants.
MEA Digital Twin Market Analysis
MEA generated USD 960 million in 2025 and is forecast to expand at a 29.7% CAGR (2026-2035). State-led infrastructure programs, energy-asset optimization, and smart-city investment underpin regional growth. Procurement can be concentrated and project-led, making sovereign priorities, local delivery capability, and data-residency requirements central to market access.
Saudi Arabia
Saudi Arabia accounted for 28.0% of MEA revenue in 2025 and is forecast to grow at a 32.2% CAGR (2026-2035). Large-scale infrastructure and energy programs create opportunities for city-scale, construction, and industrial applications. Suppliers must demonstrate the ability to support long-duration programs in which design, construction, and operating data need to remain connected.
UAE
The UAE generated USD 211.20 million in 2025 and is projected to reach USD 3.02 billion by 2035. Urban management, real estate, logistics, and energy diversification support demand. The country's role as a regional technology hub can amplify reference-customer effects when public deployments demonstrate practical operational outcomes.
South Africa
South Africa represented 12.0% of MEA revenue in 2025 and is projected to reach USD 1.16 billion by 2035. Mining, water, and utilities offer immediate asset-performance use cases. The market also provides a potential entry point for suppliers pursuing wider sub-Saharan infrastructure and industrial modernization opportunities.
Israel
Israel generated USD 96 million in 2025 and is projected to reach USD 1.22 billion by 2035. The country's cybersecurity, engineering, and technology ecosystem supports both domestic deployment and solution innovation. Secure architectures for critical infrastructure and defense-related applications can be a differentiating area for locally developed capabilities.
GMI Analyst View
We find that regional expansion requires differentiated commercial execution, not a single global playbook. Mature markets emphasize integration with established industrial systems, while scaling markets depend more heavily on public investment, local service capacity, and the ability to adapt architectures to national data and operating requirements.
Digital Twin Market Share & Competitive Landscape
The digital twin market share structure is moderately concentrated among leading platform providers, while specialist vendors, integrators, and regional suppliers retain substantial room to compete through vertical expertise and customer proximity. The top five vendors collectively accounted for 31.5% of the market in 2025, leaving competition shaped by platform breadth, installed base access, implementation capability, and credibility in regulated operating environments.
Siemens AG
Siemens AG held a 10.0% market share in 2025. Its Xcelerator portfolio links automation, engineering, simulation, and data capabilities, giving the company a strong position in industrial deployments where customers want a unified operating environment. Its acquisition of Altair broadened the company's simulation and AI capabilities, strengthening its ability to address customers seeking integrated industrial software rather than separately sourced tools [2].
Dassault Systèmes
Dassault Systèmes held a 9.5% market share in 2025. The company's 3DEXPERIENCE platform is deeply embedded in product and system-twin workflows in aerospace, automotive, and life sciences, where continuity from design through lifecycle management creates high switching costs. Its expanded relationship with Airbus demonstrates the value of long-horizon platform commitments in complex engineering ecosystems.
Microsoft Corporation
Microsoft Corporation held a 5.0% market share in 2025. Azure Digital Twins, Azure IoT services, and the broader Azure data and AI environment provide an attractive route for enterprises seeking to extend an existing cloud estate. Microsoft's advantage is ecosystem integration, while its challenge is to maintain sufficient domain specificity in industrial settings where customers require proven operational-technology expertise.
PTC and NVIDIA complete the top tier through complementary strengths. PTC combines IIoT, PLM, and augmented-reality capabilities for industrial customers, while NVIDIA supplies high-performance computing and simulation infrastructure that supports both proprietary and third-party twin environments. Honeywell, Emerson, Schneider Electric, ABB, GE Vernova, and Rockwell Automation use installed automation relationships to compete in operationally intensive sectors, while Bentley Systems, Hexagon, IBM, SAP, and Accenture bring infrastructure, engineering, enterprise software, and systems-integration capabilities to specific deployment models.
Emerging and specialized competitors-including C3.ai, Kongsberg Digital, Willow, and Cognite-can win where customers prioritize focused industrial AI, maritime and energy expertise, smart-building operations, or industrial-data contextualization. Competitive intensity will remain high because buyers increasingly seek a combination of vertical competence, open integration, secure deployment, and demonstrable operational outcomes rather than a generic visualization platform.
Recent Industry Developments
Bentley Systems and EARTHBRAIN formed a strategic partnership to integrate Bentley's AI-enabled digital twin technology with EARTHBRAIN's Smart Construction suite. The collaboration is intended to connect construction workflows from design through earthworks and operating stages, illustrating how digital-twin competition is extending from engineering software into site-level execution environments [5].
Eaton collaborated with Autodesk on the Brightlayer Digital Energy Twin, combining energy-management capabilities with Autodesk Tandem for electrical-system simulation and optimization in commercial buildings and data centers. The offering reflects rising demand for tools that connect design-stage decisions with facility operations and energy-performance management [6].
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.