
Authors:
Monali Tayade, Sampada Kulkarni
Download free PDF
Veterinary Orthopedic Implants Market Size & Share 2026-2035
Report ID: GMI4535
|
Published Date: September 2026
|
Report Format: PDF/Excel/Dashboard/Platform
Download Free PDF
Explore Our Licensing Options:
Download Free PDF

Veterinary Orthopedic Implants Market
Get a free sample of this report
What are you hoping to find?
Your PDF is on its way. Tell us little about your research goal, and we'll help you find the most relevant market insights.
Veterinary Orthopedic Implants Market Size
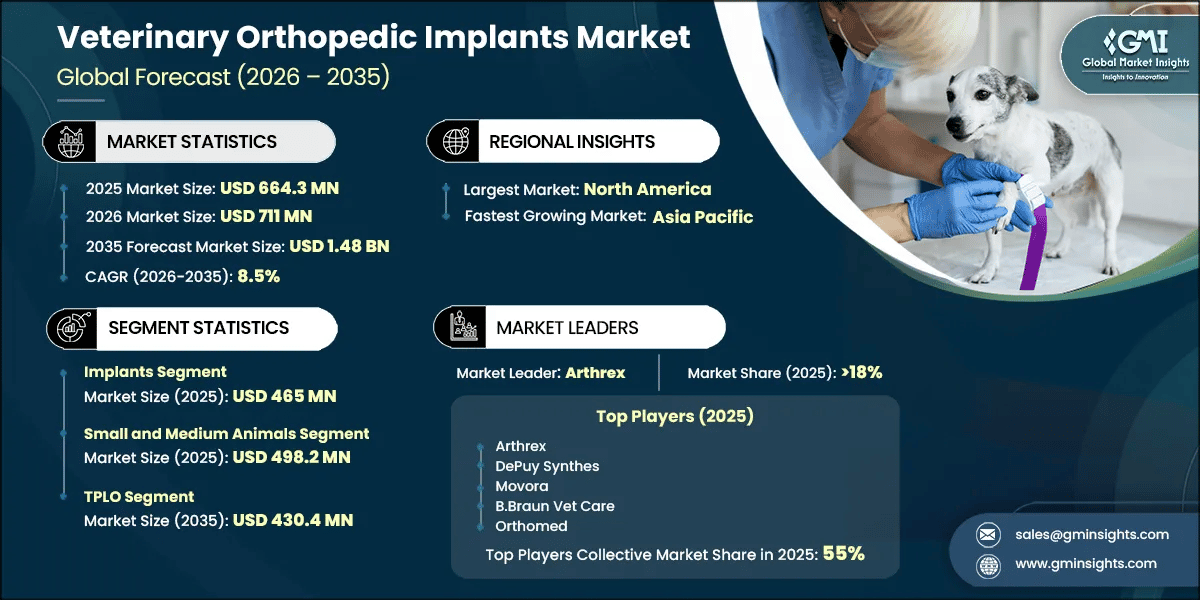
The veterinary orthopedic implants market was valued at USD 664.3 million in 2025, is projected to reach USD 711 million in 2026, is expected to grow at an 8.5% CAGR from 2026 to 2035, and is anticipated to reach USD 1.48 billion by 2035.
Veterinary Orthopedic Implants Market Key Takeaways
Market Leader: Arthrex led with over 18% market share in 2025.
Leading Players: Top 5 players in this market include Arthrex, DePuy Synthes, Movora, B.Braun Vet Care, Orthomed, which collectively held a market share of 55% in 2025.
Veterinary orthopedic implants encompass implantable fixation, arthroplasty, and ligament-repair devices, together with procedure-specific surgical systems used to treat fractures, joint disease, and musculoskeletal injuries in animals. Market expansion reflects rising acceptance of definitive surgical intervention, a widening specialty-care referral base, and growing owner willingness to pursue procedures that preserve mobility and quality of life. Demand is also shifting toward clinically differentiated implant platforms that support more complex reconstruction and reproducible outcomes.
GMI Analyst View
Based on our ongoing engagement with orthopedic specialists and veterinary practitioners across major markets, the veterinary orthopedic implants market expanded at a 6.4% CAGR during 2022–2025. This trajectory indicates that demand was already gaining momentum through broader specialist capacity and more established referral-based surgical practice, rather than being dependent on one procedure category or geography.
Veterinary Orthopedic Implants Market Trends, Growth Drivers & GMI Forecast Outlook
Companion-animal orthopedic care is moving toward earlier specialist referral and more definitive treatment, supporting implant demand across ligament repair, fracture management, and joint reconstruction. Growth remains strongest where surgeon training, hospital infrastructure, and owner financing can develop together, while affordability and uneven large-animal service coverage constrain broader adoption.
Key Drivers
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
The companion-animal population provides the core clinical pipeline for orthopedic intervention [1]. Orthopedic disease in dogs, particularly ligament injury and degenerative joint conditions, is closely tied to the availability of owners willing to enter a specialty-care pathway. As referral networks become more integrated with primary veterinary practice, diagnosis is more likely to translate into a surgical consultation and an implant-supported procedure.
Insurance growth changes the economic threshold for high-cost intervention [2]. When reimbursement absorbs part of the cost of imaging, surgery, anesthesia, and rehabilitation, owners are more likely to select restorative treatment over long-term medical management. This effect favors premium implant categories because the procedures with the greatest clinical complexity also carry the highest financial hurdle without coverage.
Product innovation is expanding the addressable case mix as well as the value of individual procedures. Patient-specific constructs, anatomically matched fixation systems, and more standardized surgical workflows allow specialists to address cases that previously carried greater technical uncertainty. Manufacturer-supported education is equally consequential because it determines whether a product platform can move from leading referral centers into a broader network of capable practices.
Key Restraints
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
The principal barrier to surgical conversion is the financial burden carried by uninsured owners [2]. Advanced orthopedic treatment usually requires specialist consultation, diagnostic imaging, anesthesia, implants, rehabilitation, and follow-up care, making the decision highly sensitive to household resources. Insurance expansion improves access, but its uneven distribution means the market remains dependent on a comparatively narrow set of owners able to fund specialty intervention.
Large-animal orthopedics faces a different constraint set, combining limits on the animal base with a thin clinical delivery network [3]. Rural service shortages can restrict both routine assessment and referral to surgical care, while the economics of treatment are more difficult to justify for production animals. These dynamics keep companion-animal orthopedics as the principal source of sustained market momentum.
The veterinary device framework does not apply the same formal pre-market clearance process used for many human medical devices [4]. As a result, hospital procurement teams and specialist surgeons may favor suppliers with established clinical documentation, training support, and demonstrated product consistency. This strengthens qualification barriers for lesser-known entrants even when those suppliers compete aggressively on price.
GMI Analyst View
We view the market as one in which clinical demand is developing faster than the financing and standardization needed to convert every eligible case into a procedure. The strongest near-term gains will therefore accrue where specialist capacity, owner education, and payment support reinforce one another, rather than across the full animal-health population uniformly.
Veterinary Orthopedic Implants Market Segment Analysis
By Product Type
The Veterinary Orthopedic Implants segment generated USD 465.0 million in 2025 and is projected to account for 73.0% of the global market by 2035. Implants remain the commercial center of orthopedic procedures because they determine clinical indication, procedural workflow, inventory requirements, and much of the surgeon's product selection. The category benefits from a widening shift toward definitive fixation and arthroplasty, where platform differentiation, instrumentation compatibility, and clinical evidence can support premium positioning.
Instruments are expected to generate USD 400.7 million by 2035 and accounted for 30.0% of the global market in 2025. Instrument demand is linked to procedure adoption but follows a different purchasing cycle from implants. Hospitals and referral practices typically invest in procedure-specific sets to establish capability, after which recurring implant use becomes more closely tied to case throughput. Suppliers that pair reliable instruments with workflow training can improve account retention even as the implant component captures a larger share of procedure revenue.
By Animal Size
Small and medium animals generated USD 498.2 million in 2025 and are projected to represent 77.0% of global market revenue by 2035. The small and medium animal segment anchors the Veterinary Orthopedic Implants market because companion animals are more frequently treated in urban referral hospitals with advanced imaging, anesthesia, and rehabilitation capabilities. Stronger owner attachment and the availability of elective surgical pathways also support greater uptake of complex ligament, trauma, and joint procedures.
Large animals accounted for 25.0% of global market revenue in 2025 and are expected to generate USD 341.3 million by 2035. Large-animal demand remains important in equine practice and selected high-value livestock cases, but it is structurally more selective than companion-animal demand. Case economics, travel distances, specialist availability, and the production value of the animal strongly influence treatment decisions, limiting broad-based penetration of advanced implant procedures.
By Procedure
TPLO accounted for 30.0% of the global market in 2025 and is expected to generate USD 430.4 million by 2035. TPLO remains central to canine orthopedic practice because it addresses a common ligament condition through a well-established specialist workflow. Its commercial importance extends beyond procedure volume: it creates demand for dedicated plates, saws, guides, fixation systems, and surgeon training, making it a critical platform for suppliers seeking durable hospital relationships.
Joint replacement generated USD 132.9 million in 2025 and is projected to grow at a 9.7% CAGR from 2026 to 2035. Joint replacement is gaining importance as clinical confidence, implant design, and specialist capability extend arthroplasty beyond a limited number of academic and referral settings. The segment favors companies able to provide an integrated offering that includes implant systems, surgical education, planning support, and post-procedure guidance.
Trauma fixation generated USD 132.9 million in 2025 and is expected to account for 20.2% of the global market by 2035. Trauma fixation benefits from its role in treating acute injury, where surgical intervention is often necessary rather than elective. Demand is supported by continual refinement of plate geometry, locking technologies, and materials that enable more reliable stabilization across a wider range of animal sizes and fracture patterns.
TTA represented 15.0% of the global market in 2025 and is projected to generate USD 192.9 million by 2035. TTA remains a recognized option for cruciate-ligament treatment, particularly where surgeons have established procedural familiarity and patient selection criteria. Its competitive position is shaped by clinical preferences, training pathways, and the relative adoption of TPLO, making supplier education and procedure-specific systems important determinants of demand.
Other procedures generated USD 99.6 million in 2025 and are expected to represent 15.8% of the global market in 2035. Other procedures include applications such as patellar stabilization, spinal fixation, acetabular reconstruction, and specialized fracture repair. This category benefits from the expanding clinical scope of veterinary orthopedics, especially as custom implants and more size-specific systems become accessible to referral centers beyond academic institutions.
By End User
Veterinary hospitals generated USD 584.6 million in 2025 and are projected to account for 89.0% of global market revenue by 2035. Veterinary hospitals dominate demand because orthopedic surgery requires coordinated access to surgical suites, anesthesia, imaging, trained staff, sterilization systems, and recovery care. The increasing complexity of implant-supported intervention further concentrates high-value procedures in facilities that can deliver consistent perioperative management and specialist oversight.
Other end users accounted for 12.0% of global market revenue in 2025 and are expected to generate USD 163.2 million by 2035. Clinics and research institutions remain relevant for lower-complexity procedures, teaching activity, clinical trials, and the evaluation of new implant approaches. However, higher-acuity cases increasingly migrate to specialty hospitals, where equipment availability and referral networks better support technically demanding orthopedic care.
GMI Analyst View
We believe the most consequential segment shift is toward systems that combine procedural complexity with repeatable specialist workflows. Suppliers positioned in arthroplasty, advanced fixation, and companion-animal referral care are likely to capture disproportionate value because their offerings sit where clinical differentiation, training intensity, and hospital purchasing influence are most concentrated.
Veterinary Orthopedic Implants Market Regional Analysis
North America Veterinary Orthopedic Implants Market Analysis
North America generated USD 305.6 million in Veterinary Orthopedic Implants revenue in 2025 and is expected to reach USD 621.8 million by 2035.
The region's leadership rests on mature specialty-hospital infrastructure, extensive surgeon training, established manufacturer and distributor networks, and comparatively strong owner acceptance of advanced veterinary care. Its market remains especially attractive for suppliers that can combine implant breadth with education, logistics reliability, and clinical support.
U.S.
The U.S. generated USD 269.0 million in 2025 and is expected to account for 86.0% of North American revenue by 2035. The U.S. is the primary commercial center of North American veterinary orthopedics, supported by dense referral networks and a broad base of companion-animal specialty practices. It also serves as an important launch market for new fixation and arthroplasty platforms because surgeons, hospitals, and distributors can provide early clinical validation and training capacity.
Canada
Canada is projected to generate USD 87.1 million by 2035 and is expected to grow at a 9.3% CAGR from 2026 to 2035. Canadian demand is supported by expanding specialty-hospital networks in major metropolitan areas and an increasingly formalized referral pathway from primary veterinary care. Growth is reinforced by owner engagement with specialty treatment and a widening base of practices equipped to manage orthopedic cases.
Europe Veterinary Orthopedic Implants Market Analysis
Europe generated USD 192.6 million in 2025 and is anticipated to grow at a 7.2% CAGR from 2026 to 2035. Europe combines established companion-animal care cultures with a diverse specialist infrastructure and a meaningful base of implant and instrument suppliers. Western European markets provide stable demand through mature referral practice, while Southern and Central European markets offer additional expansion potential as private specialty care becomes more accessible.
Germany
Germany generated USD 42.4 million in 2025 and is projected to account for 20.0% of European revenue by 2035. Germany's market is supported by a strong network of specialist clinics and veterinary teaching institutions that sustain demand across fracture fixation, cruciate repair, and arthroplasty. Its established clinical base makes product performance, surgeon education, and supply reliability more important competitive factors than simple market access.
United Kingdom
The United Kingdom is projected to generate USD 73.3 million by 2035 and is expected to grow at a 7.9% CAGR from 2026 to 2035. The United Kingdom benefits from established companion-animal ownership, advanced referral practice, and a strong professional ecosystem for veterinary orthopedic training. Suppliers must navigate a sophisticated market in which clinical evidence, continuing education, and dependable distribution are decisive to account adoption.
France
France accounted for 15.0% of European market revenue in 2025 and is anticipated to grow at a 6.4% CAGR from 2026 to 2035. French demand is increasingly shaped by specialist referrals from primary practices, particularly in metropolitan care corridors. The gradual maturation of owner expectations for advanced treatment is widening the market for implant-supported procedures while preserving a need for clinically credible, economically accessible product portfolios.
Italy
Italy accounted for 10.0% of European revenue in 2025 and is projected to generate USD 38.6 million by 2035. Italy's opportunity is tied to the continued expansion of private referral hospitals and specialist orthopedic capability in major urban areas. Demand development is influenced by differences in household spending capacity and service availability, which favor suppliers able to offer strong education and flexible access to procedure-specific platforms.
Spain
Spain generated USD 15.4 million in 2025 and is expected to grow at an 8.6% CAGR from 2026 to 2035. Spain is benefiting from the development of private specialty hospitals and a broader acceptance of referral-based veterinary care. As orthopedic capacity expands beyond teaching-hospital settings, procedural training and distributor support will be increasingly important in converting growing case identification into implant use.
Rest of Europe
Rest of Europe accounted for 27.0% of European revenue in 2025 and is expected to generate USD 108.0 million by 2035. This group combines mature, high-spending markets with countries where specialty veterinary infrastructure is still extending into secondary cities. Market conditions vary materially across the region, creating opportunities for suppliers with adaptable channel strategies, local clinical support, and portfolios suited to different practice maturity levels.
Asia Pacific Veterinary Orthopedic Implants Market Analysis
Asia Pacific generated USD 119.6 million in 2025 and is projected to account for 24.0% of global revenue by 2035. Asia Pacific presents the broadest structural runway for market development as companion-animal ownership, discretionary spending, and specialist-care capacity rise together in major urban centers. Market access depends heavily on distributor quality, local surgeon training, and the ability to establish confidence in clinical outcomes among newly developing referral networks.
China
China generated USD 41.8 million in 2025 and is anticipated to grow at a 13.1% CAGR from 2026 to 2035. China's expansion is supported by urban pet ownership growth and investment in specialist veterinary hospitals. The market remains highly dependent on building trusted clinical and distribution relationships, giving established international brands and capable domestic suppliers room to compete through training, evidence, and service responsiveness.
Japan
Japan accounted for 22.0% of Asia Pacific revenue in 2025 and is projected to generate USD 64.1 million by 2035. Japan is a mature regional market in which demand is shaped more by procedure sophistication and premium care than by first-time access to specialty services. Suppliers that can demonstrate durable clinical performance and provide advanced surgical support are well positioned in this quality-sensitive environment.
India
India generated USD 14.4 million in 2025 and is expected to grow at a 14.8% CAGR from 2026 to 2035. India offers substantial long-term potential as urban companion-animal ownership expands and private investment supports the emergence of referral-grade veterinary facilities. The pace of commercial development will depend on how quickly surgeon training, product availability, and owner willingness to pay develop beyond the largest metropolitan centers.
South Korea
South Korea is projected to account for 10.1% of Asia Pacific revenue by 2035 and is expected to grow at a 12.2% CAGR from 2026 to 2035. South Korea's premium pet-care culture and concentrated urban geography support efficient referral networks and adoption of advanced orthopedic systems. Demand is particularly favorable for suppliers offering differentiated implant technologies, specialized procedural education, and responsive service for high-throughput metropolitan hospitals.
Australia
Australia accounted for 8.0% of Asia Pacific revenue in 2025 and is projected to generate USD 24.9 million by 2035. Australia has an established primary-care and referral ecosystem, with specialist activity concentrated in major cities. This hub-and-spoke structure supports advanced orthopedic care but also increases the importance of service coverage, traveling specialist models, and dependable access to implant inventory for practices outside metropolitan areas.
Rest of Asia Pacific
Rest of Asia Pacific generated USD 15.5 million in 2025 and is projected to account for 11.9% of regional revenue by 2035. This group includes markets where companion-animal ownership is rising quickly but advanced orthopedic capacity remains concentrated in leading cities. Private veterinary-hospital investment and international distribution partnerships are likely to determine how rapidly these markets can convert demand interest into repeatable procedure volume.
Latin America Veterinary Orthopedic Implants Market Analysis
Latin America is projected to generate USD 74.2 million by 2035 and is expected to grow at an 11.3% CAGR from 2026 to 2035. The region's expansion is tied to urban pet ownership, increasing spending on companion-animal health, and the gradual development of specialty practices in large metropolitan areas. Affordability, insurance availability, and import-related pricing remain important constraints, making portfolio accessibility and channel execution critical for suppliers.
Brazil
Brazil generated USD 14.6 million in 2025 and is expected to grow at an 11.5% CAGR from 2026 to 2035. Brazil is an important Latin American market because of its large companion-animal population and increasingly professionalized specialty-care sector. Early adoption by university hospitals and referral groups can help establish clinical reference points that support wider use of advanced fixation and joint-replacement systems.
Mexico
Mexico accounted for 24.8% of Latin American revenue in 2025 and is projected to generate USD 17.8 million by 2035. Mexico's growth is supported by urban demand in major population centers and a growing base of specialty practices. The market's ability to realize this opportunity will depend on continued improvement in affordability, referral capacity, and access to procedure-specific implants through reliable local channels.
Rest of Latin America
Rest of Latin America accounted for 20.3% of regional revenue in 2025 and is expected to grow at an 11.2% CAGR from 2026 to 2035. This group includes more mature specialty-care pockets alongside emerging urban markets where veterinary referral infrastructure remains uneven. Suppliers that tailor channel models to local purchasing capacity and surgeon availability can access demand that is otherwise constrained by fragmented service delivery.
Middle East & Africa
The Middle East & Africa generated USD 19.9 million in 2025 and is expected to grow at an 8.9% CAGR from 2026 to 2035. Demand is centered on higher-income urban markets with growing companion-animal care infrastructure, while much of the broader region remains at an early stage of specialty development. The opportunity favors companies that can support distributors and hospitals with training, inventory planning, and clinically differentiated product systems.
GCC
The GCC generated USD 9.0 million in 2025 and is expected to grow at a 9.4% CAGR from 2026 to 2035. The GCC benefits from premium veterinary hospitals, international clinical talent, and a growing base of companion-animal owners seeking specialized care. Continued investment in veterinary infrastructure and professional development can increase the availability of complex orthopedic procedures across the sub-region.
South Africa
South Africa accounted for 18.1% of Middle East & Africa revenue in 2025 and is projected to generate USD 7.8 million by 2035. South Africa has the region's most established specialist veterinary ecosystem and serves as an important clinical reference market for advanced orthopedic care. Economic constraints nevertheless limit the share of the companion-animal population that can access high-cost procedures, reinforcing the need for differentiated but accessible product strategies.
Rest of MEA
Rest of MEA accounted for 36.7% of regional revenue in 2025 and is expected to grow at an 8.6% CAGR from 2026 to 2035. Demand remains concentrated in major metropolitan centers, where private veterinary practices can serve urban and expatriate pet-owning populations. Broader market development will require expansion of specialist training, distribution infrastructure, and owner access to affordable advanced care.
GMI Analyst View
We see regional performance as primarily determined by the speed at which specialist infrastructure converts companion-animal demand into completed procedures. North America retains an advantage through the depth of its established ecosystem, while Asia Pacific and Latin America offer the more consequential expansion opportunity as referral networks, surgeon capability, and product access mature.
Veterinary Orthopedic Implants Market Share & Competitive Landscape
The top five companies held approximately 55% of the Veterinary Orthopedic Implants market in 2025, indicating moderate concentration in a market where clinical evidence, surgeon education, portfolio depth, and supply reliability shape hospital purchasing decisions. Veterinary Orthopedic Implants market share is therefore influenced less by price alone than by the ability to support a complete procedure pathway, from implant selection through training and postoperative guidance.
Arthrex Vet Systems held an 18% market share in 2025. Its position reflects a broad orthopedic platform spanning fixation and cruciate-repair systems, supported by structured surgeon education and an ability to translate technical capabilities from orthopedic innovation into veterinary workflows. The company's strength lies in supplying integrated systems that support specialist adoption across multiple procedure types.
DePuy Synthes held a 12% market share in 2025. The company benefits from material-science expertise, an established orthopedic heritage, and access to broad distribution capabilities. Its competitive relevance is strongest where hospitals value familiar fixation technologies, dependable supply, and clinical confidence in implant-system performance.
Movora held a 10% market share in 2025. Through brands including BioMedtrix, KYON, and IMEX, the company offers a broad veterinary orthopedic portfolio across arthroplasty, trauma fixation, cruciate procedures, and instruments. Its acquisition-led platform model supports cross-selling and training-led penetration in specialist hospitals across major geographies.
B. Braun Vet Care competes through its surgical instrument heritage, broad manufacturing capabilities, and established relationships with veterinary hospitals. Its ability to combine implants, instruments, and procedural support is especially relevant in accounts seeking standardized operating-room workflows and dependable procurement arrangements.
Orthomed is positioned as a specialist provider of precision-engineered implants and instruments for small-animal orthopedic procedures. In March 2025, Creative Science acquired Orthomed UK Ltd. alongside Infiniti Medical LLC, broadening the commercial platform around Orthomed's implant and education capabilities [7]. The transaction supports the company's potential to strengthen international distribution and channel reach.
AmerisourceBergen Corporation (Cencora, Inc.) participates in veterinary orthopedics through Securos Surgical, combining veterinary-specific implants and instruments with established distribution capability. Its competitive role is shaped by logistical reach and the ability to serve specialty practices through a broader veterinary supply infrastructure.
BlueSAO serves the Asia Pacific market with orthopedic implants and surgical instruments for companion animals. Its positioning reflects growing regional demand for suppliers able to balance procedure-specific product breadth with local channel support.
Fusion Implants focuses on advanced fixation and patient-specific orthopedic solutions for companion animals. Its specialist-manufacturing orientation supports differentiation in complex reconstruction, where custom design capability and close collaboration with referral hospitals can create meaningful clinical value.
GerVetUSA supplies general and orthopedic surgical instruments to veterinary practices and distributors. The company addresses demand for accessible procedural tools and competes through catalog breadth, availability, and cost-conscious purchasing support.
GPC Medical Ltd. manufactures surgical and orthopedic instruments for domestic and export markets, including veterinary applications. Its position in emerging-market channels is supported by cost competitiveness and product availability for practices seeking accessible orthopedic systems.
Integra LifeSciences has strengthened its veterinary orthopedic position through joint-replacement capability. Its acquisition of BioMedtrix expanded its exposure to canine arthroplasty and supports participation in a procedure category where clinical specialization and implant-system integration are central to competitive advantage.
Narang Medical Limited offers orthopedic devices and surgical instruments for veterinary use in domestic and export markets. The company is relevant where demand is shaped by affordability and the need for accessible instrument systems.
Ortho Max provides implant and instrument systems for small-animal orthopedic procedures. Its mid-tier positioning can appeal to practices seeking a balance between product accessibility and procedural capability.
Rita Leibinger is a longstanding specialist in veterinary orthopedic implants, including locking plate systems used in small-animal trauma fixation. Its established technical reputation and clinical validation support relevance among surgeons that prioritize procedure-specific implant design and documented performance.
Veterinary Instrumentation supplies orthopedic implants and surgical instruments with particular relevance to cruciate repair, fracture fixation, and joint procedures. Its specialist orientation and established presence in European veterinary orthopedics support demand among referral hospitals and experienced surgeons.
Recent Industry Developments
BioMedtrix (Movora/Vimian Group) — July 2026: NC State College of Veterinary Medicine announced that BioMedtrix made its uncemented, press-fit total hip replacement implant system available in sizes designed for cats and miniature dogs [5]. The development broadens access to arthroplasty for patient groups that have historically faced limited implant-size availability and may support wider adoption of joint replacement in small companion animals.
Spark Spine and Invictos Orthopedics — February 2026: Spark Spine and Invictos Orthopedics announced a partnership to bring electro-mechanical polymer implant technology to veterinary orthopedic applications, including TPLO procedures and spinal fusion [6]. The collaboration illustrates continued technology transfer from human-device innovation into veterinary orthopedic care, with differentiation centered on biomaterial-enabled healing support.
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.
Frequently Asked Question(FAQ) :
Research methodology, data sources & validation process
This report draws on a structured research process built around direct industry conversations, proprietary modelling, and rigorous cross-validation and not just desk research.
Our 6-step research process
1. Research design & analyst oversight
At GMI, our research methodology is built on a foundation of human expertise, rigorous validation, and complete transparency. Every insight, trend analysis, and forecast in our reports is developed by experienced analysts who understand the nuances of your market.
Our approach integrates extensive primary research through direct engagement with industry participants and experts, complemented by comprehensive secondary research from verified global sources. We apply quantified impact analysis to deliver dependable forecasts, while maintaining complete traceability from original data sources to final insights.
2. Primary research
Primary research forms the backbone of our methodology, contributing nearly 80% to overall insights. It involves direct engagement with industry participants to ensure accuracy and depth in analysis. Our structured interview program covers regional and global markets, with inputs from C-suite executives, directors, and subject matter experts. These interactions provide strategic, operational, and technical perspectives, enabling well-rounded insights and reliable market forecasts.
3. Data mining & market analysis
Data mining is a key part of our research process, contributing nearly 20% to the overall methodology. It involves analysing market structure, identifying industry trends, and assessing macroeconomic factors through revenue share analysis of major players. Relevant data is collected from both paid and unpaid sources to build a reliable database. This information is then integrated to support primary research and market sizing, with validation from key stakeholders such as distributors, manufacturers, and associations.
4. Market sizing
Our market sizing is built on a bottom-up approach, starting with company revenue data gathered directly through primary interviews, alongside production volume figures from manufacturers and installation or deployment statistics. These inputs are then pieced together across regional markets to arrive at a global estimate that stays grounded in actual industry activity.
5. Forecast model & key assumptions
Every forecast includes explicit documentation of:
✓ Key growth drivers and their assumed impact
✓ Restraining factors and mitigation scenarios
✓ Regulatory assumptions and policy change risk
✓ Technology adoption curve parameter
✓ Macroeconomic assumptions (GDP growth, inflation, currency)
✓ Competitive dynamics and market entry/exit expectations
6. Validation & quality assurance
The final stages involve human validation, where domain experts manually review filtered data to identify nuances and contextual errors that automated systems might miss. This expert review adds a critical layer of quality assurance, ensuring data aligns with research objectives and domain-specific standards.
Our triple-layer validation process ensures maximum data reliability:
✓ Statistical Validation
✓ Expert Validation
✓ Market Reality Check
Trust & credibility
Verified data sources
Trade publications
Industry journals, trade publications, and specialized media.
Industry databases
Proprietary and third-party market databases
Regulatory filings
Government procurement records and policy documents
Academic research
University studies and specialist institution reports
Company reports
Annual reports, investor presentations, and filings
Expert interviews
C-suite, procurement leads, and technical specialists
GMI archive
13,000+ published studies across 20+ industry verticals
Trade data
Import/export volumes, HS codes, and customs records
Parameters studied & evaluated
Every data point in this report is validated through primary interviews, true bottom-up modelling, and rigorous cross-checks. Read about our research process →