
Underfloor Heating Actuator Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research approach
1.2 Quality Commitments
1.2.1 GMI AI policy & data integrity commitment
1.2.1.1 Source consistency protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial list of primary sources
1.5 Data mining sources
1.5.1 Paid sources
1.5.1.1 Sources, by region
1.6 Base estimates and calculations
1.6.1 Base year calculation
1.7 Forecast model
1.7.1 Quantified market impact analysis
1.7.1.1 Mathematical impact of growth parameters on forecast
1.8 Research transparency addendum
1.8.1 Source attribution framework
1.8.2 Quality assurance metrics
1.8.3 Our commitment to trust
Chapter 2. Executive Summary
2.1 Industry 360° synopsis
2.2 Key market trends
2.2.1 Product trends
2.2.2 Application trends
2.3 TAM analysis, 2027–2035
2.4 CXO perspectives: strategic imperatives
Chapter 3. Industry Insights
3.1 Industry ecosystem analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost structure
3.1.4 Value addition at each stage
3.1.5 Factors affecting the value chain
3.1.6 Disruptions
3.2 Industry impact forces
3.2.1 Growth drivers
3.2.1.1 EU Energy Performance of Buildings Directive (EPBD) Mandating Efficient Heating Upgrades in New & Retrofit Builds
3.2.1.2 Rapid Growth of Hydronic Underfloor Heating Adoption in Residential New Construction Across Europe & Asia Pacific
3.2.1.3 Rising Consumer Demand for Zone-Level Temperature Control & Associated Energy Cost Savings
3.2.1.4 Accelerating Smart Home & Building Automation System (BMS) Penetration Driving Premium Actuator Demand
3.2.2 Industry pitfalls and challenges
3.2.2.1 High Upfront Installation Cost of Hydronic UFH Systems Relative to Conventional Radiator Alternatives
3.2.2.2 Limited Retrofit Feasibility in Existing Buildings with Concrete Subfloor Construction
3.2.3 Market opportunities
3.2.3.1 Smart & BMS-Connected Actuator Adoption in Commercial & Institutional Buildings
3.2.3.2 EU Renovation Wave Initiative Unlocking Large-Scale Retrofit Demand Across Europe
3.3 Growth potential analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis (2022–2025)
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
3.5 Regulatory landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia-Pacific
3.5.4 Latin America
3.5.5 Middle East and Africa
3.6 Porter's analysis
3.6.1 Bargaining Power of Suppliers
3.6.2 Bargaining Power of Buyers
3.6.3 Threat of New Entrants
3.6.4 Threat of Substitute Products & Systems
3.6.5 Intensity of Competitive Rivalry
3.7 PESTEL analysis
3.7.1 Political Factors
3.7.2 Economic Factors
3.7.3 Social Factors
3.7.4 Technological Factors
3.7.5 Environmental Factors
3.7.6 Legal Factors
3.8 Trade Data Analysis (Based on Paid Database)
3.8.1 Import/Export Volume & Value Trends
3.8.2 Key Trade Corridors & Tariff Impact
3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company market share analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia-Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East and Africa
4.2.2 Market Concentration Analysis
4.3 Competitive analysis of major market players
4.4 Competitive positioning matrix
4.5 Key developments
4.5.1 Mergers & acquisitions
4.5.2 Partnerships & collaborations
4.5.3 New product launches
4.5.4 Expansion plans and funding
4.6 Company tier benchmarking
4.6.1 Tier classification criteria & qualifying thresholds
4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5. Market Estimates & Forecast, By Product, 2022–2035 (USD Million & '000 Units)
5.1 Key trends
5.2 Thermal Actuators
5.3 Motoric Actuators
Chapter 6. Market Estimates & Forecast, By Application, 2022–2035 (USD Million & '000 Units)
6.1 Key trends
6.2 Residential
6.3 Commercial
6.4 Industrial
Chapter 7. Market Estimates & Forecast, By Region, 2022–2035 (USD Million & '000 Units)
7.1 Key trends
7.2 North America
7.2.1 U.S.
7.2.2 Canada
7.3 Europe
7.3.1 Germany
7.3.2 UK
7.3.3 France
7.3.4 Italy
7.3.5 Spain
7.3.6 Netherlands
7.3.7 Sweden
7.3.8 Norway
7.3.9 Denmark
7.3.10 Finland
7.3.11 Austria
7.3.12 Belgium
7.3.13 Switzerland
7.3.14 Czech Republic
7.3.15 Russia
7.4 Asia Pacific
7.4.1 China
7.4.2 Japan
7.4.3 South Korea
7.4.4 Australia
7.4.5 India
7.5 Latin America
7.5.1 Brazil
7.5.2 Mexico
7.6 Middle East & Africa
7.6.1 Saudi Arabia
7.6.2 UAE
7.6.3 South Africa
Chapter 8. Company Profiles (Driven by Primary Research)
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Ankit Gupta. 2026, October. Underfloor Heating Actuator Market (Report ID: GMI4913). Global Market Insights Inc. Retrieved November 13, 2026, from https://www.gminsights.com/toc/details/underfloor-heating-actuator-market

Underfloor Heating Actuator Market
Get a free sample of this report
Underfloor Heating Actuator Market Size
The Underfloor Heating Actuator Market was valued at USD 330 million in 2025, is expected to reach USD 360 million in 2026, and will expand at a CAGR of 7.2% from 2026 to 2035 to attain USD 670 million by 2035. The market covers electrothermal and electromechanical devices fitted to manifold zone valves in hydronic underfloor heating systems, where thermostat or building management system signals regulate water flow and zone temperatures.
The market is moving from a specialist comfort-heating component category toward a more integral element of low-temperature, digitally managed building systems. New construction provides the clearest near-term demand base, while premiumisation is increasing the revenue contribution of motoric, connected, and BMS-compatible products relative to basic replacement actuators.
GMI Analyst View
Based on our engagement with industry contacts, the Underfloor Heating Actuator Market reached an installed volume of approximately 24.5 million units in 2025. We view this installed base as evidence that demand is broadening beyond mature European applications, while the mix of systems being specified increasingly favors higher-control actuator architectures over standalone switching devices.
Underfloor Heating Actuator Market Trends, Growth Drivers & GMI Forecast Outlook
Regulatory pressure on building energy performance, construction investment in premium building stock, and rising requirements for interoperable zone control are reshaping actuator demand. Growth depends not only on underfloor heating adoption, but also on whether specifications favor basic thermal devices or digitally capable motoric products.
Key Drivers
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
The recast EPBD makes heating-system design central to building-performance compliance. Heating, cooling, and hot water account for around 80% of energy used in EU homes, reinforcing the commercial importance of controllable, low-temperature distribution systems in projects seeking lower operational energy demand [1]European Commission. "Energy Performance of Buildings Directive." energy.ec.europa.eu. For actuator suppliers, that shifts the buying conversation from component replacement toward the ability to support responsive room-by-room control, heat-pump-compatible operation, and measurable energy performance.
The policy signal also changes project timing. New EU buildings are required to meet zero-emission performance requirements from 2030, while public buildings face an earlier deadline, encouraging developers and consultants to make system-architecture choices before final compliance dates take effect [2]European Commission. "Nearly-zero energy and zero-emission buildings." energy.ec.europa.eu. This favors products that can be specified early with manifolds, hydronic circuits, and building-control infrastructure rather than sourced solely as aftermarket components.
GCC construction has a different demand profile. The region's opportunity is concentrated in high-value villas, hospitality assets, and commercial developments where hydronic underfloor heating is specified as part of premium comfort and smart-building packages. The installed base remains less mature than Europe's, but project-led demand can support both first-fit sales and a future service opportunity as completed buildings enter operation.
Key Restraints
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
A slow renovation cycle limits how quickly Europe's large installed building stock can become an actuator opportunity. Underfloor heating retrofits commonly depend on a wider intervention involving floors, pipework, heat generation, and controls; actuator demand is therefore tied to the timing and depth of renovation decisions rather than to a simple replacement cycle. Policy support improves the long-run case, but local funding availability, installer capacity, and property-owner willingness determine near-term conversion.
Project economics create a related constraint. In existing homes, wet hydronic underfloor heating can require disruptive construction work, making the value proposition strongest where floors are already being replaced or a heat-pump installation changes the economics of low-temperature heat delivery. This favors integrated renovation packages and constrains broad, discretionary retrofit adoption.
Technical fragmentation also affects supplier economics. Voltage conventions, valve interfaces, and local certification expectations can prevent a single actuator platform from serving every market without modification. Established suppliers with broad portfolios can absorb that complexity more readily, while newer entrants must balance product breadth against inventory and qualification costs.
GMI Analyst View
We see the market's most durable support in the convergence of regulation and product architecture, rather than in a uniform acceleration of retrofit activity. Demand timing will vary by country and project type, but the commercial value of digitally controllable, interoperable zoning is becoming less optional in the applications that set the market's revenue mix.
Underfloor Heating Actuator Market Segment Analysis
By Product Type
Motoric actuators held an 89.6% revenue share in 2025 and are projected to generate USD 610.4 million by 2035. The Underfloor Heating Actuator Market is increasingly organized around motoric products because commercial BMS specifications, remote diagnostics, proportional control, and premium residential smart-home integration all favor digitally capable actuation over basic on-off functionality.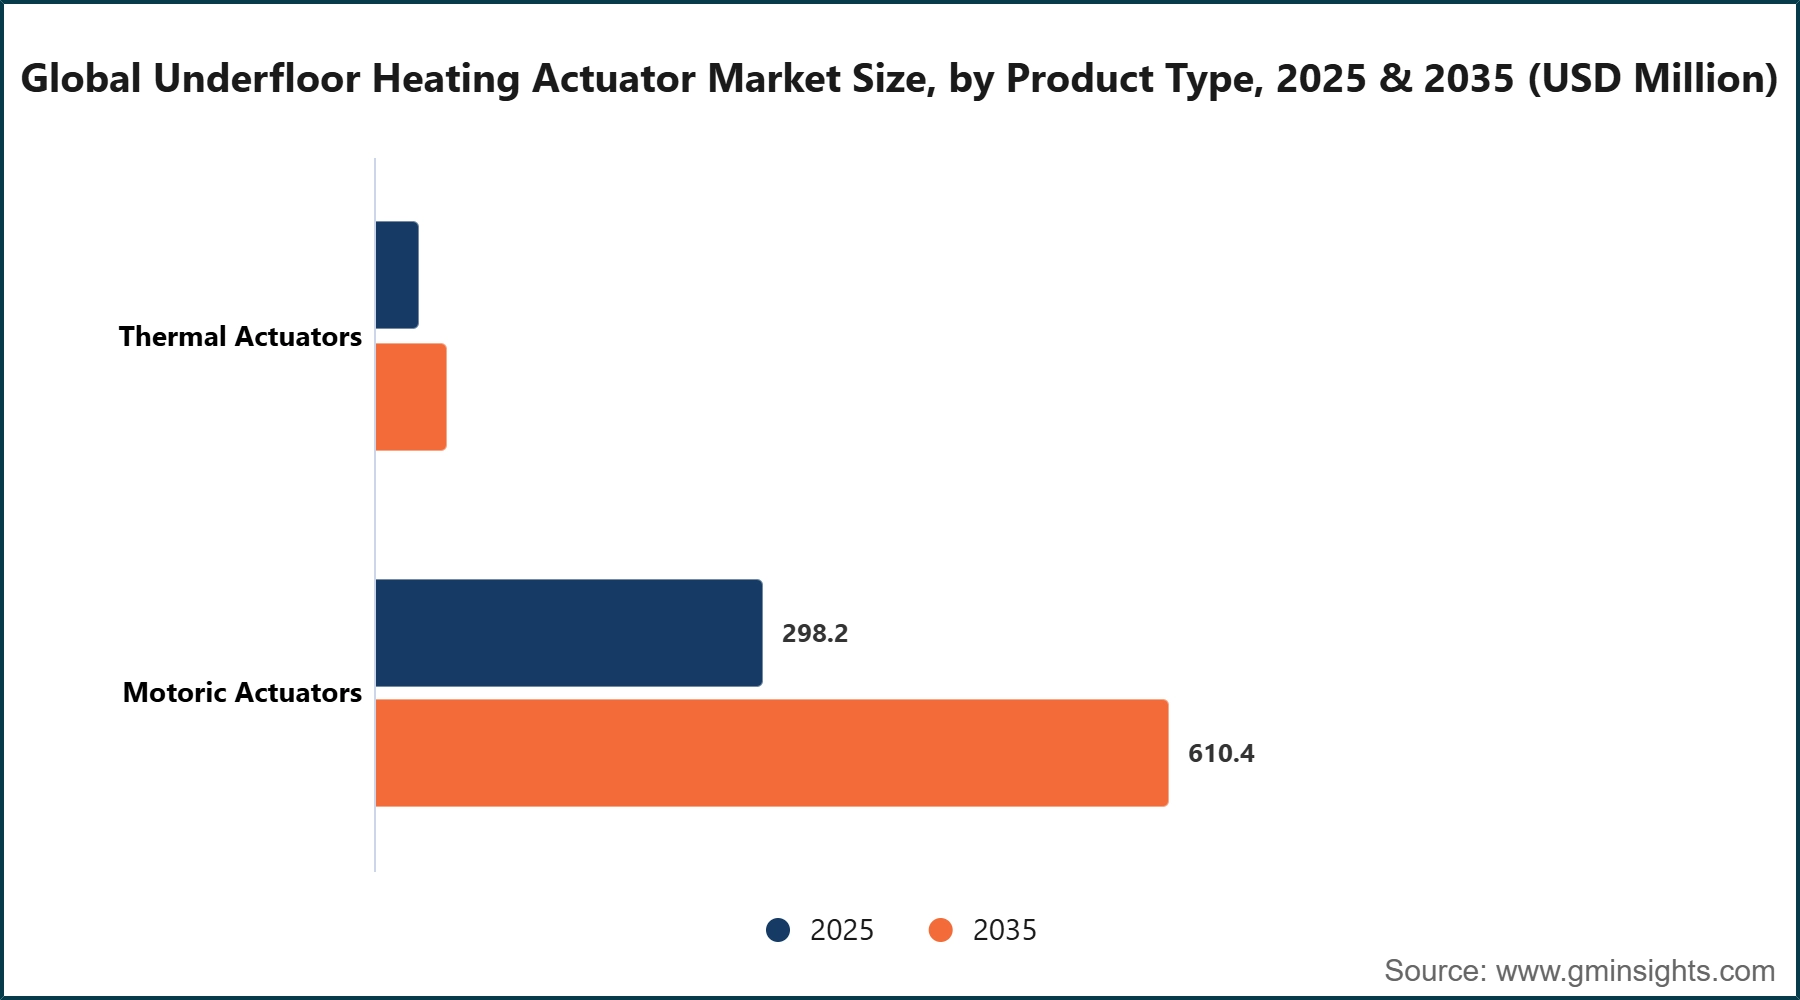 Thermal actuators generated USD 34.6 million in 2025 and are expected to represent 8.5% of market revenue by 2035. Their lower acquisition cost and straightforward commissioning preserve relevance in cost-sensitive residential installations and replacement work, but new-build specifications increasingly prioritize communication capability, finer control, and compatibility with broader building-control ecosystems.
By Application
Residential applications generated USD 190.1 million in 2025 and are expected to account for 54.0% of global revenue by 2035. Demand spans mainstream housing projects using basic manifold zoning and premium developments that specify integrated controls; this creates a bifurcated market in which cost-competitive products coexist with higher-value smart actuator systems.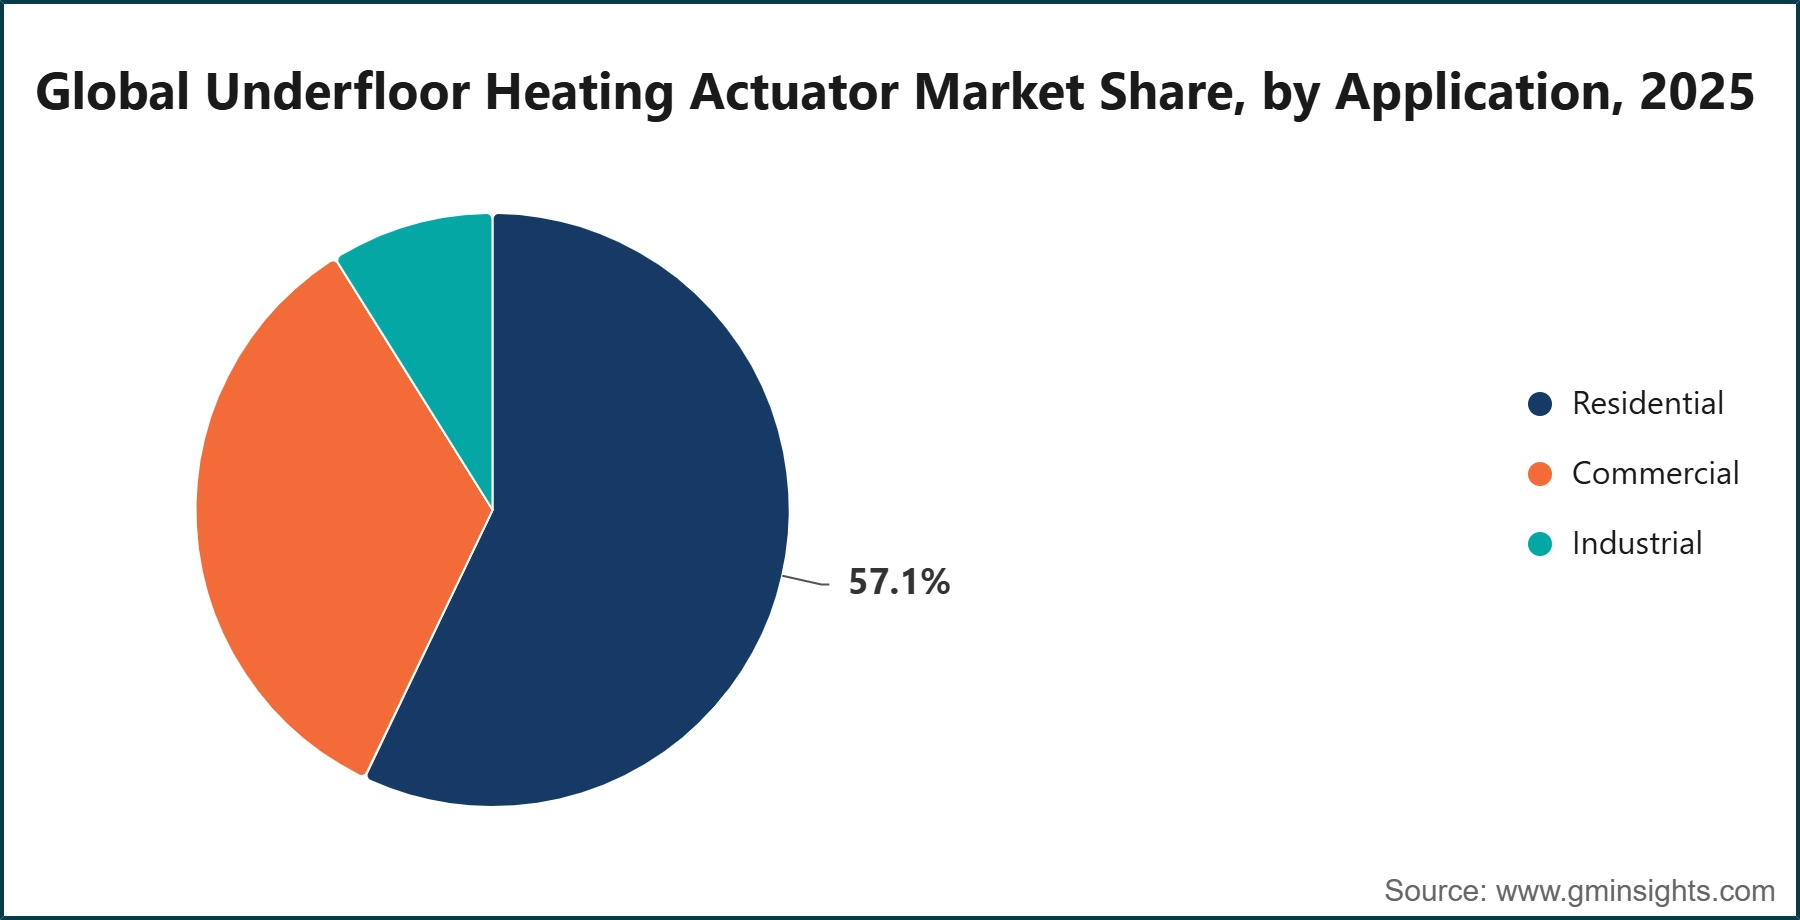
Commercial applications held a 34.0% revenue share in 2025 and are projected to generate USD 253.5 million by 2035. Offices, hospitality properties, institutional buildings, and mixed-use schemes place greater value on BMS compatibility, commissioning efficiency, and documented zone-level performance, making this application especially important to the adoption of motoric and connected actuators.
Industrial applications represented 8.9% of revenue in 2025 and are forecast to generate USD 53.4 million by 2035. Purchasing decisions in warehouses, manufacturing facilities, and process-oriented buildings emphasize robust operation, compatible hydronic controls, and maintenance reliability, with project cycles typically longer than in residential applications.
GMI Analyst View
We believe product differentiation is becoming more application-specific. Residential demand will continue to support both value-oriented and connected products, whereas commercial requirements increasingly reward communication capability and system integration. That divergence gives suppliers a clearer reason to segment portfolios by specification depth rather than compete on unit price alone.
Underfloor Heating Actuator Market Regional Analysis
North America Underfloor Heating Actuator Market Analysis
North America generated USD 29.1 million in 2025 and is expected to represent 7.6% of global revenue by 2035. The underfloor heating actuator market in the region remains concentrated in premium residential construction, select institutional and hospitality projects, and applications where hydronic radiant heating complements heat-pump-oriented building designs.
United States
The United States generated USD 24.0 million in 2025 and is projected to expand at a 6.2% CAGR (2026-2035). Demand is centered on high-value residential projects and commercial installations where architects, mechanical contractors, and developers specify hydronic systems for comfort, energy performance, or premium positioning.
Canada
Canada held 15.8% of North American revenue in 2025 and is forecast to generate USD 5.6 million by 2035. Cold-climate construction in major provincial markets supports demand for radiant heating, although adoption remains linked to specialist installer availability and high-specification residential or commercial projects.
Europe Underfloor Heating Actuator Market Analysis
Europe generated USD 186.8 million in 2025 and is projected to account for 49.8% of global revenue by 2035. The underfloor heating actuator market in Europe benefits from deeply established hydronic underfloor heating infrastructure, mature installer channels, and a policy environment that increases the value of low-temperature, zoned heating control in new construction and renovation.
Germany
Germany generated USD 50.4 million in 2025 and is expected to account for 24.7% of European revenue by 2035. Its scale reflects a mature hydronic heating base, extensive professional distribution networks, and a strong domestic engineering ecosystem that supports both standard thermal actuators and higher-specification motoric products.
Netherlands
The Netherlands held 12.3% of European revenue in 2025 and is forecast to generate USD 35.5 million by 2035. Heat-pump-oriented building design and an active energy-efficiency agenda support the use of low-temperature heating systems, while renovation and new-housing activity create opportunities for integrated manifold and control packages.
Poland
Poland represented 10.1% of European revenue in 2025 and is projected to generate USD 31.4 million by 2035. Large residential development pipelines and a growing preference for higher-control heating systems support demand, while the country's substantial existing housing stock provides a longer-term renovation opportunity.
United Kingdom
The United Kingdom generated USD 19.1 million in 2025 and is expected to expand at a 5.9% CAGR (2026-2035). Demand is supported by new residential projects incorporating hydronic heating, incentive-led heat-pump adoption, and sustainability-focused commercial schemes where zone-level control contributes to building-performance objectives.
France
France held 7.9% of European revenue in 2025 and is forecast to generate USD 26.5 million by 2035. Social-housing upgrades, urban development, and rising attention to energy performance expand the addressable market, although project economics and installation capacity remain important determinants of retrofit conversion.
Sweden
Sweden generated USD 12.6 million in 2025 and is expected to account for 6.3% of European revenue by 2035. Its established radiant-heating culture and preference for energy-optimized residential systems support a comparatively high-value demand mix, with upgrades and premium renovation work sustaining opportunities for connected actuator products.
Asia Pacific Underfloor Heating Actuator Market Analysis
Asia Pacific represented 24.2% of global revenue in 2025 and is projected to generate USD 187.5 million by 2035. The underfloor heating actuator market in Asia Pacific combines China's scale in both manufacturing and end-market demand with differentiated opportunities in mature smart-home markets and emerging premium construction segments.
China
China generated USD 65.7 million in 2025 and is forecast to account for 62.1% of Asia Pacific revenue by 2035. The country is central to global supply at the cost-competitive end of the market while also supporting domestic demand from premium apartment, commercial, and hospitality construction, giving local manufacturers influence over pricing and product availability.
Japan
Japan held 9.1% of Asia Pacific revenue in 2025 and is projected to generate USD 11.5 million by 2035. The market favors technically sophisticated residential and commercial applications, where smart-home integration and building upgrades can support demand for higher-specification controls.
South Korea
South Korea generated USD 3.3 million in 2025 and is expected to expand at an 8.7% CAGR (2026-2035). The country's established preference for heated floors and strong digital-home culture support the transition from traditional heating approaches toward modern hydronic systems with smart control capability.
India
India represented 1.5% of Asia Pacific revenue in 2025 and is projected to generate USD 7.1 million by 2035. Demand is selective rather than broad-based, concentrated in premium cold-climate housing, high-altitude hospitality, and climate-controlled commercial projects where radiant systems offer a differentiated comfort proposition.
Latin America Underfloor Heating Actuator Market Analysis
Latin America generated USD 17.0 million in 2025 and is forecast to generate USD 33.9 million by 2035. The underfloor heating actuator market in the region is concentrated in premium real estate, hospitality, and colder-climate applications, with demand shaped more by construction cycles and developer confidence than by broad regulatory mandates.
Brazil
Brazil generated USD 10.3 million in 2025 and is expected to account for 64.9% of Latin American revenue by 2035. Demand is concentrated in major urban and southern markets, where luxury residential and hospitality development supports specification of hydronic underfloor heating systems.
Argentina
Argentina held 21.2% of Latin American revenue in 2025 and is forecast to generate USD 5.2 million by 2035. Premium housing in Buenos Aires and colder southern markets remains the principal source of demand, although construction activity is sensitive to broader macroeconomic conditions.
Middle East & Africa (MEA) Underfloor Heating Actuator Market Analysis
MEA generated USD 19.3 million in 2025 and is projected to expand at a 13.0% CAGR (2026-2035). The underfloor heating actuator market in MEA is driven by premium construction, especially in GCC residential, hospitality, and commercial developments where hydronic systems are increasingly incorporated into high-specification building designs.
GCC
The GCC generated USD 15.2 million in 2025 and is forecast to generate USD 49.7 million by 2035. Large development programs in Saudi Arabia and the UAE create a material opportunity for European branded suppliers and Chinese OEMs, with product selection varying by project specification, procurement approach, and required system integration.
South Africa
South Africa held 4.7% of MEA revenue in 2025 and is projected to generate USD 2.8 million by 2035. Demand is concentrated in premium residential construction in colder local markets, where underfloor heating addresses a clear comfort requirement but remains exposed to commercial construction conditions and infrastructure constraints.
GMI Analyst View
We interpret regional diversification as a strategic opportunity and an operating challenge. Europe remains the market's specification center, while MEA and Asia Pacific introduce different project economics, channels, and product preferences. Suppliers that can combine broad compatibility with localized distribution and technical support will be better positioned than those relying on a single regional product playbook.
Underfloor Heating Actuator Market Share & Competitive Landscape
The Underfloor Heating Actuator Market share is moderately concentrated, with the five largest participants including Chinese OEM Cluster, Möhlenhoff, Danfoss, Uponor, and Oventrop collectively holding approximately 43% of global revenue in 2025. Competition combines scale-driven Chinese OEM production with European brands that compete through system integration, professional installer relationships, qualification depth, and compatibility with higher-specification hydronic and building-control installations.
The Chinese OEM Cluster held a 22% market share in 2025. Its position reflects domestic manufacturing scale, competitive export pricing, and growing ability to address both thermal and motoric actuator demand. The cluster's principal strategic challenge is moving beyond basic price and delivery competition while meeting the certification, interoperability, and channel-support expectations of higher-value European and international projects.
Möhlenhoff held a 7% market share in 2025. The company's position is supported by its specialist focus on underfloor heating actuators and manifold systems, product coverage across common voltage and operating configurations, and long-standing access to professional installation channels in Germany and wider Europe.
Danfoss held a 5% market share in 2025. Its competitive position is strengthened by the ability to connect actuator offerings with wider residential controls and commercial building-automation systems, allowing it to compete where system integration, commissioning simplicity, and diagnostics carry more weight than component price alone.
Uponor, now part of GF Building Flow Solutions, and Oventrop retain relevance through integrated piping, manifold, valve, and heating-system propositions. Their ability to bundle actuators into broader hydronic specifications gives them channel advantages where installers and developers prioritize system compatibility and accountability for overall performance.
Honeywell International, Siemens, Schneider Electric, Johnson Controls, Emerson Electric, and Sauter are most relevant in commercial and institutional applications where zone control is part of a wider building-management scope. Giacomini, Rehau, Watts Water Technologies, Eberle Controls, Heatmiser, Intatec, Polypipe, Warmup, and Hunt Heating compete through varying combinations of manifold systems, controls, installer access, and regional distribution.
Belimo is not a participant in the underfloor heating actuator market as defined here. Its actuator portfolio is focused on HVAC damper and airflow-control applications, which are outside the scope of manifold zone-valve actuators used in hydronic underfloor heating systems.
Recent Industry Developments
In September 2025, eQ-3 announced the Homematic IP Floor Heating Controller — 8 channels, motorised, for water-based surface heating systems. The product uses motorised valve drives and supports automatic hydraulic balancing and smart-home integration, illustrating continued product development around digitally managed residential heating control [5]eQ-3 / Homematic IP. "New Floor Heating Controller - 8 channels, motorised." homematic-ip.com.
In February 2026, SASWELL launched HVAC terminal actuators for fan-coil and underfloor heating applications. The products incorporate stepper-motor modulation, app-based configuration, and a universal manifold-valve interface, signaling continued Chinese OEM investment in smart and modulating actuator configurations [6]SASWELL. "2026 New HVAC Actuators | Modulating, Fail-Safe & Smart UFH." saswell.com.
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.