
Insulation Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research approach
1.2 Quality Commitments
1.2.1 GMI AI policy & data integrity commitment
1.2.1.1 Source consistency protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial list of primary sources
1.5 Data mining sources
1.5.1 Paid sources
1.5.1.1 Sources, by region
1.6 Base estimates and calculations
1.6.1 Base year calculation
1.7 Forecast model
1.7.1 Quantified market impact analysis
1.7.1.1 Mathematical impact of growth parameters on forecast
1.8 Research transparency addendum
1.8.1 Source attribution framework
1.8.2 Quality assurance metrics
1.8.3 Our commitment to trust
Chapter 2. Executive Summary
2.1 Industry 360° synopsis
2.2 Key market trends
2.2.1 Material type trends
2.2.2 Insulation function trends
2.2.3 Product Form trends
2.2.4 End use industry trends
2.2.5 Regional trends
Chapter 3. Industry Insights
3.1 Industry ecosystem analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost structure
3.1.4 Value addition at each stage
3.1.5 Factor affecting the value chain
3.1.6 Disruptions
3.2 Industry impact forces
3.2.1 Growth drivers
3.2.1.1 Stringent Energy Efficiency Regulations & Building Codes (EU EPBD, US IECC, China GB Standards)
3.2.1.2 Rising Residential & Commercial Construction Activity in Emerging Economies
3.2.1.3 Accelerating Green Building Certification Adoption (LEED, BREEAM, EDGE)
3.2.1.4 Large-Scale Building Retrofitting Programs in Mature Markets
3.2.2 Industry pitfalls and challenges
3.2.2.1 Volatility in Petrochemical-Derived Raw Material Costs (Crude Oil Dependency)
3.2.2.2 Health & Environmental Concerns — Toxic Chemicals & VOC Emissions
3.2.2.3 Declining Coal-Based Power Plant Pipelines Reducing Industrial Demand
3.2.3 Market opportunities
3.3 Growth potential analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
3.5 Regulatory landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia-Pacific
3.5.4 Latin America
3.5.5 Middle East and Africa
3.6 Porter’s analysis
3.7 PESTEL analysis
3.8 Trade Data Analysis (Driven by Primary Research & Paid Database sources)
3.8.1 Import/Export Volume & Value Trends by Product Category (HS Code 7210, 7212, 7225)
3.8.2 Key Trade Corridors & Tariff Impact on Cross-Border Decking Supply Flows
3.8.3 Anti-Dumping & Countervailing Duty Cases Affecting Trade Flows
3.9 Technology & Innovation Landscape
3.9.1 Aerogel & Nano-insulation Technologies
3.9.2 Vacuum Insulation Panels (VIPs)
3.9.3 Phase-Change Material (PCM) Integration
3.9.4 Bio-based & Mycelium-based Insulation Innovations
3.10 Impact of AI & Generative AI on the Market
3.10.1 AI-Driven Disruption of Existing Business Models
3.10.2 GenAI Use Cases & Adoption Roadmap by Segment
3.10.3 Risks, Limitations & Regulatory Considerations
3.11 Capacity & Production Landscape (Driven by Primary Research)
3.11.1 Installed Manufacturing Capacity by Region & Key Producer
3.11.2 Capacity Utilisation Rates & Expansion Pipelines (Greenfield & Brownfield Projects)
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company market share analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia-Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East and Africa
4.2.2 Market Concentration Analysis
4.3 Competitive analysis of major market players
4.4 Competitive positioning matrix
4.5 Key developments
4.5.1 Mergers & acquisitions
4.5.2 Partnerships & collaborations
4.5.3 New product launches
4.5.4 Expansion plans and funding
4.6 Company tier benchmarking
4.6.1 Tier classification criteria & qualifying thresholds
4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5. Market Estimates and Forecast, By Material Type, 2022 – 2035 ($ Million, Million Square Meters)
5.1 Key trends
5.2 Glass Wool
5.2.1 Blown/Loose-fill Form
5.2.2 Blanket & Batt Form
5.3 Stone Wool / Rock Wool
5.3.1 Blanket & Batt Form
5.3.2 Rigid Board Form
5.4 Expanded Polystyrene (EPS)
5.4.1 Standard EPS Board
5.4.2 Graphite-Enhanced EPS (Grey EPS / Neopor)
5.5 Extruded Polystyrene (XPS)
5.5.1 Polyurethane (PUR) / Polyisocyanurate (PIR) Foam
5.5.2 Spray-Applied PUR Foam
5.5.3 PIR Rigid Board / Sandwich Panels
5.6 Phenolic Foam
5.7 Aerogel
5.7.1 Blanket/Mat Form
5.7.2 Granular/Loose Form
5.7.3 Cellulose
5.7.4 Calcium Silicate
5.7.5 CMS / Ceramic & Refractory Fibers
5.8 Others
Chapter 6. Market Estimates and Forecast, By Insulation Function, 2022 – 2035 ($ Million, Million Square Meters)
6.1 Key trends
6.2 Thermal Insulation
6.3 Acoustic Insulation
6.4 Electrical Insulation
Chapter 7. Market Estimates and Forecast, By Product Form, 2022 – 2035 ($ Million, Million Square Meters)
7.1 Key trends
7.2 Blanket (Rolls & Batts)
7.3 Rigid Board / Panel
7.4 Loose-fill & Blown-in
7.5 Spray Foam
7.6 Pre-formed / Tubular Sections
Chapter 8. Market Estimates and Forecast, By End Use Industry, 2022 – 2035 ($ Million, Million Square Meters)
8.1 Key trends
8.2 Building & Construction
8.2.1 Residential
8.2.1.1 Single-Family Housing
8.2.1.2 Multi-Family / Apartment
8.2.2 Non-Residential
8.2.2.1 Commercial (Office, Retail, Hospitality)
8.2.2.2 Institutional (Healthcare, Education, Government)
8.2.2.3 Industrial Buildings & Warehouses
8.3 Industrial & Plant Equipment
8.3.1 Oil & Gas / Petrochemical Processing
8.3.2 Power Generation (Thermal, Nuclear)
8.3.3 Chemical & Pharmaceutical Processing
8.3.4 LNG & Cryogenic Storage
8.4 HVAC & OEM
8.4.1 Commercial HVAC Equipment Manufacturing
8.4.2 Refrigeration OEM Systems
8.5 Transportation
8.5.1 Automotive (EV Battery Thermal Management & Cabin)
8.5.2 Rail & Marine
8.5.3 Aerospace & Defense
8.6 Appliances
8.6.1 Refrigerators & Freezers
8.6.2 Water Heaters & Boilers
8.6.3 Industrial Ovens & Furnaces
8.7 Others
Chapter 9. Market Estimates and Forecast, By Region, 2022 – 2035 ($ Million, Million Square Meters)
9.1 Key trends
9.2 North America
9.2.1 US
9.2.2 Canada
9.3 Europe
9.3.1 Germany
9.3.2 UK
9.3.3 France
9.3.4 Italy
9.3.5 Spain
9.3.6 Netherlands
9.3.7 Rest of Europe
9.4 Asia Pacific
9.4.1 China
9.4.2 India
9.4.3 Japan
9.4.4 Australia
9.4.5 South Korea
9.4.6 Rest of Asia-Pacific
9.5 Latin America
9.5.1 Brazil
9.5.2 Mexico
9.5.3 Argentina
9.5.4 Rest of Latin America
9.6 Middle East and Africa
9.6.1 South Africa
9.6.2 Saudi Arabia
9.6.3 UAE
9.6.4 Rest of Middle East and Africa
Chapter 10. Company Profiles
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Avinash Singh. 2026, September. Insulation Market Size - By Product (Fiberglass/Glass Wool, Mineral Wool, Plastic foam, Others), By Application (Residential Construction, Industrial, HVAC & OEM, Non-residential Construction) & Global Forecast, 2022 - 2030 (Report ID: GMI2579). Global Market Insights Inc. Retrieved November 13, 2026, from https://www.gminsights.com/toc/details/insulation-market

Insulation Market
Get a free sample of this report
Insulation Market Size
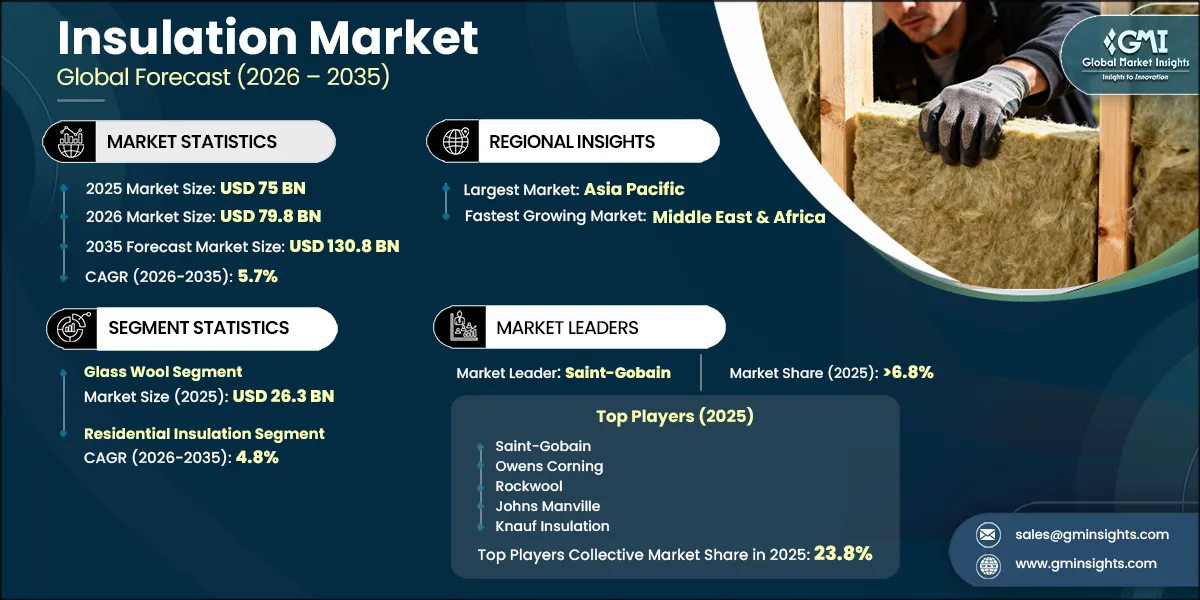
The global insulation market was valued at USD 75 billion in 2025 and is expected to reach USD 79.8 billion in 2026, advancing at a 5.7% CAGR from 2026 to 2035 to reach USD 130.8 billion by 2035.
The Global Insulation Market is being reshaped by stricter building-energy requirements, expanding retrofit obligations, and a growing preference for materials that combine thermal efficiency with fire, acoustic, moisture, and embodied-carbon performance. Demand is increasingly differentiated between high-volume building applications and specification-led technical uses in industrial facilities and HVAC systems.
GMI Analyst View
Based on our discussions with procurement managers and insulation manufacturers, the global insulation market registered USD 69.0 billion in 2023, reflecting a demand trough created by construction-cycle weakness, inventory correction, and supply-chain destocking. We view the subsequent recovery as more durable because renovation mandates, code enforcement, and performance-based procurement are broadening the market's structural demand base.
This report covers the Global Insulation Market across the historic period of 2022–2025, with 2025 as the base year and 2026–2035 as the forecast period. Revenue is assessed on a demand-side, USD revenue-only basis across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. The analysis covers product types including glass wool, mineral wool, EPS/XPS, PU/PIR foam, aerogel, and other insulation materials, as well as residential, commercial, industrial, and HVAC & equipment applications. Installation services, standalone accessories, non-insulation fire-protection coatings, and electrical wiring insulation are excluded.
Insulation Market Trends, Growth Drivers & GMI Forecast Outlook
Regulatory enforcement is moving insulation procurement beyond voluntary efficiency upgrades, while the commercial case for deeper retrofits remains uneven across property owners and markets. Product demand is therefore expected to be strongest where compliance, energy-management requirements, and construction activity converge with established installation capacity.
Key Drivers
The revised Energy Performance of Buildings Directive turns building-envelope improvement into a compliance-led procurement cycle for European non-residential owners. Its effect reaches beyond product volume: façade, roof, floor, and cavity-wall systems must increasingly be selected for documented in-use performance, which favors suppliers able to provide tested assemblies, technical documentation, and installer support. The large stock of older, inefficient buildings expands the addressable renovation pipeline even where immediate project conversion remains constrained. [1]
Efficiency investment is also widening demand beyond code-driven building activity. Building-envelope upgrades, industrial process optimization, and HVAC thermal-management projects all create insulation requirements that are tied to operating-cost reduction rather than solely to new construction. This provides an important counterweight to cyclical housing starts and supports demand for both conventional materials and higher-performance technical products. [2]
Green-building frameworks are changing how developers evaluate insulation. Whole-lifecycle carbon assessment and performance-oriented certification criteria increase the value of products with verified environmental documentation, low-carbon manufacturing pathways, and strong thermal outcomes in constrained assemblies. This favors technical differentiation in premium commercial and institutional projects. [3]
Key Restraints
The central constraint in Europe is not the absence of policy ambition but the rate at which owners, contractors, lenders, and local authorities can turn policy into completed renovation work. Residential retrofit economics remain especially exposed to fragmented incentives, project complexity, and shortages of skilled labor. As a result, demand may build unevenly across national markets rather than follow a uniform regulatory schedule. [1]
Construction-cost inflation has amplified this execution risk by raising the cost of complementary work that often accompanies envelope upgrades, including access, structural remediation, and mechanical-system changes. The resulting payback pressure can favor lower-cost interventions and defer deeper renovation packages, limiting near-term conversion in price-sensitive property segments. [2]
Foam manufacturers face a separate adjustment challenge as reformulation, production-line adaptation, certification, and specification approval must proceed in parallel. Larger integrated producers are generally better positioned to manage this transition, while smaller suppliers may face temporary cost and qualification disadvantages in regulated product categories.
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
GMI Analyst View
We see two demand rhythms shaping the market: compliance-led renovation and performance-led new construction. The former has a large installed-base opportunity but a slower conversion cycle, while the latter responds more directly to project pipelines, industrial investment, and code adoption. This split should preserve market resilience while making regional and application outcomes increasingly uneven.
Insulation Market Segment Analysis
By Product Type
Glass wool generated USD 26.3 billion in 2025, and its market share is projected to reach 31.7% by 2035. The Global Insulation Market continues to rely on glass wool as a cost-effective, broadly available material for residential and light-commercial construction. Its installed-base advantage rests on contractor familiarity, adaptable formats, and a strong performance-to-cost balance, although premium materials are gaining specification share in space-constrained and technically demanding projects.
Mineral wool held a 25.1% market share in 2025 and is projected to reach USD 35.3 billion by 2035. Mineral wool is benefiting from demand for noncombustible, acoustically effective, and durable envelope systems. Its position is especially strong in commercial façades, fire-rated assemblies, industrial equipment, and projects where design teams seek to combine thermal performance with safety and lifecycle considerations.
EPS/XPS generated USD 14.6 billion in 2025, and its market share is projected to reach 17.6% by 2035. EPS/XPS remains important in moisture-exposed applications, including foundations, floors, external walls, and cold-storage structures. However, product reformulation needs and competitive pressure from other high-performance rigid boards are shifting development priorities toward lower-impact chemistries and more application-specific product designs.
PU/PIR foam is projected to reach USD 18.5 billion by 2035 and is expected to record a CAGR of 6.1% (2026–2035). PU/PIR foam benefits where thermal performance per unit thickness is commercially decisive. Thin-profile roof, floor, modular-building, and high-efficiency envelope systems support its adoption, though qualification timelines and blowing-agent transition requirements can affect the pace at which newer formulations enter specified projects.
Aerogel generated USD 2.5 billion in 2025 and is expected to record a CAGR of 9.8% (2026–2035). Aerogel occupies a high-value niche in industrial, cryogenic, energy, and space-constrained building applications. Its commercial opportunity depends on the ability to translate exceptional thermal performance into lower installed-system cost, particularly where insulation thickness, heat loss, or process reliability create material economic consequences.
Other insulation materials are projected to reach USD 5.5 billion by 2035 and held a 3.7% market share in 2025. Cellulose, natural fiber, cork, hemp, and other specialty materials are gaining relevance as building owners and designers place greater weight on biobased content, circularity, and embodied-carbon disclosures. Their expansion is most credible in specification-led sustainable construction rather than as a universal replacement for established mineral and foam products.
By Application
Residential insulation generated USD 33.8 billion in 2025 and is expected to record a CAGR of 4.8% (2026–2035). Residential demand is anchored in new housing construction, attic and wall upgrades, and the large stock of inefficient homes in mature economies. Yet it also faces the highest sensitivity to financing conditions, homeowner payback expectations, and installer availability, making renovation-led growth less immediate than policy ambition alone might indicate.
Commercial insulation held a 28.0% market share in 2025 and is projected to reach USD 35.5 billion by 2035. Commercial projects increasingly require insulation systems that address energy performance, fire safety, acoustics, façade integrity, and sustainability documentation simultaneously. Higher specification intensity supports demand for advanced mineral wool, rigid foam, and integrated envelope systems in offices, hospitality, retail, institutions, and data-intensive facilities.
Industrial insulation held a 16.0% market share in 2025 and is projected to reach USD 23.5 billion by 2035. Industrial demand is comparatively insulated from residential construction cycles because it is tied to process efficiency, asset maintenance, temperature control, safety, and plant reliability. Energy, petrochemical, LNG, power, and chemical facilities therefore create recurring opportunities for technical insulation suppliers with application-engineering capability.
HVAC & Equipment insulation is projected to reach USD 17.3 billion by 2035 and is expected to record a CAGR of 7.7% (2026–2035). HVAC and equipment insulation is gaining momentum as cooling infrastructure expands, heat-pump adoption advances, and mechanical systems become more integrated with building-energy management. The segment rewards suppliers that can meet condensation-control, acoustic, fire, durability, and installation-efficiency requirements across ducts, pipes, equipment housings, and refrigeration systems.
GMI Analyst View
We believe the market is steadily shifting toward performance intensity rather than simply material volume. Demand is becoming more valuable where thermal constraints, fire requirements, lifecycle documentation, and system integration limit substitution. This favors suppliers that can combine material science with technical service and specification influence.
Insulation Market Regional Analysis
North America Insulation Market Analysis
North America generated USD 18.0 billion in 2025, and its market share is projected to reach 22.0% by 2035. North American demand is supported by established building-code frameworks, residential renovation activity, and industrial investment. The region's mature insulation penetration limits volume expansion relative to emerging markets, but code updates, high-performance construction, LNG-related activity, and demand for technical insulation preserve a substantial value opportunity.
U.S.
The U.S. anchors regional demand through a combination of residential energy codes, localized stretch-code adoption, commercial building activity, and industrial project investment. Demand is particularly responsive to product availability, contractor channels, and the ability of suppliers to serve both mass-market housing and technical commercial applications.
Europe Insulation Market Analysis
Europe held a 29.1% market share in 2025 and is projected to reach USD 35.6 billion by 2035. Europe remains the most regulation-intensive insulation market, with energy-performance obligations creating a durable basis for commercial, public-sector, and industrial renovation demand. The main uncertainty is execution: financing structures, local contractor capacity, and national implementation will determine how quickly the regulatory pipeline converts into installed product volume.
Germany
Germany is a pivotal European market because deep-retrofit financing and established contractor networks provide a more developed route from energy policy to installation activity. Its importance extends beyond volume, as product specifications established in Germany can influence material preferences across adjacent European markets.
Asia Pacific Insulation Market Analysis
Asia Pacific generated USD 29.1 billion in 2025 and is expected to record a CAGR of 6.5% (2026–2035). Asia Pacific is supported by urban construction, industrial development, rising cooling loads, and the gradual extension of building-energy-code coverage. The region combines mature markets with high technical standards and rapidly developing markets where insulation penetration is still expanding, producing a broad demand base across conventional and premium products.
China
China is central to regional insulation demand through the scale of urban construction, increasingly stringent building-performance standards, and the expansion of green-building practices. The market offers a substantial opportunity for suppliers that can align product performance, local production, and project-specification support.
Latin America Insulation Market Analysis
Latin America held a 5.1% market share in 2025 and is projected to reach USD 7.0 billion by 2035. Latin American growth is being driven primarily by commercial construction, industrial activity, operating-cost concerns, and the gradual expansion of green-building practices. Demand remains constrained by macroeconomic volatility and less consistent residential-code enforcement, which keeps the market more project-led than regulation-led.
Brazil
Brazil provides the region's broadest insulation opportunity across commercial real estate, industrial facilities, and high-value urban construction. Its demand profile favors suppliers able to serve both building-envelope applications and technical insulation requirements in process-intensive industries.
Middle East & Africa Insulation Market Analysis
Middle East & Africa held a 3.1% market share in 2025 and is expected to record a CAGR of 7.2% (2026–2035). Middle East & Africa combines infrastructure-led construction with extreme-climate thermal requirements and growing attention to green-building performance. Demand is strongest where large projects, industrial investment, and emerging efficiency standards create an economic rationale for higher-performance insulation systems.
UAE
The UAE is a specification-led regional market where green-building requirements, cooling demand, and high-value construction support procurement of thermal-performance products. Its influence is amplified by its role as a reference market for developers, consultants, and suppliers operating across the Gulf.
GMI Analyst View
We expect Asia Pacific and Middle East & Africa to become increasingly important to the market's marginal growth profile because construction volume, cooling needs, and code formation are expanding simultaneously. Europe retains the deepest renovation opportunity, but its near-term outcome depends more heavily on execution capacity than on the underlying need for insulation.
Insulation Market Share & Competitive Landscape
The Global Insulation Market share structure remains fragmented, with the top five players collectively holding approximately 23.8% of global market revenue in 2025. Competition differs sharply by product category: scale, logistics, and channel coverage matter in glass and mineral wool, while formulation capability, qualification expertise, and technical support are more decisive in foam, aerogel, and elastomeric applications.
Saint-Gobain held a 6.8% market share in 2025. Saint-Gobain's insulation position is reinforced by its broader building-solutions portfolio, which enables system-level engagement with commercial and industrial customers. Its ability to connect insulation with façade, interior, and building-envelope offerings strengthens its relevance in projects where procurement favors coordinated technical solutions.
Owens Corning held a 5.4% market share in 2025. Owens Corning combines a strong North American consumer and contractor presence with a broad insulation portfolio spanning glass wool, XPS, and spray foam. Its strategic focus on building products concentrates investment and channel capability in end markets where code enforcement and energy-performance expectations are becoming more demanding.
Rockwool International held a 4.7% market share in 2025. Rockwool's differentiation rests on stone wool's fire performance, acoustics, and compatibility with sustainability-oriented commercial specifications. Manufacturing expansion and lower-carbon production technologies may become increasingly relevant as embodied-carbon criteria enter more procurement and design decisions.
Johns Manville is well positioned in commercial roofing, industrial insulation, and North American distribution channels, where project execution and contractor relationships materially affect supplier selection. Its strength lies in serving technically specified applications rather than competing solely on commodity material pricing.
Knauf Insulation's presence across Europe, North America, and Asia Pacific gives it exposure to both mature renovation markets and developing construction economies. Its investment in lower-carbon mineral wool production aligns with the growing role of lifecycle assessments in building-material specification.
Kingspan focuses on premium insulated panels, high-performance boards, and specialty insulation categories where specification barriers are higher than in commodity products. Its portfolio strategy reflects a market shift toward engineered envelope systems and materials that can meet demanding thermal requirements within limited assembly thickness.
Armacell maintains a distinct position in flexible elastomeric foam for HVAC and technical insulation. Its exposure to mechanical systems, refrigeration, and equipment insulation provides access to application areas where condensation control, installation practicality, and long-term system efficiency are critical.
BASF participates across EPS and polyurethane value chains, combining material science with downstream insulation relevance. Its role in lower-impact foam chemistry is particularly important as producers adapt to evolving blowing-agent and environmental requirements.
Regional players, including URSA Insulation, Recticel, Huamei Energy-Saving Technology Group, NMC, Soprema, Arabian Fiberglass Insulation, Fletcher Insulation, and Isoboard, compete through regional manufacturing, application specialization, and channel access. Emerging companies such as Aspen Aerogels, Steico, va-Q-tec Thermal Solutions, Isohemp, and Amorim Cork Composites are expanding the specialty-material landscape by addressing high-performance, biobased, and space-constrained applications.
Recent Industry Developments
ROCKWOOL began construction on a new stone wool manufacturing facility in Wallula, Washington, using electric melting technology to expand its western U.S. production footprint and support commercial, industrial, and fire-safety demand. [4]
Knauf Group commissioned a low-carbon rock mineral wool production line in Croatia, reinforcing the competitive importance of manufacturing emissions, recycled inputs, and lifecycle performance in European mineral wool specifications. [5]
Owens Corning completed the sale of its glass reinforcements business to concentrate its capital allocation and operating focus on residential and commercial building products. [6]
TopBuild completed the acquisition of Specialty Products and Insulation, expanding its mechanical-insulation distribution and fabrication capabilities across North American commercial and industrial end markets. [7]
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.