
Range Hood Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research Approach
1.2 Quality Commitments
1.2.1 GMI AI Policy & Data Integrity Commitment
1.2.1.1 Source Consistency Protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial List of Primary Sources
1.5 Data Mining Sources
1.5.1 Paid Sources
1.5.1.1 Sources, by Region
1.6 Base Estimates & Calculations
1.6.1 Base Year Calculation
1.7 Forecast Model
1.7.1 Quantified Market Impact Analysis
1.7.1.1 Mathematical Impact of Growth Parameters on Forecast
1.8 Research Transparency Addendum
1.8.1 Source Attribution Framework
1.8.2 Quality Assurance Metrics
1.8.3 Our Commitment to Trust
Chapter 2. Executive Summary
2.1 Industry 360° Synopsis
2.2 Key Market Trends
2.2.1 Product Type Trends
2.2.2 Ventilation System Trends
2.2.3 Application Trends
2.2.4 Distribution Channel Trends
2.2.5 Width Trends
2.2.6 Price Range Trends
2.3 TAM Analysis, 2027–2035
2.4 CXO Perspectives: Strategic Imperatives
Chapter 3. Industry Insights
3.1 Industry Ecosystem Analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin Analysis
3.1.3 Cost Structure
3.1.4 Value Addition at Each Stage
3.1.5 Factors Affecting the Value Chain
3.1.6 Disruptions
3.2 Industry Impact Forces
3.2.1 Growth Drivers
3.2.1.1 Rising Residential Construction & Kitchen Renovation Spending
3.2.1.2 Growing Consumer Awareness of Indoor Air Quality & Cooking-Related Pollutants
3.2.1.3 Increasing Adoption of Open-Concept & Modular Kitchen Designs
3.2.1.4 Government Incentives & Energy Efficiency Mandates (Energy Star, ASHRAE 62.2, Inflation Reduction Act)
3.2.1.5 Smart Home Integration Driving Demand for IoT-Enabled Range Hoods
3.2.2 Industry Pitfalls & Challenges
3.2.2.1 High Installation Cost & Complexity of Ducted Ventilation Systems
3.2.2.2 Consumer Sensitivity to Noise Levels Limiting High-CFM Adoption
3.2.2.3 Recurring Maintenance Costs (Filter Replacement, Professional Cleaning)
3.2.2.4 Intense Price Competition from Low-Cost Asian Manufacturers
3.2.3 Market Opportunities
3.2.3.1 Smart & Connected Range Hood Adoption (Auto-Sensing, Voice Control, App Integration)
3.2.3.2 Ghost Kitchen & Cloud Kitchen Boom Driving Commercial Segment Demand
3.2.3.3 Energy-Efficient Product Innovation for Green Building Certifications (LEED, BREEAM)
3.2.3.4 Emerging Market Urbanization (India, Southeast Asia) Driving First-Time Buyer Demand
3.3 Growth Potential Analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis (Driven by Primary Research)
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus) (Driven by Primary Research)
3.5 Regulatory Landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia Pacific
3.5.4 Latin America
3.5.5 Middle East & Africa
3.6 Porter's Analysis
3.6.1 Bargaining Power of Suppliers
3.6.2 Bargaining Power of Buyers
3.6.3 Threat of New Entrants
3.6.4 Threat of Substitute Products
3.6.5 Intensity of Competitive Rivalry
3.7 PESTEL Analysis
3.7.1 Political Factors
3.7.2 Economic Factors
3.7.3 Social Factors
3.7.4 Technological Factors
3.7.5 Environmental Factors
3.7.6 Legal Factors
3.8 Trade Data Analysis (Driven by Primary Research)
3.8.1 Import/Export Volume & Value Trends (Driven by Primary Research)
3.8.2 Key Trade Corridors & Tariff Impact (Driven by Primary Research)
3.9 Impact of AI & Generative AI on the Market
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
3.10 Distribution Infrastructure & Channel Penetration Landscape (Driven by Primary Research)
3.10.1 Channel Coverage by Region & Format (Modern vs. Traditional Trade) (Driven by Primary Research)
3.10.2 Last-Mile Infrastructure Gaps & Emerging Channel Shifts (Driven by Primary Research)
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company Market Share Analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East & Africa
4.2.2 Market Concentration Analysis
4.3 Competitive Analysis of Major Market Players
4.4 Competitive Positioning Matrix
4.5 Key Developments
4.5.1 Mergers & Acquisitions
4.5.2 Partnerships & Collaborations
4.5.3 New Product Launches
4.5.4 Expansion Plans & Funding
4.6 Company Tier Benchmarking
4.6.1 Tier Classification Criteria & Qualifying Thresholds
4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5. Range Hood Market Estimates & Forecast, by Product Type (USD Million, 2022–2035)
5.1 Key Trends, by Product Type
5.2 Wall Mount Range Hood
5.2.1 Standard Wall Mount
5.2.2 Convertible Wall Mount
5.3 Under Cabinet Range Hood
5.3.1 Standard Under Cabinet
5.3.2 Slim/Low-Profile Under Cabinet
5.4 Ceiling/Island Mount Range Hood
5.4.1 Standard Island Hood
5.4.2 Designer/Custom Island Hood
5.5 Downdraft Ventilation Hood
5.5.1 Retractable Downdraft
5.5.2 Fixed Downdraft
5.6 Insert/Built-In Range Hood
5.6.1 Standard Insert
5.6.2 Professional-Grade Insert
5.7 Others
Chapter 6. Range Hood Market Estimates & Forecast, by Ventilation System (USD Million, 2022–2035)
6.1 Key Trends, by Ventilation System
6.2 Ducted (Vented)
6.2.1 External Wall Ducting
6.2.2 Roof/Ceiling Venting
6.3 Non-Ducted (Recirculating)
6.3.1 Charcoal Filter-Based
6.3.2 Carbon/Activated Filter-Based
Chapter 7. Range Hood Market Estimates & Forecast, by Application (USD Million, 2022–2035)
7.1 Key Trends, by Application
7.2 Residential
7.2.1 New Construction
7.2.2 Renovation & Replacement
7.3 Commercial
7.3.1 Restaurants & Food Service Outlets
7.3.2 Hotels & Hospitality
7.3.3 Institutional Kitchens (Schools, Hospitals, Canteens)
7.3.4 Ghost Kitchens & Cloud Kitchens
Chapter 8. Range Hood Market Estimates & Forecast, by Distribution Channel (USD Million, 2022–2035)
8.1 Key Trends, by Distribution Channel
8.2 Online
8.2.1 Brand Websites & Direct-to-Consumer (DTC)
8.2.2 E-Commerce Marketplaces (Amazon, Flipkart, JD.com, etc.)
8.3 Offline
8.3.1 Specialty Appliance Stores
8.3.2 Home Improvement Retail (Home Depot, Lowe's, B&Q, etc.)
8.3.3 Supermarkets & Hypermarkets
8.3.4 Direct Sales & Trade/Contractor Channels
Chapter 9. Range Hood Market Estimates & Forecast, by Width (USD Million, 2022–2035)
9.1 Key Trends, by Width
9.2 Up to 30 Inches
9.3 30 to 36 Inches
9.4 36 to 42 Inches
9.5 Above 42 Inches
Chapter 10. Range Hood Market Estimates & Forecast, by Price Range (USD Million, 2022–2035)
10.1 Key Trends, by Price Range
10.2 Economy/Budget
10.3 Mid-Range
10.4 Premium/Luxury
Chapter 11. Range Hood Market Estimates & Forecast, by Region (USD Million, 2022–2035)
11.1 Key Trends, by Region
11.2 North America
11.2.1 U.S.
11.2.2 Canada
11.3 Europe
11.3.1 Germany
11.3.2 UK
11.3.3 France
11.3.4 Italy
11.3.5 Spain
11.3.6 Rest of Europe
11.4 Asia Pacific
11.4.1 China
11.4.2 Japan
11.4.3 India
11.4.4 South Korea
11.4.5 Australia
11.4.6 Rest of Asia Pacific
11.5 Latin America
11.5.1 Brazil
11.5.2 Mexico
11.5.3 Rest of Latin America
11.6 Middle East & Africa
11.6.1 UAE
11.6.2 Saudi Arabia
11.6.3 South Africa
11.6.4 Rest of Middle East & Africa
Chapter 12. Company Profiles (Driven by Primary Research)
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Avinash Singh. 2026, September. Range Hood Market (Report ID: GMI4421). Global Market Insights Inc. Retrieved November 13, 2026, from https://www.gminsights.com/toc/details/range-hood-market

Range Hood Market
Get a free sample of this report
Range Hood Market Size
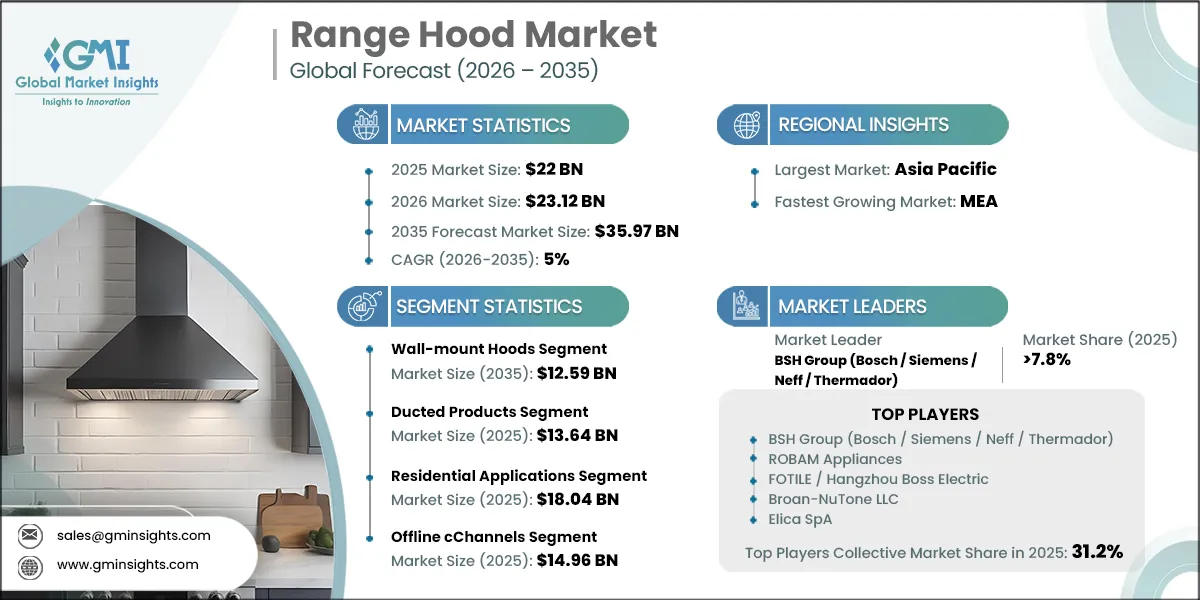
The Range Hood Market was valued at USD 22 billion in 2025, is expected to reach USD 23.12 billion in 2026, is projected to grow at a 5.0% CAGR (2026–2035), and is anticipated to reach USD 35.97 billion by 2035. The market covers manufacturer-level revenue from residential and commercial ventilation units installed above cooking surfaces, including wall-mount, ceiling/island, under-cabinet, downdraft, and insert/built-in products in ducted and recirculating configurations.
The Range Hood Market is moving from a largely functional appliance category toward a more differentiated kitchen-design and indoor-air-quality purchase. Replacement demand, renovation activity, compliance-led specifications, and premiumization are increasingly important to revenue growth, while new construction remains a decisive volume source in rapidly urbanizing markets.
GMI Analyst View
Our multi-horizon forecast modeling and discussions with channel partners indicate that the global range hood market is projected to reach USD 28.48 billion in 2030. This milestone reflects a recovery in installation activity, a growing renovation-led replacement cycle in mature markets, and a continued shift toward higher-value ventilation formats.
Range Hood Market Trends, Growth Drivers & GMI Forecast Outlook
The market is being shaped by the convergence of housing activity, kitchen renovation, local-exhaust requirements, and consumer demand for quieter, more integrated appliances. Revenue expansion will depend on whether manufacturers can convert regulatory and design-led demand into premium mix gains while limiting exposure to construction weakness and price-led channel pressure.
Key Drivers
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Multifamily development is particularly relevant because it concentrates appliance specifications in projects where installation timing, contractor availability, and compliance documentation matter as much as retail preference. This supports stable demand for standardized products, while the renovation channel remains the principal route for premium wall-mount and island formats to gain share in mature housing markets.
India presents a different demand profile from mature replacement markets. Housing formation, modular-kitchen adoption, and increasing awareness of cooking-related pollutants are expanding the addressable consumer base, giving manufacturers an opportunity to establish distribution and service networks before brand preferences become deeply entrenched.
Ventilation standards also affect product engineering and channel qualification. Products that combine effective capture, manageable noise, and installation compatibility are better placed to win builder, remodeler, and green-building specifications, particularly where buyers view local exhaust as part of a broader indoor-air-quality upgrade.
Key Restraints
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Single-family affordability pressure affects more than housing volumes; it also changes the composition of appliance demand. When households defer moves or whole-home projects, manufacturers must compete harder for partial kitchen upgrades, where consumers compare ventilation purchases against cabinetry, countertops, and other renovation expenditures.
China's price environment is structurally challenging because digital platforms make competitive offers highly visible and promote frequent discounting. Brands with differentiated sensing, cleaning, service, or bundled kitchen capabilities have more room to protect value, whereas undifferentiated mid-tier products remain exposed to margin and pricing pressure.
Ducted conversion faces practical constraints that do not disappear simply because consumers prefer better pollutant removal. Retrofit projects can require routing changes, approval from building management, and coordination among several trades; quiet, high-performance systems can therefore remain concentrated in premium installations rather than becoming a universal replacement choice.
GMI Analyst View
We view the forecast as a contest between compliance- and design-led premiumization on one side and construction softness and channel discounting on the other. The stronger manufacturers will be those that protect value through specification access, acoustic engineering, and direct customer relationships rather than relying solely on unit-volume growth.
Range Hood Market Segment Analysis
By Product Type
Wall-mount hoods are the leading format within the Range Hood Market, generating USD 8.36 billion in 2025 and are projected to reach USD 12.59 billion by 2035. Wall-mount hoods retain broad relevance because they fit conventional kitchen layouts, span builder-grade to premium price points, and offer a visible upgrade path for remodelers. Their breadth makes the segment resilient, although open-plan design is gradually redirecting a portion of premium demand toward island configurations.
Under-cabinet products are projected to reach USD 6.47 billion by 2035 and represented 20.0% of the market in 2025. This segment remains central to cost-sensitive builder and replacement demand because it aligns with standard upper-cabinet configurations and has relatively straightforward installation requirements. Its strategic challenge is maintaining relevance as kitchen layouts and consumer preferences shift toward more integrated or visually unobtrusive ventilation.
Downdraft products are projected to reach USD 2.88 billion by 2035 and held an 8.0% market share in 2025. Downdraft systems address a specialized need in layouts where overhead equipment would disrupt sightlines. Their niche is reinforced by premium kitchen design, but penetration is constrained by installation complexity, countertop integration, and a higher ownership cost than conventional hood formats.
Insert/built-in products generated USD 2.64 billion in 2025 and are projected to grow at a 5.0% CAGR (2026–2035). Insert systems are closely linked to custom cabinetry, remodeler specifications, and modular-kitchen development. Their appeal rests on concealed integration and flexibility in matching a ventilation product to bespoke kitchen furniture, making them relevant to premium renovation projects even where broader construction conditions are mixed.
By Ventilation Type
Ducted products generated USD 13.64 billion in 2025, and are projected to account for 65.0% of the market by 2035. Ducted systems benefit from stronger performance perceptions, growing local-exhaust requirements, and the preference of professional installers for solutions that remove contaminants from the kitchen rather than filtering and returning air. Their growth is most compelling where building design can accommodate routing without costly structural changes.
Non-ducted products represented 38.0% of revenue in 2025 and are projected to reach USD 12.59 billion by 2035. Recirculating models remain indispensable in apartments and retrofit settings where external ducting is impractical. Their continued relevance is therefore less a matter of technical preference than of housing-stock realities, installation convenience, and buyer sensitivity to project disruption.
By Application
Residential applications generated USD 18.04 billion in 2025, and are projected to account for 78.0% of the market by 2035. Residential demand is supported by the replacement cycle across the installed base, renovation spending, and household formation. The modest share shift reflects faster expansion in commercial installations rather than a weakening of the household market, which remains the category's broadest and most durable source of demand.
By Distribution Channel
Offline channels generated USD 14.96 billion in 2025, and are projected to account for 58.0% of the market by 2035. Physical retail, showrooms, contractor networks, and developer-direct channels remain essential because many purchases require assessment of fit, sound, lighting, and installation requirements. Offline engagement is particularly important for ducted and premium formats, where professional guidance can reduce purchase and installation risk.
Online channels are projected to reach USD 15.11 billion by 2035, and are expected to grow at a 7.9% CAGR (2026–2035). Digital channels are changing both consumer discovery and price formation. Brands with strong product content, reliable installation support, and direct service capabilities can use online distribution to extend reach, but transparent comparison tools and promotion-led marketplaces also intensify pressure on less differentiated products.
GMI Analyst View
We see the segment mix separating into design-led premium products and highly price-sensitive functional products. The strategic opportunity lies in serving both without diluting positioning: manufacturers need accessible products for broad replacement demand and technically credible, aesthetically distinctive offerings for projects where ventilation is part of the kitchen's overall design decision.
Range Hood Market Regional Analysis
North America Range Hood Market Analysis
The Range Hood Market in North America generated USD 6.27 billion in 2025, and is projected to reach USD 9.39 billion by 2035. The region combines a large installed base with a sophisticated renovation ecosystem, making replacement demand as important as new construction. Building-performance requirements and retailer-contractor ecosystems favor suppliers that can offer certified products, dependable fulfillment, and a portfolio spanning installation-grade to premium formats.
USA
The USA generated USD 5.29 billion in 2025 and is projected to account for 82.7% of the North American market by 2035. The U.S. market is shaped by its extensive remodeling channel, builder specifications, and broad home-improvement retail infrastructure. Affordability pressure can limit first-fit demand in the near term, but homeowners who remain in place often prioritize targeted kitchen improvements that sustain replacement opportunities.
Canada
Canada accounted for 10.7% of North American revenue in 2025 and is expected to grow at a 4.5% CAGR (2026–2035). Canadian demand is concentrated in urban multifamily construction and renovation activity, where efficient, quiet, and code-compatible equipment has particular value. Alignment between provincial requirements and broader North American performance standards supports adoption of higher-specification models.
Europe Range Hood Market Analysis
Europe is projected to reach USD 6.41 billion by 2035 and grow at a 3.8% CAGR (2026–2035). Europe's mature category penetration limits volume acceleration, but the region remains disproportionately influential in design, acoustic engineering, integration, and premium appliance positioning. Renovation-led demand and efficiency-oriented product specifications favor suppliers able to combine aesthetics with technical performance.
Germany
Germany generated USD 1.32 billion in 2025 and is projected to reach USD 1.86 billion by 2035. Germany's market is supported by technically informed consumers, a strong renovation culture, and domestic premium-appliance capability. Product selection often places greater weight on engineering quality, integration, and long-life performance than on entry-level price alone.
Italy
Italy represented 17.4% of European revenue in 2025 and is expected to grow at a 3.2% CAGR (2026–2035). Italy remains important as both a consumption market and a design-and-manufacturing center for premium ventilation. Its supplier base gives domestic buyers early access to product innovation while reinforcing the global influence of Italian design in island, wall-mount, and built-in formats.
France
France generated USD 0.53 billion in 2025 and is projected to account for 11.3% of European revenue by 2035. French demand is closely tied to renovation of the existing housing base and preference for visually integrated kitchens. Regulatory attention to ventilation quality provides a stable specification backdrop, particularly where builders and remodelers prioritize energy and indoor-environment performance.
UK
The UK is projected to reach USD 0.60 billion by 2035 and represented 9.8% of European revenue in 2025. Demand in the UK is shaped by premium urban kitchen projects alongside an older housing stock where external venting can be difficult. That constraint preserves the relevance of recirculating and compact integrated products even as higher-performance ducted systems gain traction in new developments.
Spain
Spain represented 7.6% of European revenue in 2025 and is expected to grow at a 3.0% CAGR (2026–2035). Measured construction recovery and renovation activity support the Spanish market. Demand is strongest where new urban development, tourism-linked property investment, and replacement spending create opportunities for branded kitchen-appliance suppliers.
Asia Pacific Range Hood Market Analysis
The Range Hood Market in Asia Pacific generated USD 9.24 billion in 2025, and is projected to reach USD 16.55 billion by 2035, representing 46.0% of global revenue. Asia Pacific combines China's large installed base with rapid kitchen modernization and housing expansion elsewhere in the region. Its scale makes channel strategy decisive: companies must balance China's price-intensive digital market with opportunities for first-fit growth and premium category formation across other Asian economies.
China
China generated USD 6.17 billion in 2025, and is projected to reach USD 10.79 billion by 2035. China remains the region's central market because of its installed base, deep domestic-brand competition, and digitally mature consumer channels. Although property-sector weakness restrains new-build momentum, replacement demand and adoption of sensing, cleaning, and connected features give leading brands avenues to defend value.
Japan
Japan represented 13.7% of Asia Pacific revenue in 2025 and is expected to grow at a 3.0% CAGR (2026–2035). Japan is a mature, replacement-driven market where noise performance, energy efficiency, and reliability are prominent purchase criteria. Its sophisticated consumer expectations continue to influence motor, filtration, and control-system innovation that can later migrate to other regional platforms.
India
India is projected to reach USD 2.18 billion by 2035, and is expected to grow at a 10.0% CAGR (2026–2035). India is in a category-building phase, with urban housing, modular kitchens, and greater awareness of kitchen-air quality expanding the addressable base. Construction pipeline growth and rising household purchasing power create an opportunity for companies that can match product design, price architecture, and local distribution to diverse urban markets. [2]
South Korea
South Korea generated USD 0.53 billion in 2025 and is projected to account for 4.8% of Asia Pacific revenue by 2035. South Korea is characterized by premium consumer expectations around connectivity, automation, and low-noise operation. The market rewards integration with broader smart-home ecosystems, giving suppliers with credible technology platforms an advantage in upper-tier kitchen projects.
Latin America Range Hood Market Analysis
Latin America is projected to reach USD 2.17 billion by 2035 and grow at a 5.1% CAGR (2026–2035). The region's outlook is linked to urbanization, household-income development, and broader availability of branded appliances through organized retail and e-commerce. Market performance remains sensitive to country-level construction and consumer-spending conditions, making adaptable price and distribution strategies essential.
Brazil
Brazil generated USD 0.77 billion in 2025, and is projected to reach USD 1.26 billion by 2035. Brazil anchors regional demand through its large consumer base and expanding organized appliance channels. Price sensitivity remains pronounced, but the growth of foodservice, cloud kitchens, and urban renovation supports opportunities across both residential and commercial installations.
Middle East & Africa Range Hood Market Analysis
The Range Hood Market in Middle East & Africa generated USD 0.77 billion in 2025, and is expected to grow at a 6.5% CAGR (2026–2035). The region's growth is concentrated in residential, hospitality, and mixed-use projects, especially where major developments specify premium appliances and commercial ventilation. This creates attractive opportunities but also makes demand sensitive to the timing and execution of capital projects.
Saudi Arabia
Saudi Arabia generated USD 0.34 billion in 2025, and is expected to grow at a 7.2% CAGR (2026–2035). Saudi Arabia's market is supported by residential development, tourism infrastructure, and mixed-use investment. Suppliers that can meet project specifications, provide dependable local support, and serve both household and hospitality demand are best positioned to benefit from the country's construction-led growth.
UAE
The UAE is projected to reach USD 0.34 billion by 2035, and accounted for 25.0% of regional revenue in 2025. The UAE's premium residential and hospitality mix supports demand for design-led and specification-grade ventilation solutions. Developers and kitchen specialists place particular value on finish quality, compact integration, and dependable service, especially in luxury apartment and villa projects.
GMI Analyst View
We expect Asia Pacific to remain the principal source of incremental demand, but the regional story is becoming more diversified than a single-country growth narrative. China will remain essential for scale, while India and other developing Asian markets offer broader first-fit potential; meanwhile, Europe's importance rests on innovation and premium reference-setting rather than volume growth alone.
Range Hood Market Share & Competitive Landscape
The Range Hood Market share landscape is moderately concentrated, with the five leading participants collectively accounting for approximately 31.2% of global revenue in 2025. Competition remains fragmented because kitchen styles, installation practices, consumer preferences, and distribution structures vary widely across markets, leaving substantial room for regional specialists, private-label suppliers, and direct-to-consumer entrants.
BSH Group held a 7.8% global market share in 2025. Its competitive strength is its multi-brand architecture, which allows the company to address mass-premium, premium, and ultra-premium kitchen projects while leveraging broad manufacturing and distribution capabilities.
ROBAM Appliances held a 7.5% global market share in 2025. The company's position is rooted in China's digital retail ecosystem and its focus on higher-value products incorporating sensing, cleaning, and integrated kitchen capabilities.
FOTILE Group held a 7.3% global market share in 2025. Its differentiation centers on products tailored to high-heat cooking practices, strong domestic brand recognition, and growing efforts to translate Chinese-market product expertise into international premium channels.
Broan-NuTone is strategically important in North America because of its builder and home-improvement distribution reach, while Elica and Faber reinforce the influence of Italian design and integrated premium-kitchen positioning. Miele, Novy, Falmec, Bertazzoni, and Gaggenau compete where acoustic performance, cabinetry integration, and designer specification matter more than mass-market scale.
Whirlpool, Electrolux, Midea, Haier, Panasonic, VATTI, Arcelik, Zephyr, ZLINE, Cosmo, and Vent-A-Hood illustrate the category's wide competitive spectrum. Portfolio breadth, white-goods distribution, digital reach, specialist engineering, and price architecture are all viable routes to relevance, but no single capability is sufficient across every geography and channel.
Recent Industry Developments
Elica completed its acquisition of a 28% stake in Steel S.r.l. in November 2025, establishing a progressive mechanism that could increase its ownership over time. The transaction broadens Elica's access to premium cooking products and supports its strategy of competing for a larger share of high-end residential and hospitality kitchen specifications in North America and Europe. [5]
Broan-NuTone introduced its ENERGY STAR-certified Roomside Series at the 2025 International Builders' Show, featuring EZDuct™ airtight installation technology and SlideClip™ grilles. The launch addresses builder and contractor requirements for installation efficiency and code-aligned ventilation performance, reinforcing the company's specification-channel position. [6]
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.