
Flow Chemistry Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research Approach
1.2 Quality Commitments
1.2.1 GMI AI Policy & Data Integrity Commitment
1.2.1.1 Source Consistency Protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial List of Primary Sources
1.5 Data Mining Sources
1.5.1 Paid Sources
1.5.1.1 Sources, By Region
1.6 Base Estimates & Calculations
1.6.1 Base Year Calculation
1.7 Forecast Model
1.7.1 Quantified Market Impact Analysis
1.7.1.1 Mathematical Impact of Growth Parameters on Forecast
1.8 Research Transparency Addendum
1.8.1 Source Attribution Framework
1.8.2 Quality Assurance Metrics
1.8.3 Our Commitment to Trust
Chapter 2. Executive Summary
2.1 Industry 360° Synopsis
2.2 Key Market Trends
2.2.1 Reactor Type Trends
2.2.2 Application Trends
2.2.3 End Use Industry Trends
2.2.4 Regional Trends
2.3 TAM analysis, 2027-2035–2035 (USD Billion)
2.4 CXO Perspectives: Strategic Imperatives
Chapter 3. Industry Insights
3.1 Industry Ecosystem Analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost Structure
3.1.4 Value Addition at Each Stage
3.1.5 Factors Affecting the Value Chain
3.1.6 Disruptions
3.2 Industry Impact Forces
3.2.1 Growth Drivers
3.2.2 Industry Pitfalls & Challenges
3.2.3 Market Opportunities
3.3 Growth Potential Analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis (Driven by Primary Research)
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus) (Driven by Primary Research)
3.5 Regulatory Landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia Pacific
3.5.4 Latin America
3.5.5 Middle East & Africa
3.6 Porter's Analysis
3.7 PESTEL Analysis
3.8 Trade Data Analysis (Based on Paid Database)
3.8.1 Import/Export Volume & Value Trends (Based on Paid Database)
3.8.2 Key Trade Corridors & Tariff Impact (Based on Paid Database)
3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
3.10 Capacity & Production Landscape (Driven by Primary Research)
3.10.1 Production Capacity by Region & Key Producer (Driven by Primary Research)
3.10.2 Capacity Utilization Rates & Expansion Pipelines (Driven by Primary Research)
3.11 Forecast Assumptions & Scenario Analysis (Driven by Primary Research)
3.11.1 Base Case — Key Macro & Industry Variables Driving CAGR
3.11.2 Optimistic Scenario — Favourable Macro & Industry Tailwinds
3.11.3 Pessimistic Scenario — Macroeconomic Slowdown or Industry Headwinds
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company Market Share Analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East & Africa
4.2.2 Market Concentration Analysis
4.3 Competitive Analysis of Major Market Players
4.4 Competitive Positioning Matrix
4.5 Key Developments
4.5.1 Mergers & Acquisitions
4.5.2 Partnerships & Collaborations
4.5.3 New Product Launches
4.5.4 Expansion Plans & Funding
4.6 Company Tier Benchmarking
4.6.1 Tier Classification Criteria & Qualifying Thresholds
4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5. Reactor Type Market Estimates & Forecast (USD Million, 2022–2035)
5.1 Microreactor Systems
5.1.1 Glass/Borosilicate Microreactors
5.1.2 Silicon & Silicon Carbide Microreactors
5.1.3 Stainless Steel Microreactors
5.1.4 Polymer (PTFE/PFA) Microreactors
5.2 Continuous Stirred Tank Reactors (CSTR)
5.2.1 Conventional CSTR
5.2.2 Advanced CSTR Designs (Multi-stage, Jacketed)
5.3 Plug Flow Reactors (PFR) / Tubular Reactors
5.3.1 Straight Tubular PFR
5.3.2 Coiled & Serpentine PFR
5.4 Photochemical Flow Reactors
5.4.1 UV-Based Photochemical Reactors
5.4.2 Visible Light (LED-Driven) Photochemical Reactors
5.5 Electrochemical Flow Reactors
5.5.1 Divided Cell Electrochemical Reactors
5.5.2 Undivided Cell Electrochemical Reactors
5.6 Packed-Bed Reactors
5.6.1 Heterogeneous Catalysis Packed-Bed
5.6.2 Scavenger & Reagent-Loaded Packed-Bed
5.7 Others (Oscillatory Flow Reactors, Droplet-Based Reactors, Modular Flow Systems)
Chapter 6. Application Market Estimates & Forecast (USD Million, 2022–2035)
6.1 Pharmaceutical Synthesis
6.1.1 Active Pharmaceutical Ingredient (API) Synthesis
6.1.2 Drug Intermediate & Building Block Synthesis
6.1.3 Controlled Substance & Hazardous Chemistry Synthesis
6.2 Chemical Synthesis
6.2.1 Fine Chemical Synthesis
6.2.2 Specialty Chemical Synthesis
6.2.3 Basic Chemical Intermediate Production
6.3 Agrochemical Synthesis
6.3.1 Pesticide & Herbicide Active Ingredient Synthesis
6.3.2 Fertilizer Intermediate Synthesis
6.4 Polymer & Material Science
6.4.1 Specialty Polymer Synthesis
6.4.2 Nanomaterial & Nanoparticle Synthesis
6.5 Biotechnology & Life Sciences
6.5.1 Enzymatic & Biocatalytic Flow Reactions
6.5.2 Bioconjugation & Biochemical Synthesis
6.6 Energy Conversion
6.6.1 Hydrogen Production via Electrochemical Flow
6.6.2 Fuel Cell Material Synthesis
6.6.3 Battery Active Material Synthesis
6.7 Others (Food & Beverage Additive Synthesis, Academic R&D Applications)
Chapter 7. End-Use Industry Market Estimates & Forecast (USD Million, 2022–2035)
7.1 Pharmaceutical & Biotechnology
7.1.1 Integrated Pharmaceutical Manufacturers
7.1.2 Contract Development & Manufacturing Organizations (CDMOs)
7.1.3 Biopharmaceutical & Gene Therapy Developers
7.2 Chemical & Petrochemical Industry
7.2.1 Specialty Chemical Producers
7.2.2 Petrochemical & Commodity Chemical Companies
7.3 Agrochemical Industry
7.3.1 Crop Protection Manufacturers
7.3.2 Agricultural Input Producers
7.4 Academic & Research Institutions
7.4.1 Universities & Graduate Research Laboratories
7.4.2 Government & National Research Laboratories
7.5 Food & Beverage
7.5.1 Flavor & Fragrance Manufacturers
7.5.2 Food Additive & Ingredient Producers
7.6 Others
Chapter 8. Regional Market Estimates & Forecast (USD Million, 2022–2035)
8.1 North America
8.1.1 Market Estimates & Forecast (USD Million, 2022–2035)
8.1.2 U.S.
8.1.3 Canada
8.1.4 Mexico
8.2 Europe
8.2.1 Market Estimates & Forecast (USD Million, 2022–2035)
8.2.2 Germany
8.2.3 UK
8.2.4 France
8.2.5 Italy
8.2.6 Spain
8.2.7 Rest of Europe
8.3 Asia Pacific
8.3.1 Market Estimates & Forecast (USD Million, 2022–2035)
8.3.2 China
8.3.3 Japan
8.3.4 India
8.3.5 South Korea
8.3.6 Australia
8.3.7 Rest of Asia Pacific
8.4 Latin America
8.4.1 Market Estimates & Forecast (USD Million, 2022–2035)
8.4.2 Brazil
8.4.3 Argentina
8.4.4 Rest of Latin America
8.5 Middle East & Africa
8.5.1 South Africa
8.5.2 Saudi Arabia
8.5.3 UAE
8.5.4 Rest of Middle East & Africa
Chapter 9. Company Profiles
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Kiran Pulidindi. 2026, September. Flow Chemistry Market – By Reactor Type, By Material Type, & By Application, – Growth Forecast, 2026 – 2035 (Report ID: GMI1106). Global Market Insights Inc. Retrieved October 26, 2026, from https://www.gminsights.com/toc/details/flow-chemistry-market

Flow Chemistry Market
Get a free sample of this report
Flow Chemistry Market Size
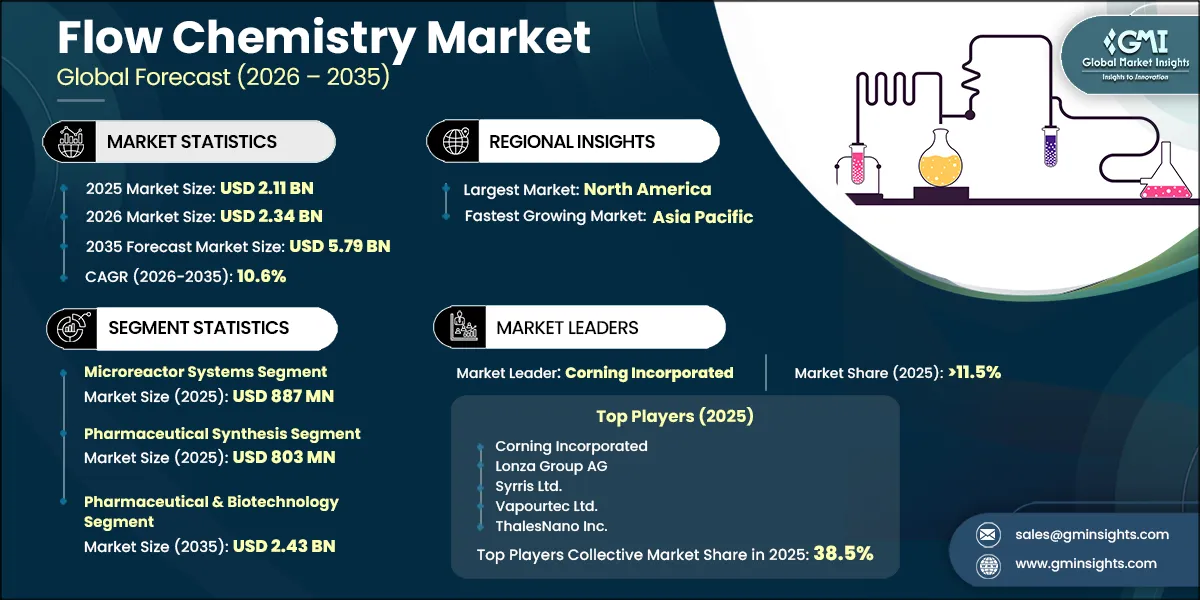
The flow chemistry market was valued at USD 2.11 billion in 2025, is expected to reach USD 2.34 billion in 2026, will expand at a 10.6% CAGR (2026–2035), and is projected to reach USD 5.79 billion by 2035.
The market encompasses end-user procurement of continuous-flow reactor equipment, integrated systems, and directly associated bundled hardware and software. Demand is shifting from research-led experimentation toward production-oriented deployment where controlled residence time, heat transfer, pressure management, and enclosed processing improve the economics and safety profile of complex synthesis.
GMI Analyst View
Our analysis of demand-side procurement flows for continuous-flow reactor equipment confirms that the flow chemistry market registered USD 1.91 billion in 2024, a figure that validates the consistent pre-base-year expansion trajectory underpinning our 2025 baseline and supports the 2026–2035 forecast growth path across pharmaceutical, chemical, and research end-use segments.
Flow Chemistry Market Trends, Growth Drivers & GMI Forecast Outlook
Regulatory harmonization is making continuous-manufacturing qualification more legible for pharmaceutical manufacturers, while demonstrated performance advantages are strengthening the case for purpose-built flow assets. ICH Q13 provides a shared regulatory reference point for continuous manufacturing [1], and published evidence identifies meaningful quality and throughput gains under suitable implementation conditions [2].
Key Drivers
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
ICH Q13 has reduced uncertainty around the validation, control, and regulatory presentation of continuous manufacturing. That change matters commercially because it allows pharmaceutical process-development teams to evaluate flow assets within established quality and capital-governance processes rather than treating each installation as an exceptional technology programme.
The demand effect is strongest where flow equipment improves a constrained production route rather than simply replacing a familiar vessel. Published continuous-manufacturing experience has associated the model with a 40% improvement in product dose uniformity relative to batch benchmarks [2]. For buyers, the relevant value lies in better process control, lower rejection exposure, and greater confidence in scaling validated chemistry.
Key Restraints
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Integrated flow platforms require more than a reactor purchase. Pumps, back-pressure regulation, thermal control, inline analytics, automation, and process-development support must work as a validated operating system. This concentrates early commercial adoption among buyers that can commit internal engineering capacity and establish product-volume certainty.
The technical conversion burden also slows adoption. Residence-time distributions, heat-transfer geometry, phase behavior, and catalyst response can differ materially from the corresponding batch route, requiring process redevelopment rather than a straightforward equipment substitution. Suppliers that can support this translation from route scouting to commercial operation are better positioned to convert customer interest into production-scale orders.
GMI Analyst View
We view the central forecast question as the pace at which capital and capability constraints ease for mid-market adopters. Regulatory clarity has improved the investment case, but scalable adoption will depend on whether CDMOs and equipment suppliers can spread technical risk across multiple customer programmes without sacrificing process-specific performance.
Flow Chemistry Market Segment Analysis
By Reactor Type
Microreactor Systems generated USD 887 million in 2025 and are projected to account for 40.0% of market revenue by 2035. Microreactors remain the commercial entry point for many pharmaceutical, fine-chemical, and research users because their compact channels provide strong heat-transfer control, defined residence times, and safer handling of sensitive or hazardous reaction systems. Their material flexibility also supports use across glass, silicon, metal, and polymer configurations.
PFR/Tubular systems held a 21.0% market share in 2025 and are projected to reach USD 1.22 billion by 2035. The flow chemistry market relies on PFR and tubular architectures where extended, tightly controlled residence times are required for API intermediates, organometallic chemistry, and other demanding synthesis routes. Their production relevance rises when customers move beyond screening toward multi-step continuous manufacturing.
CSTR systems generated USD 338 million in 2025 and are expected to grow at a 9.9% CAGR (2026–2035). Continuous stirred-tank configurations serve liquid-phase chemistries that require mixing tolerance or longer residence periods, including selected enzymatic, fermentation, and polymerization processes. Their growth profile reflects a durable niche, although newer photochemical and electrochemical formats are attracting greater attention in high-value synthesis programmes.
Photochemical Reactors held a 9.0% market share in 2025 and are projected to reach USD 636 million by 2035. Photochemical flow systems address light-driven reactions for which batch processing can be limited by penetration depth, thermal management, and scale-up consistency. Advances in wavelength-controlled LED systems are widening the industrial relevance of photoredox and related transformations.
Electrochemical Reactors are expected to grow at a 12.3% CAGR (2026–2035) and reach USD 405 million by 2035. Electrochemical flow platforms replace selected stoichiometric oxidants and reductants with controlled electron transfer, reducing reagent-handling burdens and supporting lower-waste process design. Interest is particularly strong where pharmaceutical and specialty-chemical producers are evaluating non-thermal activation routes.
Packed Bed Reactors generated USD 85 million in 2025 and are forecast to grow at a 10.5% CAGR (2026–2035). Packed-bed systems support heterogeneous catalysis and scavenger applications in continuous production. Their adoption depends on catalyst life, pressure-drop management, and modular maintenance design, making monitoring and rapid cartridge or bed replacement important competitive features.
By Application
Pharmaceutical Synthesis generated USD 803 million in 2025 and is projected to represent 40.0% of market revenue by 2035. Pharmaceutical synthesis is the principal demand base for continuous-flow equipment because API and intermediate routes frequently require tight control of exotherms, reaction time, impurity profiles, and hazardous reagents. Regulatory acceptance is reinforcing investment across integrated manufacturers and CDMOs.
Chemical Synthesis represented a 27.0% share of application revenue in 2025 and is projected to reach USD 1.45 billion by 2035. Fine and specialty chemical producers use flow systems to intensify high-value, low-volume reactions where yield, solvent use, and safety can justify a dedicated capital investment. The application is therefore more closely tied to differentiated chemistry than to commodity chemical production.
Agrochemical Synthesis generated USD 253 million in 2025 and is expected to grow at a 9.6% CAGR (2026–2035). Agrochemical routes involving nitration, chlorination, diazotization, and similarly hazardous intermediates benefit from the small inventories and controlled stoichiometry achievable in enclosed flow equipment. Adoption remains measured because crop-cycle exposure and product-registration cycles can lengthen capital decisions.
Polymer/Material Science held a 9.0% market share in 2025 and is expected to reach USD 520 million by 2035. The flow chemistry market is gaining relevance in polymer and materials development where molecular-weight distribution, end-group functionality, particle characteristics, and reproducibility are commercial quality attributes. Continuous processing gives developers greater control over those parameters than conventional batch mixing in selected routes.
Biotechnology/Life Sciences is projected to grow at a 13.1% CAGR (2026–2035) and reach USD 578 million by 2035. Biocatalytic reactions, bioconjugation, and advanced building-block synthesis are expanding the need for platforms that can manage temperature-sensitive substrates, aqueous phases, and biological catalysts. CDMO investment in advanced biopharmaceutical intermediates is a key route to commercial demand.
Energy Conversion generated USD 84 million in 2025 and is projected to reach USD 231 million by 2035. Energy-related use remains a smaller application base, but electrochemical flow equipment is increasingly relevant to hydrogen, fuel-cell-material, and battery-material research. Its commercial trajectory depends on the pace at which energy-system development moves from laboratory work into repeatable industrial processing.
By End-Use Industry
Pharmaceutical & Biotechnology generated USD 887 million in 2025 and is projected to reach USD 2.43 billion by 2035. Integrated drug manufacturers, biopharmaceutical developers, and CDMOs form the most consequential buyer group because they can deploy flow equipment from process development through commercial manufacturing. Multi-client CDMO facilities can also create repeat procurement cycles as capacity and customer programmes expand.
Chemical & Petrochemical accounted for a 29.0% share of end-use revenue in 2025 and is projected to reach USD 1.68 billion by 2035. Adoption is concentrated in specialty and fine chemicals, where process intensification can improve yield, quality consistency, and resource efficiency. Commodity-scale refining remains less central to the addressable equipment opportunity.
Agrochemical end users held a 12.0% market share in 2025 and are projected to hold an 11.0% share by 2035. The modest relative decline reflects faster expansion in pharmaceutical and biotechnology demand rather than a contraction in agrochemical adoption. Buyers in this segment continue to prioritize safer control of hazardous intermediates and compact modular production formats.
Academic/Research Institutions are projected to account for 9.0% of market revenue by 2035 and grow at a 9.5% CAGR (2026–2035). Universities, government laboratories, and national research facilities sustain demand for modular platforms used in synthetic-method development and proof-of-concept scale-up. This installed base also supports workforce familiarity with continuous processing before researchers move into industrial roles.
Food & Beverage is expected to grow at a 13.2% CAGR (2026–2035) and reach USD 289 million by 2035. Food and ingredient manufacturers are evaluating controlled continuous routes for additives, flavor compounds, enzyme-modified ingredients, and nutraceutical inputs. Their adoption is linked to demand for consistent, traceable, and hygienically produced functional ingredients.
GMI Analyst View
We see a market with an established pharmaceutical-microreactor core and a faster-moving frontier in electrochemical, photochemical, and life-sciences applications. The strategic advantage will favor suppliers that can preserve process control while offering modular architectures adaptable to different chemistry classes and customer development stages.
Flow Chemistry Market Regional Analysis
North America Flow Chemistry Market Analysis
North America generated USD 782 million in 2025 and is projected to reach USD 2.03 billion by 2035. The flow chemistry market in North America benefits from a dense pharmaceutical manufacturing base, established CDMO infrastructure, and a deep research ecosystem. The region's revenue base is increasingly supported by larger integrated platform purchases that combine reactors, analytics, automation, and technical services.
U.S.
The U.S. generated USD 665 million in 2025 and is projected to reach USD 1.72 billion by 2035. Demand is anchored in API manufacturing, CDMO qualification activity, and the commercial translation of research-scale continuous processes. Domestic manufacturing priorities and familiarity with FDA continuous-manufacturing expectations further support equipment investment.
Canada
Canada accounted for approximately 11% of North American revenue in 2025. The country's opportunity is supported by CDMO activity in Ontario and Quebec, established pharmaceutical production, and academic expertise in flow-chemistry development. Demand is concentrated in specialized installations rather than broad-based production conversion.
Mexico
Mexico is at an early adoption stage, with demand concentrated in specialty chemical manufacturing and limited pharmaceutical production. Investment is expected to track broader manufacturing trends through 2035.
Europe Flow Chemistry Market Analysis
Europe generated USD 655 million in 2025 and is projected to represent 29.0% of market revenue by 2035. Europe combines a major pharmaceutical and fine-chemical manufacturing base with longstanding expertise in chemical engineering and flow-reactor development. Sustainability requirements and ICH Q13 alignment are supporting selective replacement of batch capacity with continuous systems.
Germany
Germany generated USD 164 million in 2025 and is projected to reach USD 420 million by 2035. Its chemical-engineering ecosystem and concentration of specialized reactor designers make Germany both a demand center and a technology-development hub. Buyers place particular value on modular plants capable of moving validated routes from pilot work to regulated production.
UK
The UK accounted for an 18.0% share of European revenue in 2025 and is projected to reach USD 302 million by 2035. Pharmaceutical API manufacturing and a mature academic chemistry base underpin demand. The market's specialist workforce and established process-development capability support adoption of modular systems for batch-to-flow conversion.
France
France represented 15.0% of European revenue in 2025. Fine chemicals, pharmaceutical production, and research infrastructure provide a credible base for gradual flow-equipment adoption. Demand is often linked to collaborative process-development work that bridges academic discovery and industrial scale-up.
Italy
Italy's pharmaceutical manufacturers, particularly in the north, represent a core industrial buyer base. Investment has been directed toward specialized flow systems for API synthesis and fine-chemical production.
Spain
Spain's specialty chemical producers are among the regional buyers, with adoption linked to process intensification priorities and product-specific safety requirements.
Asia Pacific Flow Chemistry Market Analysis
Asia Pacific is forecast to grow at a 12.2% CAGR (2026–2035) and reach USD 1.68 billion by 2035. The flow chemistry market in Asia Pacific is being propelled by CDMO capacity expansion, pharmaceutical modernization, and national priorities around advanced manufacturing and green chemistry. The region's growth is tied to both export-oriented pharmaceutical production and the expansion of domestic specialty-chemical capabilities.
China
China held a 40.0% share of Asia Pacific revenue in 2025 and is projected to reach USD 671 million by 2035. Pharmaceutical and specialty-chemical producers are adopting flow equipment for process intensification, yield improvement, and controlled handling of demanding reaction steps. Advanced-manufacturing and green-chemistry priorities provide an additional commercial rationale for investment.
Japan
Japan generated USD 116 million in 2025 and is projected to reach USD 369 million by 2035. Japan combines pharmaceutical manufacturing demand with technical strengths in photochemical and electrochemical reactor development. This supports procurement of higher-specification systems for advanced synthesis and process-development applications.
India
India generated USD 84 million in 2025 and is projected to reach USD 268 million by 2035. Indian CDMOs are strengthening continuous-flow capability as international customers increasingly evaluate specialized process competency during outsourcing decisions. The opportunity is especially meaningful in hazardous chemistry, where controlled flow systems can differentiate manufacturing service offerings.
South Korea
South Korea held a 12.0% share of Asia Pacific revenue in 2025. Demand is shaped by pharmaceutical manufacturing, specialty chemicals, and CDMO operators seeking to serve both domestic and international customers. The market's technical manufacturing base supports adoption of more integrated, application-specific systems.
Australia
Australia's demand is concentrated in research institutions and early-stage pharmaceutical development companies, with adoption patterns reflecting the country's research-led engagement with continuous-flow technology.
Latin America Flow Chemistry Market Analysis
Latin America represented a 4.0% share of global revenue in 2025 and is projected to reach USD 260 million by 2035. The flow chemistry market in Latin America remains at an earlier stage of commercialization, with demand concentrated in pharmaceutical manufacturing, specialty chemicals, and research-led process development. Modular systems provide an entry path for buyers that cannot justify dedicated large-scale continuous plants.
Brazil
Brazil generated USD 46 million in 2025 and is projected to reach USD 143 million by 2035. Brazilian pharmaceutical and fine-chemical producers are the primary purchasers. Compact equipment is particularly relevant where manufacturers want to develop and validate continuous routes before committing to larger dedicated infrastructure.
Argentina
Argentina's pharmaceutical manufacturers, historically active in API production, are beginning to evaluate flow chemistry for productivity improvement and process intensification. Demand is at an early stage relative to Brazil.
Middle East & Africa Flow Chemistry Market Analysis
Middle East & Africa generated USD 63 million in 2025 and is expected to grow at an 8.7% CAGR (2026–2035). The flow chemistry market in Middle East & Africa is constrained by a comparatively limited pharmaceutical and specialty-chemical production base, as well as uneven access to specialized engineering talent. Demand is consequently concentrated in selected industrial, research, and localization initiatives.
Saudi Arabia
Saudi Arabia accounted for 28.0% of Middle East & Africa revenue in 2025. Interest is strongest in specialty chemicals, petrochemical process intensification, and pharmaceutical-manufacturing localization. National industrial-development programmes can support adoption, although broader market expansion will depend on specialist workforce development and sustained project execution.
UAE
The UAE's flow chemistry demand is linked to pharmaceutical manufacturing, academic research, and life sciences-oriented free zone activity. Its positioning as a regional pharma hub is progressively generating infrastructure investment that encompasses continuous manufacturing capability.
South Africa
South Africa's demand centres on specialty chemical production and early interest from generics manufacturers in pharmaceutical synthesis. Broader adoption is at a pre-commercial stage.
GMI Analyst View
We expect regional demand to be determined increasingly by CDMO concentration and manufacturing-policy alignment rather than current market size alone. Asia Pacific has the strongest expansion catalyst, while North America and Europe will remain critical for larger, integrated installations that place a premium on validation capability, analytics, and service depth.
Flow Chemistry Market Share & Competitive Landscape
The flow chemistry market share structure is moderately concentrated, with the top five suppliers collectively holding approximately 38.5% of revenue in 2025.
Competition is shaped by reactor design, application-engineering capability, scale-up support, material compatibility, and post-installation service rather than by unit volume alone. Global suppliers compete for integrated pharmaceutical and specialty-chemical programmes, while regional specialists retain strong positions where customers require process-specific expertise or customized reactor architecture.
Corning Incorporated held approximately 11.5% market share in 2025.
Corning's Advanced-Flow Reactor portfolio spans laboratory through commercial-scale applications, with a positioning centered on glass fluidics, scalable modules, and process-development support. Its ability to link R&D systems with larger manufacturing platforms supports customer continuity during scale-up.
Lonza Group AG held approximately 9.8% market share in 2025.
Lonza differentiates through the combination of technology solutions and CDMO capabilities. That model allows the company to participate in customer decisions spanning equipment selection, process development, and outsourced pharmaceutical manufacturing.
Syrris Ltd. held approximately 7.2% market share in 2025.
Syrris has a strong presence in modular microfluidic systems used for reaction screening and optimization. Its installed base across academic and industrial settings supports recurring demand for accessories, upgrades, and systems that bridge early development and pilot-scale work.
Vapourtec Ltd. competes through modular R-series and E-series systems serving batch-to-flow conversion, pharmaceutical development, and electrochemical synthesis. Its proposition is strongest where users value configurable equipment that can be deployed across changing development programmes.
ThalesNano Inc. is differentiated by hydrogenation and high-pressure flow platforms used in pharmaceutical process development and specialty chemicals. Its technology addresses reaction environments in which controlled pressure and safer handling create a material operational advantage.
Microinnova Engineering GmbH focuses on modular continuous plants for pharmaceutical API and specialty-chemical production. Its commercial position rests on translating laboratory routes into GMP-capable manufacturing infrastructure.
CEM Corporation offers microwave-assisted and continuous-flow platforms for pharmaceutical research and peptide synthesis. Its systems address workflows where accelerated activation and integrated processing can shorten synthetic-development cycles.
Regional champions, including Chemtrix BV, Cambridge Reactor Design Ltd., Ehrfeld Mikrotechnik GmbH, AM Technology, and H.E.L Group, compete through specialized capabilities in scalable reactors, electrochemistry, microstructured equipment, high-pressure operation, and automated process development. Emerging companies such as Flowid B.V., Milestone Srl, Continuus Pharmaceuticals, and Snapdragon Chemistry broaden competition through process intensification, microwave-flow platforms, integrated pharmaceutical manufacturing, and complex-route translation.
Recent Industry Developments
Almac Sciences launched cGMP-compliant high-pressure flow hydrogenation capability in March 2026, extending its API and flow-chemistry service offering toward clinical and commercial manufacturing. The initiative strengthens the availability of specialized continuous hydrogenation capacity for regulated pharmaceutical programmes [4].
Ajinomoto Omnichem and KHIMOD announced the integration of Heat Exchanger-Reactor systems into Ajinomoto Omnichem's continuous-flow platform in July 2026. The partnership extends industrial CDMO capability for modular, multi-step continuous processing in pharmaceutical APIs, green fine chemicals, and specialty ingredients [5].
SK pharmteco introduced its Catalyst Kit in September 2026 as a structured programme for catalyst screening, process optimization, and commercial-scale continuous-manufacturing development. The offering reflects growing supplier emphasis on reducing development friction between early reaction work and qualified production infrastructure [6].
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.