
Doors Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research Approach
1.2 Quality Commitments
1.2.1 GMI AI Policy & Data Integrity Commitment
1.2.1.1 Source Consistency Protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial List of Primary Sources
1.5 Data Mining Sources
1.5.1 Paid Sources
1.5.1.1 Sources, by Region
1.6 Base Estimates & Calculations
1.6.1 Base Year Calculation
1.7 Forecast Model
1.7.1 Quantified Market Impact Analysis
1.7.1.1 Mathematical Impact of Growth Parameters on Forecast
1.8 Research Transparency Addendum
1.8.1 Source Attribution Framework
1.8.2 Quality Assurance Metrics
1.8.3 Our Commitment to Trust
Chapter 2. Executive Summary
2.1 Industry 360° Synopsis
2.2 Key Market Trends
2.2.1 Product Type Trends
2.2.2 Material Trends
2.2.3 Mechanism Trends
2.2.4 Mode of Application Trends
2.2.5 End-User Trends
2.2.6 Regional Trends
2.3 TAM Analysis, 2027–2035
2.4 CXO Perspectives: Strategic Imperatives
Chapter 3. Industry Insights
3.1 Industry Ecosystem Analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost Structure
3.1.4 Value Addition at Each Stage
3.1.5 Factors Affecting the Value Chain
3.1.6 Disruptions
3.2 Industry Impact Forces
3.2.1 Growth Drivers
3.2.1.1 Rising Urbanization & Residential Construction Activity Fueling Volume Demand Across Emerging Markets
3.2.1.2 Stringent Building Energy Codes & Green Building Certifications (LEED, BREEAM) Accelerating Energy-Efficient Door Adoption
3.2.1.3 Growing Smart Home & Commercial Automation Integration Driving Demand for IoT-Enabled & Access-Controlled Door Systems
3.2.1.4 Expanding Fire Safety & Security Compliance Mandates in Commercial, Institutional & Industrial Construction
3.2.2 Industry Pitfalls & Challenges
3.2.2.1 Raw Material Price Volatility (Hardwood, Steel, Aluminum, Glass) Compressing Manufacturer Margins & Creating Pricing Uncertainty
3.2.2.2 Highly Fragmented Market Structure & Intensifying Low-Cost Competition from Asian Manufacturers Eroding Incumbent Pricing Power
3.2.2.3 Trade Tariffs & Import Policy Disruptions Increasing Input Costs & Complicating Cross-Border Supply Chain Management
3.2.3 Market Opportunities
3.2.3.1 Renovation & Replacement Wave in Aging Residential & Commercial Building Stock Across North America & Europe
3.2.3.2 Infrastructure Expansion in Asia Pacific, Middle East & Africa Creating Large-Scale New Construction Demand
3.2.3.3 Sustainable, Recycled & Low-Emission Door Materials Aligning with ESG Mandates & Green Procurement Policies
3.3 Growth Potential Analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis (Driven by Primary Research)
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus) (Driven by Primary Research)
3.5 Regulatory Landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia Pacific
3.5.4 Latin America
3.5.5 Middle East & Africa
3.6 Porter's Analysis
3.7 PESTEL Analysis
3.8 Trade Data Analysis (Paid Database)
3.8.1 Import/Export Volume & Value Trends
3.8.2 Key Trade Corridors & Tariff Impact
3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
3.10 Consumer Behaviour Analysis
3.11 Capacity & Production Landscape (Driven by Primary Research)
3.11.1 Installed Production Capacity by Region & Key Producer (Driven by Primary Research)
3.11.2 Capacity Utilization Rates & Expansion Pipelines (Driven by Primary Research)
3.12 Patent Landscape (Driven by Primary Research)
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company Market Share Analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East & Africa
4.2.2 Market Concentration Analysis
4.3 Competitive Analysis of Major Market Players
4.4 Competitive Positioning Matrix
4.5 Key Developments
4.5.1 Mergers & Acquisitions
4.5.2 Partnerships & Collaborations
4.5.3 New Product Launches
4.5.4 Expansion Plans & Funding
4.6 Company Tier Benchmarking
4.6.1 Tier Classification Criteria & Qualifying Thresholds
4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5. Product Type Market Estimates & Forecast, 2026–2035 (USD Billion) (Million Units)
5.1 Interior Doors
5.1.1 Panel Doors
5.1.2 Flush Doors
5.1.3 Barn/Pocket Doors
5.1.4 French Doors (Interior)
5.1.5 Bifold & Closet Doors
5.1.6 Others
5.2 Exterior Doors
5.2.1 Entry/Front Doors
5.2.2 Patio & French Doors (Exterior)
5.2.3 Storm Doors
5.2.4 Security & Blast-Resistant Doors
5.2.5 Garage & Overhead Doors
5.2.6 Others
Chapter 6. Material Market Estimates & Forecast, 2026–2035 (USD Billion) (Million Units)
6.1 Wood
6.1.1 Solid Wood
6.1.2 Hollow Core Wood
6.1.3 Engineered/Composite Wood (MDF, HDF)
6.2 Metal
6.2.1 Steel
6.2.2 Aluminum
6.2.3 Stainless Steel
6.3 Glass
6.3.1 Tempered Glass
6.3.2 Laminated Glass
6.3.3 Frosted/Decorative Glass
6.4 Fiberglass & Composite
6.4.1 Fiberglass Reinforced Polymer (FRP)
6.4.2 Glass-Reinforced Plastic (GRP)
6.4.3 Hybrid/Multi-Material Composites
6.5 Plastic/PVC
6.5.1 uPVC
6.5.2 PVC-Foam Core
6.6 Others (Emerging Materials)
Chapter 7. Mechanism Market Estimates & Forecast, 2026–2035 (USD Billion) (Million Units)
7.1 Swinging/Hinged Doors
7.1.1 Single Leaf
7.1.2 Double Leaf (French/Double Swing)
7.2 Sliding Doors
7.2.1 Bypass Sliding
7.2.2 Pocket Sliding
7.2.3 Sliding Glass/Patio
7.3 Folding/Bi-fold Doors
7.3.1 Accordion/Multi-Panel Folding
7.3.2 Bi-fold (2-Panel)
7.4 Overhead Doors
7.4.1 Sectional Overhead
7.4.2 Rolling/Roll-Up
7.5 Revolving Doors
7.6 Automatic/Sensor-Operated Doors
7.7 Others
Chapter 8. Mode of Application Market Estimates & Forecast, 2026–2035 (USD Billion) (Million Units)
8.1 New Construction
8.1.1 Residential New Construction
8.1.2 Commercial New Construction
8.1.3 Industrial & Institutional New Construction
8.2 Aftermarket (Renovation & Replacement)
8.2.1 Residential Renovation & Replacement
8.2.2 Commercial Renovation & Retrofitting
8.2.3 Industrial & Institutional Upgrades
Chapter 9. End-User Market Estimates & Forecast, 2026–2035 (USD Billion) (Million Units)
9.1 Residential
9.1.1 Single-Family Homes
9.1.2 Multi-Family/Apartment Buildings
9.1.3 Luxury & High-End Residential
9.2 Commercial
9.2.1 Office Buildings
9.2.2 Retail & Shopping Centers
9.2.3 Hospitality (Hotels, Resorts)
9.2.4 Warehouses & Logistics Centers
9.3 Industrial
9.3.1 Manufacturing Plants
9.3.2 Cold Storage & Food Processing Facilities
9.3.3 Chemical & Hazardous Environment Facilities
9.4 Institutional
9.4.1 Healthcare Facilities (Hospitals, Clinics)
9.4.2 Educational Institutions
9.4.3 Government & Public Infrastructure
9.4.4 Airports & Transportation Hubs
Chapter 10. Regional Market Estimates & Forecast, 2026–2035 (USD Billion) (Million Units)
10.1 North America
10.1.1 U.S.
10.1.2 Canada
10.1.3 Mexico
10.2 Europe
10.2.1 Germany
10.2.2 U.K.
10.2.3 France
10.2.4 Italy
10.2.5 Spain
10.2.6 Rest of Europe
10.3 Asia Pacific
10.3.1 China
10.3.2 India
10.3.3 Japan
10.3.4 South Korea
10.3.5 Australia
10.3.6 Rest of Asia Pacific
10.4 Latin America
10.4.1 Brazil
10.4.2 Argentina
10.4.3 Rest of Latin America
10.5 Middle East & Africa
10.5.1 Saudi Arabia
10.5.2 UAE
10.5.3 South Africa
10.5.4 Rest of Middle East & Africa
Chapter 11. Company Profiles (Driven by Primary Research)
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Avinash Singh. 2026, September. Doors Market 2026-2035 (Report ID: GMI2112). Global Market Insights Inc. Retrieved November 13, 2026, from https://www.gminsights.com/toc/details/doors-market

Doors Market
Get a free sample of this report
Doors Market Size
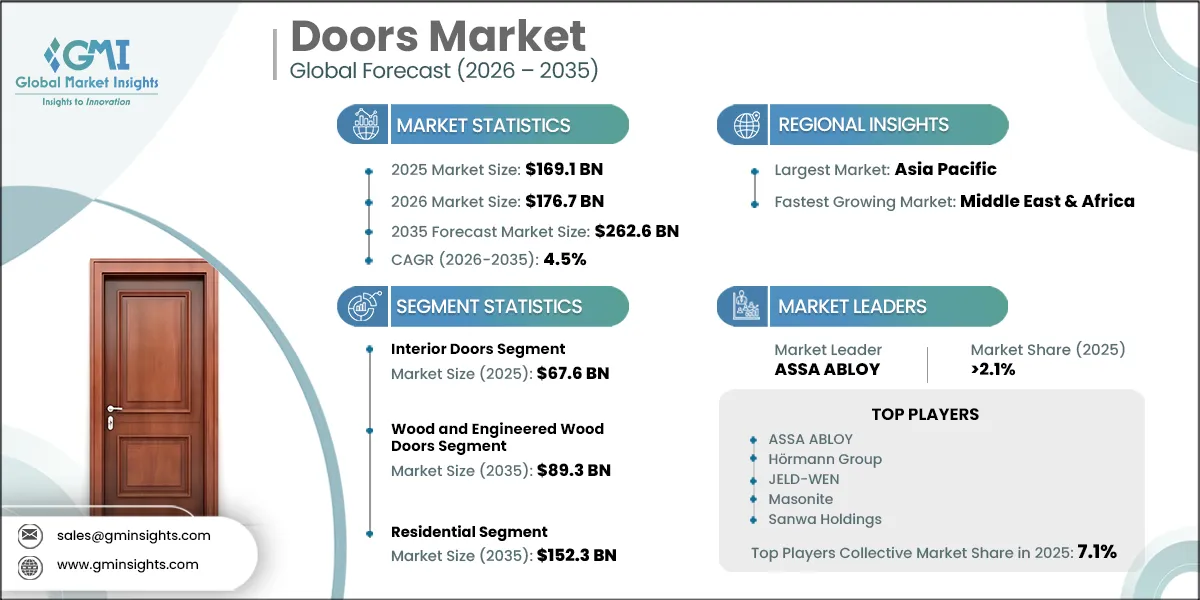
The doors market was valued at USD 169.1 billion in 2025, rising to USD 176.7 billion in 2026, and is projected to expand at a 4.5% CAGR (2026-2035) to reach USD 262.6 billion by 2035.
The doors market encompasses manufacturer-level sales of interior, exterior, industrial, commercial, and specialty door assemblies across residential, commercial, and industrial construction. New construction in urbanizing economies, replacement demand from mature building stock, and compliance-driven upgrades to thermal, fire-safety, acoustic, and access-control specifications shape demand. The market's localized manufacturing and distribution structure means revenue growth remains closely tied to construction activity and the value mix of products specified in each geography.
GMI Analyst View
Based on our review of manufacturer-level revenue data across key geographies, the doors market generated USD 150.3 billion (2022). We view that demand base as evidence of the category's resilience through supply-chain normalization, supported by the essential role of door assemblies in construction, renovation, safety compliance, and building-envelope performance.
Doors Market Trends, Growth Drivers & GMI Forecast Outlook
Urban construction, housing replacement cycles, and tighter requirements for energy performance and life safety are reshaping the doors market. Volume expansion is concentrated in developing urban centers, while mature markets increasingly derive growth from specification upgrades, renovation activity, and higher-value certified assemblies.
Key Drivers
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Urbanization broadens door demand beyond headline housing starts because expanding cities require apartment buildings, mixed-use projects, schools, hospitals, retail premises, and transport-linked commercial facilities. Urban residents represented 45% of the world's 8.2 billion people in 2025, reinforcing the scale of the construction and refurbishment requirement associated with population concentration [1]. In rapidly urbanizing markets, this supports unit demand; in mature cities, redevelopment and conversion projects add a replacement channel.
Regulatory requirements create a separate source of value growth. Thermal-envelope standards, fire-door mandates, acoustic requirements, and access-control integration can move procurement away from basic assemblies toward tested, certified, and engineered systems. The commercial effect is especially material where code compliance, insurance requirements, and institutional procurement standards raise the consequences of product failure or inadequate documentation.
Key Restraints
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Lumber-price swings create a difficult margin environment because manufacturers often negotiate against contractor budgets and distributor price lists that adjust more slowly than input costs. Trade uncertainty, supply disruptions, and changes in sawmill capacity can magnify procurement risk for wood-based products [2]. Producers with narrow material portfolios are more exposed when customers defer premium purchases or select lower-cost alternatives.
Fragmentation also limits the purchasing leverage and logistics efficiency available to many mid-sized manufacturers. Product standards, local installation practices, and country-specific code requirements constrain cross-market standardization. As a result, manufacturers may retain strong local positions while still facing elevated inventory, transport, qualification, and channel-management costs that slow the transmission of cost recovery through the value chain.
GMI Analyst View
We see the forecast as a combination of volume-led and specification-led demand rather than a uniform construction-cycle story. Urbanizing markets depend more directly on project flow and housing affordability, whereas mature markets benefit from replacement and compliance demand. This distinction should make the revenue mix progressively more resilient where certified, higher-performance products gain adoption.
Doors Market Segment Analysis
By Product Type
The doors market interior doors segment was valued at USD 67.6 billion in 2025 and is projected to account for 38.0% of market revenue in 2035. Interior doors remain closely tied to residential construction and refurbishment because each dwelling requires multiple internal openings. Product choice is increasingly influenced by space efficiency, acoustic separation, finish quality, and fire-performance requirements in multifamily and institutional settings, creating scope for value growth even where unit demand is mature.
Exterior doors are projected to generate USD 89.3 billion by 2035 and accounted for 35.0% of the market in 2025. Exterior-door demand benefits from its role in thermal performance, weather protection, security, and architectural appearance. Greater use of sealed frames, insulated cores, glazing systems, and composite or thermally broken materials is shifting purchasing decisions toward products that can satisfy both energy and durability expectations.
Industrial and commercial doors were valued at USD 25.4 billion in 2025 and are expected to expand at a 6.4% CAGR (2026-2035). Warehouses, manufacturing plants, cold-storage facilities, distribution centers, and institutional buildings require high-cycle, sectional, rapid-speed, fire-rated, and access-controlled systems. These applications carry a higher engineering and service content than standard architectural doors, making infrastructure investment and retrofit activity particularly important to the segment's outlook.
Specialty doors are projected to reach USD 26.2 billion by 2035 and represented 10.0% of the market in 2025. Fire-rated, acoustic, security, and other performance-led products address applications where specification compliance is non-negotiable. Demand is reinforced by healthcare, education, government, hospitality, and high-occupancy commercial facilities, where tested performance, documentation, and long product life can outweigh initial purchase-price considerations.
By Material
Wood and engineered wood doors are projected to generate USD 89.3 billion by 2035. Wood remains commercially important in residential interiors and customized architectural applications because of its appearance, workability, and established installation base. However, exterior applications face increasing competition from materials that offer lower maintenance requirements or simpler compliance with thermal-performance specifications.
Steel and metal doors were valued at USD 47.3 billion in 2025 and are projected to hold 27.0% of market revenue in 2035. Steel and metal remain central to commercial, industrial, security, and fire-rated applications. Their strength, durability, and suitability for standardized rated assemblies support continued demand in environments where safety, impact resistance, and long operating cycles determine procurement choices.
uPVC and fiberglass doors are projected to reach USD 57.8 billion by 2035 and are forecast to expand at a 5.5% CAGR (2026-2035). These materials are gaining relevance in exterior residential and light-commercial installations, where moisture resistance, insulation performance, and low maintenance can improve lifecycle value. Their adoption is particularly responsive to regulation and consumer preference for products that reduce upkeep without sacrificing appearance or weather resistance.
Aluminum doors represented 11.0% of global revenue in 2025 and are projected to generate USD 34.1 billion by 2035. Aluminum is well positioned in glazed entrances, commercial facades, premium patio systems, and applications adjacent to curtain-wall construction. Structural capability, corrosion resistance, design flexibility, and compatibility with large-format glazing support its use where architectural integration and long-term appearance are important.
Glass and other materials were valued at USD 6.8 billion in 2025 and are expected to account for 4.0% of market revenue in 2035. This category serves specialized design-led applications, particularly commercial interiors, retail, hospitality, and office partitions. Its demand profile is shaped less by broad construction volume than by fit-out activity, transparency requirements, and demand for differentiated architectural finishes.
By End Use
Residential doors are projected to generate USD 152.3 billion by 2035. Residential demand combines new housing, replacement purchases, remodeling, and homeowner upgrades. The category spans basic local products through premium entry and interior systems, making its commercial profile sensitive to household affordability, renovation incentives, and changing preferences for security, insulation, and design.
Commercial doors accounted for 28.0% of the market in 2025 and are forecast to expand at a 5.2% CAGR (2026-2035). Commercial procurement is increasingly shaped by technical requirements rather than simple opening counts. Healthcare, education, hospitality, offices, retail, and public buildings require combinations of fire resistance, acoustic control, hygiene, access control, and durability that support demand for engineered assemblies and verified performance.
Industrial doors are projected to generate USD 31.5 billion by 2035 and represented 12.0% of market revenue in 2025. Industrial demand is supported by logistics modernization, manufacturing investment, cold-chain capacity, and the need to upgrade older facilities. Operational performance matters as much as the initial installation: high opening cycles, safety protocols, temperature control, and loading-bay integration can favor suppliers with specialized products and service capabilities.
GMI Analyst View
We expect product mix to become more decisive than broad category volume in determining competitive performance. Industrial, commercial, and performance-oriented door systems offer stronger differentiation through engineering, compliance, and service requirements. Material substitution will remain uneven, however, because local affordability, code enforcement, and installer familiarity can delay adoption outside leading markets.
Doors Market Regional Analysis
North America Doors Market Analysis
The doors market in North America was valued at USD 45.7 billion in 2025 and is projected to reach USD 64.0 billion by 2035. North American demand is supported by replacement activity in established housing stock, commercial renovation, and code-led upgrades to fire, thermal, and access-control performance. U.S. construction spending reached USD 2,154.4 billion in 2024, providing a substantial activity base for manufacturers and distributors serving new-build and renovation channels [3].
United States
The United States doors market was valued at USD 40.2 billion in 2025 and is projected to reach USD 56.3 billion by 2035. Residential renovation, single-family construction, institutional projects, and commercial retrofits sustain a broad demand base. The market also rewards suppliers able to satisfy regional code variations, dealer and retail channels, and growing requirements for energy-efficient exterior and rated commercial assemblies.
Canada
Canada represented 12.0% of North American revenue in 2025 and is projected to generate USD 7.7 billion by 2035. Housing replacement demand is important because climate conditions and aging building stock increase the value of durable, insulated products. Major metropolitan construction and institutional investment provide an additional outlet for commercial and specialty door systems.
Europe Doors Market Analysis
Europe was valued at USD 50.7 billion in 2025 and is projected to account for 27.8% of market revenue in 2035. Europe's market is shaped by renovation, energy-performance regulation, and established demand for quality-certified products. European Union construction production increased by approximately 3.0% year-over-year, indicating measured construction activity that can still support replacement and refurbishment demand [4]. National regulation and energy-renovation programs remain particularly influential in the region's product mix.
Germany
Germany was valued at USD 11.2 billion in 2025 and is projected to generate USD 15.8 billion by 2035. The country's manufacturing depth and demanding building-standards environment support domestic consumption of high-specification systems as well as production for wider European markets. Commercial, industrial, and premium residential applications favor suppliers able to demonstrate technical performance and consistent product quality.
United Kingdom
The United Kingdom was valued at USD 8.6 billion in 2025 and is projected to account for 16.7% of European revenue in 2035. Replacement demand and commercial construction remain material sources of door procurement. Fire-door compliance, building-safety requirements, and refurbishment activity support demand for tested products and create an advantage for manufacturers with dependable certification and distribution capabilities.
France
France represented 14.0% of European revenue in 2025 and is projected to generate USD 10.2 billion by 2035. Energy-renovation activity and residential construction support demand for insulated exterior systems, while urban commercial refurbishment creates opportunities for higher-specification products. Public incentives and evolving building-performance requirements can influence the pace and mix of replacement purchases.
Italy
Italy is projected to generate USD 7.3 billion by 2035 and represented 10.1% of European revenue in 2025. An older housing base supports renovation-led demand, while northern industrial areas and design-intensive residential markets add commercial depth. Product aesthetics, customization, and premium finishing remain meaningful differentiators alongside core energy and security requirements.
Asia Pacific Doors Market Analysis
Asia Pacific was valued at USD 55.8 billion in 2025 and is projected to reach USD 96.6 billion by 2035. The region combines large-scale urban development, expanding housing needs, infrastructure investment, and an evolving preference for branded and higher-performance products. Its national markets range from mature, technically demanding systems to high-volume construction environments where price, availability, and local manufacturing remain central to buying decisions.
China
China was valued at USD 22.3 billion in 2025 and is projected to reach USD 40.6 billion by 2035. Urban renewal, modernization of residential stock, and ongoing industrial and logistics investment create multiple demand channels. The gradual tightening of building safety and performance requirements supports a shift toward higher-value assemblies, particularly in high-rise, commercial, and industrial applications.
Japan
Japan was valued at USD 7.3 billion in 2025 and is projected to account for 11.1% of Asia Pacific revenue in 2035. A mature construction market is offset by demand for technically sophisticated replacement products. Seismic, fire-safety, and thermal-performance requirements favor high-quality systems, while aging housing stock supports renovation activity even when new-build conditions are restrained.
India
India represented 12.0% of Asia Pacific revenue in 2025 and is forecast to expand at a 7.8% CAGR (2026-2035). Urbanization, housing programs, infrastructure development, and rising household purchasing power are broadening demand beyond unorganized local production. Branded door systems are gaining relevance in major cities as buyers place greater emphasis on security, finishes, acoustic performance, and more consistent installation quality.
South Korea
South Korea is projected to generate USD 6.3 billion by 2035 and represented 8.1% of Asia Pacific revenue in 2025. The market is supported by high building standards, metropolitan residential construction, and commercial demand for energy-efficient, code-compliant products. Renovation and technical specification requirements provide stability as construction activity moves through normal cyclical variation.
Latin America Doors Market Analysis
Latin America is projected to generate USD 16.5 billion by 2035 and is forecast to expand at a 5.0% CAGR (2026-2035). Urban housing demand, public housing initiatives, and industrial investment support the region's outlook. Market development varies substantially by country, with affordability, financing conditions, and local manufacturing capacity influencing the adoption of higher-specification products.
Brazil
Brazil was valued at USD 5.6 billion in 2025 and is projected to reach USD 9.0 billion by 2035. Housing deficits and social housing activity provide a durable residential demand foundation. Major urban centers also support commercial procurement, where specification needs for security, fire performance, and durability can lift demand for more advanced products.
Mexico
Mexico represented 27.7% of Latin American revenue in 2025 and is forecast to expand at a 5.1% CAGR (2026-2035). Nearshoring-related manufacturing and logistics investment adds an industrial demand channel alongside residential construction. Northern industrial corridors are particularly relevant for suppliers of sectional, loading-bay, security, and high-cycle systems.
Middle East & Africa Doors Market Analysis
The Middle East & Africa doors market was valued at USD 6.8 billion in 2025 and is forecast to expand at a 6.3% CAGR (2026-2035). Large construction programs in Gulf markets and continued urban development across Africa support growth from a comparatively smaller base. Demand is diversified across residential, hospitality, infrastructure, commercial, and institutional projects, with international project standards increasing the need for documented technical performance in major developments.
Saudi Arabia
Saudi Arabia was valued at USD 1.5 billion in 2025 and is forecast to expand at a 7.2% CAGR (2026-2035). Major development activity across hospitality, entertainment, residential, and infrastructure projects is creating demand for commercial and institutional door systems. International design and procurement standards on large projects can increase requirements for fire resistance, access control, architectural finishes, and reliable installation support.
UAE
The UAE is projected to generate USD 2.4 billion by 2035 and represented 17.6% of Middle East & Africa revenue in 2025. Commercial, hospitality, and premium residential projects support demand for visually differentiated, durable, and technically compliant systems. Renovation activity also matters in a competitive real-estate environment where property owners seek to maintain building quality and occupant appeal.
South Africa
South Africa was valued at USD 800 million in 2025 and is projected to reach USD 1.3 billion by 2035. The market combines formal demand for specification-grade products in major commercial and industrial centers with broad residential demand at varied price points. This dual structure requires suppliers to balance premium compliance-led offerings with products suited to affordability-sensitive construction channels.
GMI Analyst View
We view Asia Pacific and the Middle East & Africa as the principal engines of incremental demand, although their growth mechanisms differ. Asia Pacific combines scale with a gradual rise in product sophistication, while Middle East & Africa benefits from project-led procurement. Europe and North America remain strategically important for replacement demand and value-rich compliance upgrades.
Doors Market Share & Competitive Landscape
The doors market share structure is highly fragmented, with the five largest companies collectively accounting for approximately 7.1% of global revenue in 2025. Local building codes, material preferences, installer practices, and regionally embedded distribution networks constrain standardization and preserve the importance of national and local manufacturers. Competition therefore extends beyond production scale to certification, channel reach, service responsiveness, product breadth, and the ability to tailor offerings to local specifications.
ASSA ABLOY held a 2.1% share of the market in 2025. Its position is reinforced by a portfolio spanning access solutions, entrance systems, automatic doors, and industrial applications. The company's acquisition strategy and broad geographic operating base support its ability to deepen technical capability in categories where integrated opening solutions and aftermarket service are increasingly relevant.
Hormann Group held a 1.4% share of the market in 2025. The company's strength in garage, industrial, fire-rated, sectional, and commercial systems positions it well in applications linked to logistics infrastructure and building-performance requirements. Its vertically integrated approach also supports product consistency across technically demanding categories.
JELD-WEN held a 1.2% share of the market in 2025. Its residential and light-commercial portfolio provides exposure to replacement, renovation, retail, and contractor channels in North America and Europe. Portfolio discipline and operating efficiency remain particularly important in a market where regional brands, channel relationships, and product availability can shape competitive outcomes.
Masonite International Corporation, within Owens Corning's doors business, remains focused on North American residential interior and exterior categories. The combined platform can leverage established product brands and retail relationships, while its competitive position depends on translating broader building-products capabilities into a differentiated offering for contractors, distributors, and homeowners.
Sanwa Holdings Corporation is positioned in industrial and commercial doors, shutters, and partitions, particularly across Asia Pacific. Its exposure to high-cycle and specialized systems aligns with demand from manufacturing, logistics, and commercial construction, where operating reliability and specification compliance can be more important than lowest-cost procurement.
Recent Industry Developments
In October 2025, ASSA ABLOY acquired Metal Products Inc., a U.S. manufacturer of custom hollow metal doors and frames. The acquired business generated approximately USD 22 million in 2024 revenue and employed approximately 170 people. The transaction strengthens ASSA ABLOY's commercial and institutional offering in the United States, where regional production proximity and delivery reliability are meaningful differentiators for rated assemblies.
In November 2025, JELD-WEN announced a strategic review of its Europe business, which generated USD 1.1 billion in 2024 revenue, approximately 28% of the company's global revenue. The business operates 23 manufacturing locations and employs approximately 6,000 people, making the review potentially consequential for European manufacturing ownership, portfolio strategy, and channel relationships.
In June 2025, ASSA ABLOY acquired Kingspan Door Components, a Belgian manufacturer of sectional-door panels. The acquisition expands component depth within the company's Entrance Systems portfolio and supports its presence in European industrial and residential sectional-door applications.
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.