
Data Center Cooling Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research approach
1.2 Quality Commitments
1.2.1 GMI AI policy & data integrity commitment
1.2.1.1 Source consistency protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial list of primary sources
1.5 Data mining sources
1.5.1 Paid sources
1.5.1.1 Sources, by region
1.6 Base estimates and calculations
1.6.1 Base year calculation for any one approach
1.7 Forecast model
1.7.1 Quantified market impact analysis
1.7.1.1 Mathematical impact of growth parameters on forecast
1.8 Research transparency addendum
1.8.1 Source attribution framework
1.8.2 Quality assurance metrics
1.8.3 Our commitment to trust
Chapter 2. Executive Summary
2.1 Industry 360° synopsis, 2022 – 2035
2.2 Key market trends
2.2.1 Regional
2.2.2 Component
2.2.3 Cooling Technique
2.2.4 Data Center Size
2.2.5 Application
2.2.6 Data Center
2.3 TAM Analysis, 2027-2035
2.4 CXO perspectives: Strategic imperatives
2.4.1 Executive decision points
2.4.2 Critical success factors
2.5 Future outlook and strategic recommendations
Chapter 3. Industry Insights
3.1 Industry ecosystem analysis
3.1.1 Supplier landscape
3.1.2 Profit margin analysis
3.1.3 Cost structure
3.1.4 Value addition at each stage
3.1.5 Factor affecting the value chain
3.1.6 Disruptions
3.2 Industry impact forces
3.2.1 Growth drivers
3.2.1.1 Rising data center capacity and increasing IT power density
3.2.1.2 Growing adoption of AI and high-performance computing infrastructure
3.2.1.3 Increasing demand for energy-efficient and sustainable cooling solutions
3.2.1.4 Expansion of hyperscale, colocation, cloud, and edge data centers
3.2.2 Industry pitfalls and challenges
3.2.2.1 High initial investment and installation costs
3.2.2.2 High energy and water consumption of conventional cooling systems
3.2.3 Market opportunities
3.2.3.1 Growing adoption of direct-to-chip and immersion liquid cooling
3.2.3.2 Increasing deployment of modular and prefabricated data centers
3.2.3.3 Rising demand for AI-optimized high-density cooling infrastructure
3.3 Growth potential analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
3.5 Regulatory landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia-Pacific
3.5.4 Latin America
3.5.5 Middle East and Africa
3.6 Porter’s analysis
3.7 PESTEL analysis
3.8 Trade Data Analysis (Driven by Paid Database)
3.8.1 Import/Export volume & value trends
3.8.2 Key trade corridors & Tariff Impact
3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
3.10 Data center capacity & infrastructure landscape
3.10.1 Installed capacity (MW) by country, 2022-2026
3.10.2 Expansion pipeline 2027-2030
3.10.3 Utilization rates & supply-demand
3.11 Patent Analysis
3.12 Technology & Innovation Landscape
3.12.1 Current Technology Trends
3.12.2 Emerging Technology Trends
3.12.3 Cost Breakdown Analysis, 2025
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company market share analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia Pacific
4.2.1.4 LATAM
4.2.1.5 MEA
4.2.2 Market Concentration Analysis
4.3 Competitive analysis of major market players
4.4 Competitive positioning matrix
4.5 Strategic outlook matrix
4.6 Key developments
4.6.1 Mergers & acquisitions
4.6.2 Partnerships & collaborations
4.6.3 New Product Launches
4.6.4 Expansion Plans and funding
Chapter 5. Market Estimates & Forecast, By Component, 2022 - 2035 (USD Mn, Units)
5.1 Key trends
5.2 Solution
5.2.1 Air conditioner
5.2.1.1 Air handling units
5.2.1.2 Split air conditioning systems
5.2.1.3 Packaged air conditioning units (PAC)
5.2.1.4 Others
5.2.2 Chilling unit
5.2.2.1 Air-cooled chillers
5.2.2.2 Water-cooled chillers
5.2.2.3 Glycol-cooled chillers
5.2.3 Cooling tower
5.2.3.1 Evaporative cooling
5.2.3.2 Dry
5.2.3.3 Others
5.2.4 Control system
5.2.4.1 Economizer system
5.2.4.2 Condensing
5.2.4.3 Non-condensing
5.2.5 Liquid cooling system
5.2.5.1 Direct to chip
5.2.5.2 Immersive
5.2.5.2.1 Single phase
5.2.5.2.2 Two phase
5.2.6 Others
5.3 Service
5.3.1 Consulting
5.3.2 Maintenance and support
5.3.3 Installation and deployment
Chapter 6. Market Estimates & Forecast, By Cooling Technique, 2022 - 2035 (USD Mn, Units)
6.1 Key trends
6.2 Rack/row based
6.3 Room based
Chapter 7. Market Estimates & Forecast, By Data Center Size, 2022 - 2035 (USD Mn, Units)
7.1 Key trends
7.2 Small data center
7.3 Medium data center
7.4 Large data center
Chapter 8. Market Estimates & Forecast, By Application, 2022 - 2035 (USD Mn, Units)
8.1 Key trends
8.2 BFSI
8.3 Colocation
8.4 Energy
8.5 Government
8.6 Healthcare
8.7 Manufacturing
8.8 IT & Telecom
8.9 Others
Chapter 9. Market Estimates & Forecast, By Data Center, 2022 - 2035 (USD Mn, Units)
9.1 Key trends
9.2 Hyperscale
9.3 Colocation
9.4 Enterprise
9.5 Edge
9.6 Cloud
Chapter 10. Market Estimates & Forecast, By Region, 2022 - 2035 (USD Mn, Units)
10.1 Key trends
10.2 North America
10.2.1 US
10.2.2 Canada
10.3 Europe
10.3.1 Germany
10.3.2 UK
10.3.3 France
10.3.4 Italy
10.3.5 Spain
10.3.6 Russia
10.3.7 Norway
10.3.8 Netherlands
10.3.9 Sweden
10.4 Asia Pacific
10.4.1 China
10.4.2 India
10.4.3 Japan
10.4.4 Australia
10.4.5 South Korea
10.4.6 Singapore
10.4.7 Thailand
10.4.8 Indonesia
10.4.9 Vietnam
10.5 Latin America
10.5.1 Brazil
10.5.2 Mexico
10.5.3 Argentina
10.6 MEA
10.6.1 South Africa
10.6.2 Saudi Arabia
10.6.3 UAE
10.6.4 Turkey
Chapter 11. Company Profiles
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Preeti Wadhwani. 2026, September. Data Center Cooling Market Size, By Component, By Cooling Technique, By Application, By Data Center Size, By Data Center Growth Forecast, 2025 - 2034 (Report ID: GMI423). Global Market Insights Inc. Retrieved November 2, 2026, from https://www.gminsights.com/toc/details/data-center-cooling-market

Data Center Cooling Market
Get a free sample of this report
Data Center Cooling Market Size
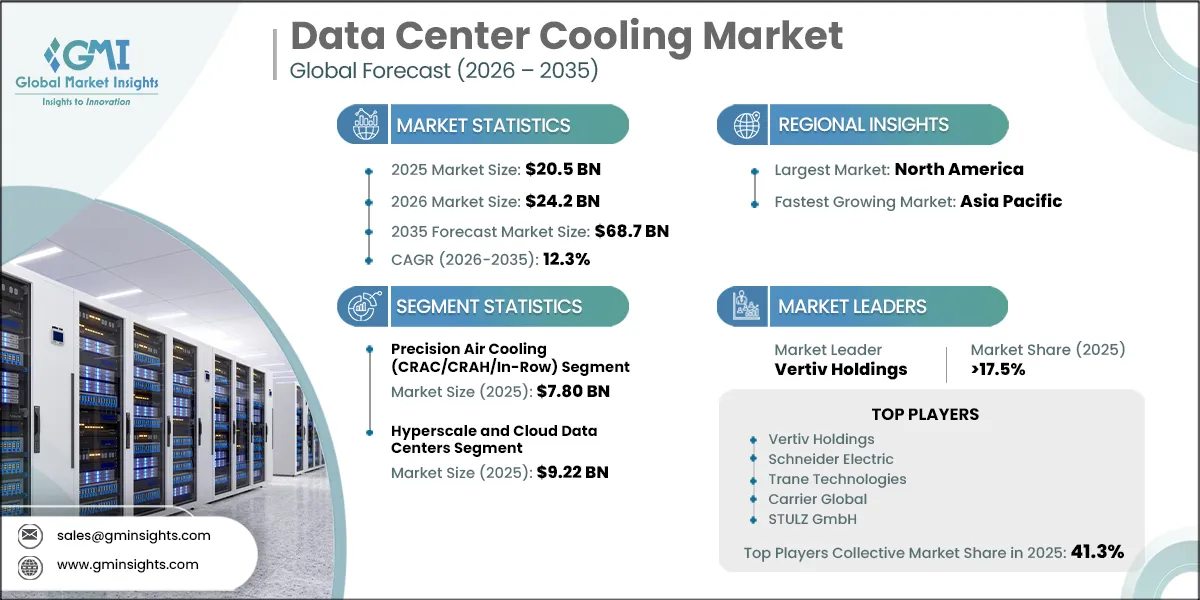
The global data center cooling market was valued at USD 20.5 billion in 2025, is expected to reach USD 24.2 billion in 2026, and is projected to expand at a 12.3% CAGR from 2026 to 2035, reaching USD 68.7 billion by 2035. The market encompasses purpose-built thermal management equipment and integrated hardware systems that regulate temperature, humidity, airflow, and heat rejection in data center facilities.
The Global Data Center Cooling Market is being reshaped by the move from conventional enterprise computing toward high-density AI training and inference deployments. This transition changes cooling from a supporting facility utility into a core design constraint, favoring engineered liquid systems, higher-capacity heat-rejection equipment, integrated controls, and service models capable of maintaining thermal reliability across increasingly complex facility architectures.
GMI Analyst View
Our tracking of global cooling equipment shipments, validated through direct engagement with equipment manufacturers and facility procurement teams, indicates that physical data center cooling equipment units delivered to operators globally are projected to approach approximately 930,000 units annually by 2035. We view this as evidence that revenue expansion rests on broad procurement growth as well as the higher system value associated with engineered cooling architectures.
Data Center Cooling Market Trends, Growth Drivers & GMI Forecast Outlook
AI rack density is accelerating the transition toward liquid and hybrid cooling, but water availability, grid constraints, permitting requirements, and retrofit complexity will determine where and when projects translate into equipment orders. The forecast therefore reflects strong structural demand alongside uneven project conversion across geographies and facility types.
Key Drivers
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Thermal design limits are becoming a direct procurement trigger for AI-capable facilities. As accelerator density rises, operators must manage heat closer to the chip and transport it through more controlled fluid systems, which increases the strategic role of CDUs, rear-door heat exchangers, immersion systems, facility chillers, and heat-rejection equipment. Dell'Oro identifies liquid cooling as moving from a specialized deployment toward a foundational requirement for AI-focused data center capacity [1].
The installed base also changes the quality of market demand. Every additional commissioned cooling system creates requirements for control integration, condition monitoring, preventive maintenance, fluid management, and emergency-response capability. This attachment opportunity is especially consequential where liquid systems raise the operational consequences of inadequate thermal oversight.
Interface standardization is reducing one of the principal barriers to liquid-cooling adoption: project-specific integration risk. More consistent mechanical and coolant-loop requirements enable operators, server providers, and cooling suppliers to shorten qualification cycles. The resulting shift should widen liquid-cooling adoption beyond the earliest hyperscale deployments, although mainstream colocation and enterprise uptake will remain conditioned by facility readiness and service availability.
Key Restraints
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
Regulatory complexity can delay the point at which committed data center investment becomes an executable construction program. State requirements concerning water use, energy disclosure, siting, and infrastructure costs vary materially, increasing diligence requirements for operators with multi-market expansion plans. WilmerHale reported that more than 40 data center-focused state bills introduced during 2025 became law, underscoring the breadth of the emerging compliance burden [2].
The California framework illustrates how utility and water obligations can alter project economics. Requirements for operators to address infrastructure impacts can raise upfront capital needs and redirect development toward locations with more predictable approvals, lower water exposure, or more favorable power arrangements. The state's action also increases the importance of cooling designs that reduce water dependency and support transparent operating performance [3].
Retrofit constraints remain a distinct limitation from technology demand. Older air-cooled facilities may lack the structural capacity, piping routes, leak-detection systems, isolation capability, and maintenance access required for liquid cooling. Consequently, the most rapid adoption is likely to remain concentrated in greenfield hyperscale and purpose-built colocation projects, while legacy facilities extend the life of existing precision-air equipment.
*Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.*
GMI Analyst View
We believe the strongest feature of the outlook is that AI-related cooling demand is rooted in physical operating requirements rather than discretionary preference. The principal execution risk is timing: equipment demand may be committed before permitting, utility interconnection, specialized manufacturing capacity, and construction schedules permit revenue recognition. This makes backlog conversion and project sequencing as important as demand visibility.
Data Center Cooling Market Segment Analysis
By Product Type
The Global Data Center Cooling Market is shifting from equipment categories designed primarily for room-level air management toward systems that manage heat through the full facility chain, from the rack and coolant loop to central plant and heat rejection.
Precision Air Cooling (CRAC/CRAH/In-Row)
Precision air cooling generated USD 7.80 billion in 2025 and is projected to account for 25.0% of market revenue by 2035. The category remains essential in moderate-density environments, legacy enterprise estates, and mixed-technology halls. Its strategic role is changing, however, as advanced facilities reserve air systems for lower-density zones while deploying liquid solutions for AI infrastructure. Suppliers with large precision-air installed bases retain a service advantage, but future differentiation will depend on hybrid configurations and retrofit pathways.
Chillers (Air-Cooled & Water-Cooled)
Chillers are projected to reach USD 12.36 billion by 2035, expanding at an 11.1% CAGR (2026-2035).
Chiller demand benefits from the upstream facility requirements created by liquid cooling. Direct-to-chip and immersion architectures still require dependable heat transfer and rejection beyond the rack, positioning chillers as a durable part of both conventional and advanced thermal designs. Equipment selection will increasingly favor efficiency, higher-temperature operation, modularity, and compatibility with heat-reuse strategies.
Liquid Cooling (CDU/Immersion/DLC)
Liquid cooling represented 17.1% of market revenue in 2025 and is projected to reach USD 22.67 billion by 2035.
Liquid cooling is the central technology transition within the market because it addresses heat loads that room-level air systems cannot manage economically or reliably. The segment's value proposition extends beyond thermal capacity: it can enable denser compute deployment, more controlled operating conditions, and more flexible facility designs. Vendor competition is therefore moving toward engineering depth, deployment capability, coolant management, and lifecycle support.
Cooling Towers & Dry Coolers
Cooling towers and dry coolers generated USD 2.30 billion in 2025 and are expected to grow at an 11.0% CAGR (2026-2035).
These systems are critical to facility-level heat rejection and are increasingly shaped by local water availability, ambient climate, and operating-cost constraints. In water-stressed locations, dry and adiabatic alternatives can gain preference despite their different capital and energy profiles. The category's growth is tied not only to new data center capacity but also to the need to redesign heat-rejection systems around denser computing environments.
Controls & BMS Systems
Controls and BMS systems are projected to account for 7.0% of market revenue by 2035 and to expand at a 12.4% CAGR (2026-2035).
Controls become more valuable as operators run legacy air-cooled zones alongside liquid-cooled AI deployments. Integrated hardware can improve visibility across temperature, airflow, coolant distribution, and equipment performance while reducing the risk of localized thermal events. The segment is positioned to benefit from demand for coordinated operation across increasingly heterogeneous cooling estates.
Services & Aftermarket
Services and aftermarket activity is projected to reach USD 4.80 billion by 2035 and accounted for 6.8% of market revenue in 2025.
The service opportunity expands with the installed base and with the complexity of deployed systems. Liquid cooling introduces operational requirements around fluid quality, leak management, component reliability, and technician capability, supporting deeper vendor relationships after installation. For equipment providers, this creates a more recurring revenue stream that can moderate exposure to project-based capital-equipment cycles.
By End Use
Hyperscale/Cloud Data Centers
Hyperscale and cloud data centers generated USD 9.22 billion in 2025 and are projected to represent 53.0% of market revenue by 2035. Hyperscale operators set the technology direction for cooling because their facility scale, AI concentration, and procurement sophistication allow them to adopt new thermal architectures ahead of the broader market. Their multiyear construction pipelines also favor suppliers able to provide globally consistent engineering, manufacturing capacity, commissioning support, and service coverage.
Colocation Data Centers
Colocation data centers are projected to reach USD 15.11 billion by 2035, growing at a 10.8% CAGR (2026-2035).
Colocation providers must reconcile the requirements of high-density AI tenants with the flexibility needed to serve a varied customer base. This makes modular designs, phased investment, and mixed cooling configurations commercially important. Providers that can offer liquid-ready capacity without compromising tenant choice are likely to influence equipment specifications across metropolitan data center clusters.
Enterprise Data Centers
Enterprise data centers accounted for 20.0% of market revenue in 2025 and are projected to account for 14.0% by 2035.
The declining share reflects continued migration of workloads toward cloud and colocation environments, along with consolidation of remaining on-premises estates. Cooling demand will persist through replacement, reliability upgrades, and selective modernization, but large-scale greenfield investment is less central than in hyperscale and colocation markets. Retrofit feasibility will continue to determine the pace of liquid-cooling adoption.
Edge Computing Data Centers
Edge computing data centers are expected to grow at a 15.0% CAGR (2026-2035) and reach USD 5.49 billion by 2035.
Edge deployments create a different cooling requirement from centralized AI campuses: smaller footprints, distributed locations, varied climate conditions, and limited on-site technical support. This supports demand for compact, resilient, modular systems that can be rapidly installed and remotely monitored. Cooling suppliers that combine standardized products with strong local service capacity are well positioned in this segment.
GMI Analyst View
We see the segment transition as a bifurcation rather than a simple technology replacement. Mature air-based equipment will remain commercially important across legacy and moderate-density facilities, while liquid cooling becomes an engineered systems business defined by integration capability, manufacturing discipline, and service depth. The most durable value pool is likely to sit with suppliers able to bridge both operating models.
Data Center Cooling Market Regional Analysis
North America Data Center Cooling Market Analysis
North America generated USD 8.82 billion in 2025 and is projected to reach USD 26.10 billion by 2035. The Data Center Cooling Market in North America is supported by the concentration of hyperscale campuses, AI infrastructure investment, mature colocation ecosystems, and a deep supplier base. Advanced cooling adoption is progressing rapidly in major U.S. data center markets, although permitting, water, power, and infrastructure-cost considerations are creating meaningful variation between locations. Demand increasingly favors providers that can integrate facility heat rejection, liquid systems, controls, and services.
United States
The United States generated USD 7.99 billion in 2025 and is projected to reach USD 23.70 billion by 2035. The country's scale reflects its concentration of global cloud platforms, AI training capacity, and high-density colocation development. Cooling procurement is increasingly linked to campus-scale construction programs and specialized AI deployments rather than stand-alone equipment replacement. Regulatory divergence between states adds complexity to site selection and can influence the balance between water-intensive and low-water cooling technologies.
Europe Data Center Cooling Market Analysis
Europe generated USD 4.51 billion in 2025 and is expected to grow at an 11.3% CAGR (2026-2035). European demand is shaped by cloud expansion, modernization of established enterprise capacity, and increasingly stringent sustainability requirements. Energy efficiency, heat reuse, water management, and reporting expectations affect equipment specifications and elevate the role of controls, efficient chillers, dry cooling, and higher-temperature heat-rejection designs. This environment favors suppliers that can demonstrate both thermal performance and compliance capability.
United Kingdom
The United Kingdom is projected to reach USD 3.02 billion by 2035, compared with USD 1.08 billion in 2025. London's established connectivity ecosystem and the surrounding hyperscale and colocation corridors sustain equipment demand. AI-related densification is increasing interest in liquid distribution infrastructure, while the installed base continues to support demand for conventional air and chiller solutions. The market's maturity makes deployment speed, availability of skilled service support, and compatibility with existing facilities particularly important.
Germany
Germany accounted for 4.4% of market revenue in 2025 and is projected to expand at an 11.9% CAGR (2026-2035). Germany combines major colocation capacity, industrial AI investment, and high energy-efficiency expectations. Frankfurt remains a critical connectivity and cloud-access hub, while national and European sustainability priorities influence cooling-system selection. Demand is likely to favor architectures that support efficient heat rejection, facilitate heat reuse, and offer reliable performance under tighter environmental requirements.
Asia Pacific Data Center Cooling Market Analysis
Asia Pacific generated USD 5.33 billion in 2025 and is projected to grow at a 13.9% CAGR (2026-2035). The Data Center Cooling Market in Asia Pacific is driven by large-scale cloud expansion, national digital-infrastructure initiatives, AI deployment, and favorable opportunities for greenfield construction. The region's diversity creates a broad set of cooling requirements, ranging from high-temperature and water-constrained environments to mature markets focused on densifying established data center estates. This supports demand across liquid, air, chiller, dry-cooling, and controls technologies.
China
China is projected to reach USD 4.68 billion by 2035, compared with USD 1.33 billion in 2025. Domestic cloud expansion and national data center development programs are supporting substantial cooling investment. Efficiency requirements and the scale of new facilities encourage adoption of high-performance cooling configurations, particularly where operators are building AI-capable capacity. The market's size also supports a broad domestic supplier ecosystem, increasing competitive pressure on global vendors.
India
India is projected to reach USD 3.40 billion by 2035 and expand at an 18.0% CAGR (2026-2035). India's growth reflects data localization, hyperscaler campus investment, domestic digital demand, and a large pipeline of greenfield data center projects. High ambient temperatures in key development markets heighten the operational importance of cooling efficiency and resilience. Because much of the infrastructure is being designed from the ground up, operators have a greater opportunity to specify liquid-ready and water-conscious systems at the initial design stage.
Latin America Data Center Cooling Market Analysis
Latin America generated USD 1.02 billion in 2025 and is projected to reach USD 4.12 billion by 2035. The region is benefiting from growing cloud adoption, hyperscaler expansion, digitalization initiatives, and the relatively low starting point of data center capacity. Brazil and Mexico are central demand centers, while climate conditions, grid reliability, and local service availability shape product selection. Equipment suppliers that can deliver robust systems suited to diverse operating conditions are positioned to capture emerging project pipelines.
Brazil
Brazil generated USD 513 million in 2025 and is projected to grow at a 14.6% CAGR (2026-2035). Brazil's large digital economy, concentration of infrastructure around São Paulo, and expanding cloud investment base make it the region's principal cooling market. The country's power economics and large enterprise demand base support both hyperscale and enterprise-oriented projects. Cooling suppliers must balance high-capacity requirements with site-specific humidity, water, and reliability considerations.
Middle East & Africa Data Center Cooling Market Analysis
The Middle East and Africa generated USD 815 million in 2025 and are projected to reach USD 3.44 billion by 2035. Sovereign digital-infrastructure programs, regional cloud investment, and AI ambitions are expanding the market across the Gulf and selected African locations. Extreme ambient temperatures create a structurally demanding operating environment, raising the importance of efficient heat rejection, water stewardship, and equipment reliability. Greenfield development provides an opportunity to deploy advanced cooling architectures without the retrofit limitations found in older facilities.
Saudi Arabia
Saudi Arabia generated USD 163 million in 2025 and is projected to advance at a 17.4% CAGR (2026-2035). The country's digital-economy strategy and AI infrastructure ambitions are supporting new data center development. Cooling systems must address exceptionally high ambient temperatures while managing water use and operating costs, reinforcing demand for high-efficiency dry and adiabatic approaches. Large-scale greenfield projects give vendors an opening to establish long-term positions through early design engagement and service partnerships.
UAE
The UAE generated USD 163 million in 2025 and is projected to reach USD 688 million by 2035. Dubai and Abu Dhabi continue to attract hyperscale, sovereign-cloud, and AI-computing investment. Cooling efficiency is central to project economics because of high ambient conditions and water considerations, while the market's strategic position attracts suppliers seeking reference deployments in the GCC. Demand is likely to reward technologies that combine thermal performance with monitoring, water management, and operational resilience.
GMI Analyst View
We view regional diversification as an important stabilizer for supplier demand. Mature markets are managing the conversion of installed infrastructure, while greenfield regions can adopt liquid-ready thermal designs at the outset. This creates different procurement cycles, customer requirements, and technical specifications across geographies, rewarding vendors with flexible portfolios and localized execution capability.
Data Center Cooling Market Share & Competitive Landscape
The Global Data Center Cooling Market share structure is moderately concentrated with Vertiv, Schneider Electric, Trane Technologies, Carrier Global, and STULZ GmbH accounting for 41.3% of market revenue in 2025. Competition remains broad because cooling procurement spans precision air, liquid systems, chillers, heat rejection, controls, service, and geographically specific delivery capabilities. Consolidation is intensifying as industrial suppliers seek to expand their positions in liquid cooling and broader thermal-management chains.
Vertiv Holdings
Vertiv held a 17.5% market share in 2025. Vertiv's competitive position is supported by a broad thermal-management portfolio and its ability to address both legacy precision-air demand and advanced liquid-cooling deployments. Its scale, installed base, and systems capability make it a key participant in hyperscale and colocation projects where customers increasingly seek integrated cooling infrastructure rather than isolated components.
Schneider Electric
Schneider Electric held a 16.2% market share in 2025. Schneider Electric competes through a systems approach that connects cooling, power, and data center infrastructure management. This positioning is particularly relevant where operators need coordinated visibility across mixed cooling environments. Its ability to link thermal equipment with broader facility management requirements supports differentiation in complex, high-availability deployments.
Trane Technologies
Trane Technologies held a 3.1% market share in 2025. Trane's strategic opportunity lies in extending its established chiller and facility-cooling capabilities into more specialized data center thermal applications. The company's position is strengthened when customers require continuity between central plant equipment, heat rejection, controls, and liquid-cooling infrastructure, especially in large AI-oriented developments.
STULZ GmbH
STULZ maintains a specialist position in data center climate management, particularly in precision-air and in-row cooling applications. Its customer proximity and focused product expertise remain valuable in enterprise and colocation settings, where facility conditions and retrofit constraints often require tailored solutions. The company's strategic challenge is to extend this expertise into hybrid and liquid architectures without compromising the installed-base advantages that underpin its established market presence.
Others
The remaining competitive tier includes established HVAC participants, regional specialists, and emerging liquid-cooling providers. These companies compete through technical specialization, regional service reach, modular products, water-efficient designs, and differentiated approaches to direct-to-chip or immersion cooling. As the market shifts toward integrated thermal systems, partnerships, acquisitions, manufacturing capacity, and qualification credibility are becoming increasingly important competitive levers.
Recent Industry Developments
Ecolab Acquires CoolIT Systems
Ecolab announced an agreement to acquire CoolIT Systems for approximately USD 4.75 billion. The transaction combines liquid-cooling hardware with Ecolab's capabilities in water, fluid, monitoring, and global service, illustrating the strategic convergence of cooling technology and fluid-management expertise in AI data center infrastructure [4].
Trane Technologies Acquires LiquidStack
Trane Technologies announced an agreement to acquire LiquidStack, expanding its coverage from facility-level thermal infrastructure into direct-to-chip and immersion cooling. The transaction reinforces the commercial value of offering a more complete thermal-management chain for high-density data center deployments [5].
Vertiv Acquires ThermoKey
Vertiv announced an agreement to acquire ThermoKey, expanding its heat-rejection and heat-exchange capabilities. The acquisition signals continued supplier investment in the infrastructure required to support liquid-cooled data center architectures, particularly across European markets [6].
SLB Acquires Kelvion
SLB announced an agreement to acquire Kelvion for approximately USD 4.1 billion, extending its data center infrastructure role through heat-exchange and thermal-management capabilities. The transaction demonstrates the growing strategic importance of thermal infrastructure to companies entering the data center value chain [7].
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.