
Cosmetic Oil Market Size & Share 2026-2035
Download Free PDF
Report Content
Chapter 1. Research Methodology
1.1 Research Approach
1.2 Quality Commitments
1.2.1 GMI AI Policy & Data Integrity Commitment
1.2.1.1 Source Consistency Protocol
1.3 Research Trail & Confidence Scoring
1.3.1 Research Trail Components
1.3.2 Scoring Components
1.4 Data Collection
1.4.1 Partial List of Primary Sources
1.5 Data Mining Sources
1.5.1 Paid Sources
1.5.1.1 Sources, By Region
1.6 Base Estimates & Calculations
1.6.1 Base Year Calculation
1.7 Forecast Model
1.7.1 Quantified Market Impact Analysis
1.7.1.1 Mathematical Impact of Growth Parameters on Forecast
1.8 Research Transparency Addendum
1.8.1 Source Attribution Framework
1.8.2 Quality Assurance Metrics
1.8.3 Our Commitment to Trust
Chapter 2. Executive Summary
2.1 Industry 360° Synopsis
2.2 Key Market Trends
2.2.1 Oil Type Trends
2.2.2 Nature Trends
2.2.3 Application Trends
2.2.4 Distribution Channel
2.2.5 Regional Trends
2.3 TAM analysis, 2027-2035 (USD Billion)
2.4 CXO Perspectives: Strategic Imperatives
Chapter 3. Industry Insights
3.1 Industry Ecosystem Analysis
3.1.1 Supplier Landscape
3.1.2 Profit Margin
3.1.3 Cost Structure
3.1.4 Value Addition at Each Stage
3.1.5 Factors Affecting the Value Chain
3.1.6 Disruptions
3.2 Industry Impact Forces
3.2.1 Growth Drivers
3.2.2 Industry Pitfalls & Challenges
3.2.3 Market Opportunities
3.3 Growth Potential Analysis
3.4 Pricing Analysis (Driven by Primary Research)
3.4.1 Historical Price Trend Analysis (Driven by Primary Research)
3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus) (Driven by Primary Research)
3.5 Regulatory Landscape
3.5.1 North America
3.5.2 Europe
3.5.3 Asia Pacific
3.5.4 Latin America
3.5.5 Middle East & Africa
3.6 Porter's Analysis
3.7 PESTEL Analysis
3.8 Trade Data Analysis (Based on Paid Database)
3.8.1 Import/Export Volume & Value Trends (Based on Paid Database)
3.8.2 Key Trade Corridors & Tariff Impact (Based on Paid Database)
3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
3.9.1 AI-Driven Disruption of Existing Business Models
3.9.2 GenAI Use Cases & Adoption Roadmap by Segment
3.9.3 Risks, Limitations & Regulatory Considerations
3.10 Capacity & Production Landscape (Driven by Primary Research)
3.10.1 Production Capacity by Region & Key Producer (Driven by Primary Research)
3.10.2 Capacity Utilization Rates & Expansion Pipelines (Driven by Primary Research)
3.11 Forecast Assumptions & Scenario Analysis (Driven by Primary Research)
3.11.1 Base Case — Key Macro & Industry Variables Driving CAGR
3.11.2 Optimistic Scenario — Favourable Macro & Industry Tailwinds
3.11.3 Pessimistic Scenario — Macroeconomic Slowdown or Industry Headwinds
Chapter 4. Competitive Landscape, 2025
4.1 Introduction
4.2 Company Market Share Analysis
4.2.1 By Region
4.2.1.1 North America
4.2.1.2 Europe
4.2.1.3 Asia Pacific
4.2.1.4 Latin America
4.2.1.5 Middle East & Africa
4.2.2 Market Concentration Analysis
4.3 Competitive Analysis of Major Market Players
4.4 Competitive Positioning Matrix
4.5 Key Developments
4.5.1 Mergers & Acquisitions
4.5.2 Partnerships & Collaborations
4.5.3 New Product Launches
4.5.4 Expansion Plans & Funding
4.6 Company Tier Benchmarking
4.6.1 Tier Classification Criteria & Qualifying Thresholds
4.6.2 Tier Positioning Matrix by Revenue, Geography & Innovation
Chapter 5. Cosmetic Oil Market Estimates & Forecast, By Oil Type (USD Million, 2022–2035)
5.1 Key Trends & Insights, By Oil Type
5.2 Vegetable & Plant-Based Oils
5.2.1 Argan Oil
5.2.2 Coconut Oil
5.2.3 Jojoba Oil
5.2.4 Almond Oil
5.2.5 Rosehip Oil
5.2.6 Castor Oil
5.2.7 Olive Oil
5.2.8 Others (Grapeseed, Marula, Baobab, Sea Buckthorn, etc.)
5.3 Essential Oils
5.3.1 Lavender Oil
5.3.2 Tea Tree Oil
5.3.3 Rose Oil
5.3.4 Others (Eucalyptus, Peppermint, Chamomile, Frankincense, etc.)
5.4 Mineral Oils
5.5 Synthetic Oils
5.5.1 Silicone Oils (Dimethicone, Cyclomethicone)
5.5.2 Synthetic Esters
5.6 Others (Exotic/Specialty & Blended Functional Oil Complexes)
Chapter 6. Cosmetic Oil Market Estimates & Forecast, By Nature (USD Million, 2022–2035)
6.1 Key Trends & Insights, By Nature
6.2 Organic
6.2.1 Certified Organic (USDA, COSMOS, Ecocert)
6.2.2 Natural/Clean-Label (Non-Certified)
6.3 Conventional
Chapter 7. Cosmetic Oil Market Estimates & Forecast, By Application (USD Million, 2022–2035)
7.1 Key Trends & Insights, By Application
7.2 Skin Care
7.2.1 Facial Oils & Serums
7.2.2 Body Oils & Moisturizers
7.2.3 Cleansing Oils & Oil-Based Makeup Removers
7.2.4 Sun Care Oil Formulations
7.3 Hair Care
7.3.1 Scalp Treatment & Nourishment Oils
7.3.2 Hair Conditioning & Repair Oils
7.3.3 Hair Growth & Anti-Hair Loss Oils
7.4 Lip Care
7.4.1 Lip Oils & Glosses
7.4.2 Lip Serums & Oil-Based Balms
7.5 Nail & Cuticle Care
7.5.1 Cuticle Treatment Oils
7.5.2 Nail Strengthening & Repair Oils
7.6 Aromatherapy & Wellness
7.6.1 Massage Oils
7.6.2 Bath & Body Oils
7.6.3 Diffuser & Relaxation Blends
7.7 Others (Color Cosmetics with Oil Bases, Fragrance Carrier Oils, Professional Salon Blends)
Chapter 8. Cosmetic Oil Market Estimates & Forecast, By Distribution Channel (USD Million, 2022–2035)
8.1 Key Trends & Insights, By Distribution Channel
8.2 Online
8.2.1 Brand Direct-to-Consumer (DTC) Websites
8.2.2 Third-Party E-Commerce Platforms (Amazon, Nykaa, Sephora Online, etc.)
8.2.3 Social Commerce (Instagram, TikTok Shop, Pinterest)
8.3 Offline
8.3.1 Supermarkets & Hypermarkets
8.3.2 Specialty Beauty & Personal Care Stores
8.3.3 Pharmacies & Drug Stores
8.3.4 Convenience Stores
8.4 Direct Sales
8.4.1 Network Marketing & MLM Channels
8.4.2 Professional Salon & Spa Supply
8.5 Others
8.5.1 Subscription Beauty Boxes
8.5.2 Duty-Free & Travel Retail
8.5.3 Institutional & B2B Procurement
Chapter 9. Cosmetic Oil Market Estimates & Forecast, By Region (USD Million, 2022–2035)
9.1 Key Trends & Insights, By Region
9.2 North America
9.2.1 U.S.
9.2.2 Canada
9.3 Europe
9.3.1 Germany
9.3.2 UK
9.3.3 France
9.3.4 Italy
9.3.5 Spain
9.3.6 Rest of Europe
9.4 Asia Pacific
9.4.1 China
9.4.2 India
9.4.3 Japan
9.4.4 South Korea
9.4.5 Australia
9.4.6 Rest of Asia Pacific
9.5 Latin America
9.5.1 Brazil
9.5.2 Mexico
9.5.3 Rest of Latin America
9.6 Middle East & Africa
9.6.1 South Africa
9.6.2 Saudi Arabia
9.6.3 UAE
9.6.4 Rest of Middle East & Africa
Chapter 10. Company Profiles (Driven by Primary Research)
Don't see your key competitors?
The companies listed in this report are a curated selection - not the full competitive universe.
Our market revenue calculations use a bottom-up methodology that accounts for all players across all regions - including manufacturers, distributors, and specialists not individually profiled. The profiles section spotlights strategically significant players; it does not define the scope of our market sizing.
Your competitive landscape may also include
Free customization - up to 20% of report value
Need specific data? Request customization and get the insights tailored to your exact requirements.
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at [email protected]
Share Content
Add Citations
Kiran Pulidindi. 2026, September. Cosmetic Oil Market – By Source, By Formulation, By Function, By Application, By Distribution Channel, By End Use, Growth Forecast, 2026–2035 (Report ID: GMI3982). Global Market Insights Inc. Retrieved October 30, 2026, from https://www.gminsights.com/toc/details/cosmetic-oil-market

Cosmetic Oil Market
Get a free sample of this report
Cosmetic Oil Market Size
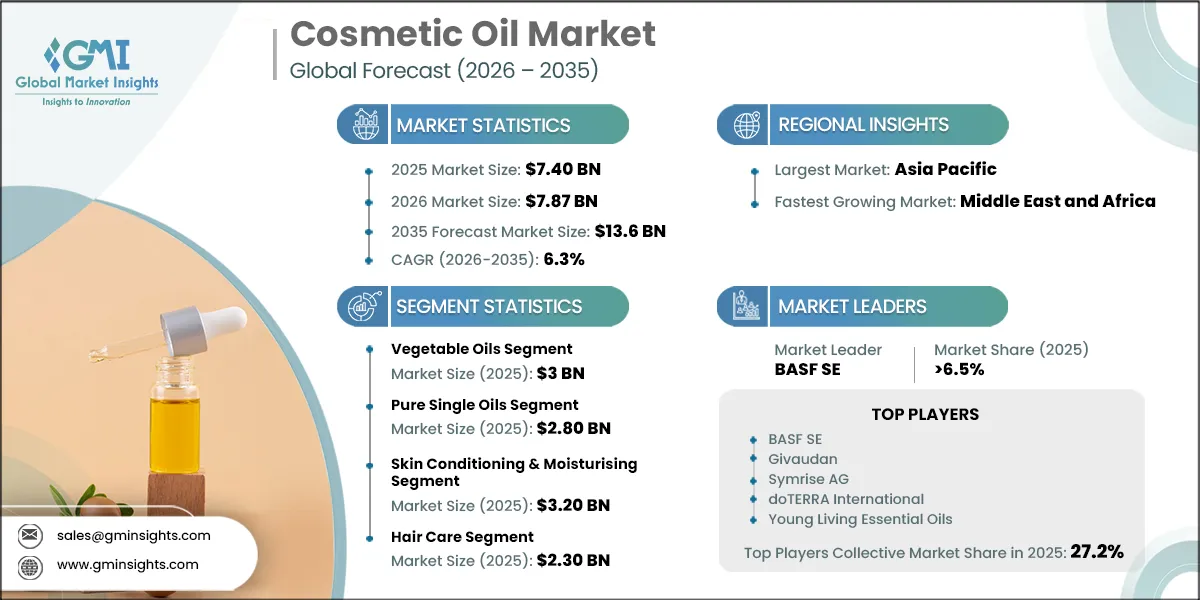
The Cosmetic Oil Market was valued at USD 7.40 billion in 2025, is expected to reach USD 7.87 billion in 2026, and is projected to expand at a ~6.3% CAGR (2026–2035), reaching USD 13.60 billion by 2035. The market includes natural, semi-synthetic, synthetic, and biotechnology-derived oils used as active ingredients, carrier components, and functional additives in personal care products.
The Cosmetic Oil Market is moving from a treatment-oriented niche toward a broader formulation platform across daily skin care, hair care, cleansing, fragrance, and professional beauty services. Botanical provenance supports premium positioning, while advances in delivery systems make oils more compatible with lightweight textures, aqueous formats, and performance-led claims.
GMI Analyst View
Based on our forecast modeling and discussions with industry participants, we expect the market to reach approximately USD 10.04 billion by 2030. The intervening period should be shaped by concurrent reformulation activity, digital distribution expansion, and rising beauty expenditure in emerging consumer markets.
Cosmetic Oil Market Trends, Growth Drivers & GMI Forecast Outlook
Demand is being reshaped by the convergence of ingredient transparency, regulatory reformulation, and channel migration. Botanical oils benefit when consumers seek traceable, multipurpose formulations, while biotechnology-derived materials gain relevance where sensory performance, supply consistency, and formulation stability are decisive.
Key Drivers
Natural-origin positioning is becoming a commercial requirement rather than a marginal claim in premium personal care. Certifications, retailer ingredient policies, and greater consumer literacy make traceability and supply-chain documentation more consequential for brands seeking price resilience and differentiated shelf positioning.
Digital commerce also changes the economics of niche oil formats. Direct-to-consumer brands can use education-led content to explain provenance, sensory characteristics, and application routines, reducing the dependence on conventional shelf space. This favors products such as single-origin oils, targeted scalp treatments, and functional blends whose value proposition benefits from detailed consumer education.
The microplastics restriction adds a practical reformulation catalyst. Suppliers able to offer stable, compliant oil-based alternatives with validated sensory performance are positioned to capture formulation work that might otherwise have remained within conventional polymer-based systems.
Key Restraints
Palm-derived feedstocks remain important to cosmetic emulsifier, surfactant, and carrier-oil supply chains, so fuel-policy shifts can transmit pricing pressure well beyond the directly affected oil. The most exposed formulators are those with limited feedstock flexibility, limited hedging capacity, or mass-market price points that do not allow rapid pass-through.
Specialty botanical oils present a different operational challenge. Their oxidation sensitivity can require inert handling, antioxidant systems, specialized packaging, and tighter logistics control. These requirements do not preclude growth, but they favor suppliers with formulation expertise and customers capable of monetizing a premium sensory or provenance proposition.
Evidence anchors use cited external data; demand implications and forecast conditions represent GMI analysis.
GMI Analyst View
We view the central forecast tension as a divide between premium demand formation and mass-market cost discipline. Ingredient provenance, sustainability credentials, and formulation transparency strengthen premium product economics, while volatile feedstock availability compels value-oriented brands to prioritize sourcing flexibility and more cost-efficient product architectures.
Cosmetic Oil Market Segment Analysis
By Source
Vegetable Oils generated USD 3.00 billion in 2025 and are expected to account for 39.0% of market revenue by 2035. Vegetable oils remain foundational because palm, sunflower, soy, safflower, and rice bran can support broad-volume emollient, conditioning, and carrier applications. Their relative share moderation reflects diversification into botanical and biotechnology-derived inputs rather than a loss of strategic relevance.
Plant Oils held a 23.0% share in 2025 and are projected to generate USD 3.30 billion by 2035. Argan, jojoba, coconut, olive, avocado, and rosehip oils benefit from premium storytelling, recognizable ingredient identities, and compatibility with active-led skin and hair care. The segment's value creation is driven by formulation differentiation and price realization rather than commodity-scale supply alone.
Nut Oils generated USD 1.00 billion in 2025 and are anticipated to expand at an approximately ~6.6% CAGR (2026–2035). Macadamia, walnut, hazelnut, and specialty oils provide brands with a route to single-origin and wellness-oriented positioning. Their commercial potential depends on consistent quality specifications, reliable traceability, and careful management of supply concentration.
Synthetic & Biotech-Derived oils are projected to represent 13.9% of revenue by 2035 and are expected to grow at an approximately ~7.7% CAGR (2026–2035). Fermentation-sourced squalane, silicone-based emollients, and bioengineered alternatives address limitations associated with botanical variability, oxidation, and constrained agricultural supply. Their role expands where formulators need reproducibility, vegan positioning, and high-performance sensory characteristics.
Mineral Oils accounted for 10.8% of revenue in 2025 and are projected to represent 8.8% by 2035. Mineral oils retain utility in price-sensitive and high-volume applications because of oxidative stability, cost efficiency, and established processing familiarity. However, retailer sustainability requirements and clean-beauty narratives increasingly narrow their role in premium-facing product portfolios.
By Formulation
The Cosmetic Oil Market's formulation mix is broadening as brands balance ingredient simplicity with delivery performance and differentiated sensorial profiles.
Pure Single Oils generated USD 2.80 billion in 2025 and are projected to account for 37.5% of revenue by 2035. Undiluted jojoba, rosehip, marula, and argan products align directly with consumer demand for ingredient clarity. Their durability depends on credible sourcing, consistent sensory quality, and packaging that protects delicate oils without undermining the product's natural positioning.
Blended/Carrier Oils held a 32.4% share in 2025 and are expected to generate USD 4.40 billion by 2035. Blends allow formulators to combine texture, stability, fragrance compatibility, and targeted performance in a way that single oils cannot always achieve. They are especially relevant to professional users and premium retail formats seeking customized treatment narratives.
Infused Oils generated USD 1.40 billion in 2025 and are anticipated to expand at an approximately ~6.0% CAGR (2026–2035). Infused formats bridge traditional botanical practices with contemporary active-ingredient positioning. Their appeal is strongest where brands can translate maceration, botanical extraction, and ritualized use into a credible modern efficacy proposition.
Encapsulated/Nano-Emulsified oils held a 10.8% share in 2025 and are anticipated to grow at an approximately ~7.2% CAGR (2026–2035). Encapsulation and nano-emulsification help address oxidative instability, sensory heaviness, and limited aqueous compatibility. These technologies make oil-based actives more suitable for serums, leave-on hair products, and performance-led skin treatments without abandoning natural-origin cues.
By Function
Skin Conditioning & Moisturizing generated USD 3.20 billion in 2025 and is projected to represent 43.4% of revenue by 2035. The function benefits from the integration of barrier-support and hydration products into daily routines. Cosmetic oils are increasingly used not only as occasional treatments but also as foundational components of moisturizers, facial oils, and recovery-focused formulations.
Hair Conditioning held a 21.6% share in 2025 and is projected to generate USD 2.80 billion by 2035. Coconut, argan, and castor oil systems address a practical combination of frizz control, conditioning, scalp care, and heat-related concerns. Professional recommendations and culturally embedded oiling practices support recurring use across diverse consumer groups.
Anti-Aging & Antioxidant applications generated USD 1.20 billion in 2025 and are anticipated to expand at an approximately ~6.7% CAGR (2026–2035). This function benefits when oils are positioned as active contributors to a broader treatment regimen rather than simply as emollients. Differentiation rests on formulation evidence, texture, and compatibility with other skin care actives.
Cleansing & Makeup Removal held a 10.8% share in 2025 and is projected to generate USD 1.40 billion by 2035. Oil cleansing has become more widely accepted through routine education, particularly in markets influenced by Asian beauty practices. The format provides an accessible entry point for consumers who may not otherwise use facial oils as leave-on treatments.
UV Protection held a 5.4% share in 2025 and is anticipated to grow at an approximately ~7.2% CAGR (2026–2035). Oil-based systems can contribute to sensory quality and formulation architecture in natural and hybrid sun-care products. Their opportunity depends on responsible claims discipline and on the ability to satisfy evolving product-performance and regulatory requirements.
By Application
Skin Care generated USD 2.70 billion in 2025 and is projected to represent 39.0% of revenue by 2035. Skin care is the principal application for premium facial oils, oil cleansers, serum oils, and oil-infused moisturizers. The application's depth allows suppliers to serve both daily-use hydration routines and higher-value treatment formats.
Hair Care generated USD 2.30 billion in 2025 and is projected to generate USD 4.10 billion by 2035. The application draws on established consumer familiarity with oil-based conditioning across South Asia, sub-Saharan Africa, the Middle East, and other markets. Professional styling, scalp treatment, and heat-protection needs create multiple routes to recurring demand.
Fragrance & Aromatherapy held a 12.2% share in 2025 and is anticipated to expand at an approximately ~6.6% CAGR (2026–2035). Essential and aromatic oils support premium fragrance narratives, wellness positioning, and natural-origin differentiation. Growth is strongest where product makers can maintain supply integrity and manage the variability inherent in natural aromatic raw materials.
Bath & Shower Products generated USD 700 million in 2025 and are projected to account for 8.8% of revenue by 2035. Bath oils, shower oils, and body-oil products retain a role in self-care and premium body-care routines. Their more measured expansion reflects competition from adjacent formats such as body lotions, cleansing creams, and multifunctional wash products.
Make-Up held a 6.8% share in 2025 and is anticipated to grow at an approximately ~4.8% CAGR (2026–2035). Oil-based make-up ingredients remain valuable for slip, pigment dispersion, and comfort, but lighter textures and humidity-resistant formats limit their relative growth. Innovation is likely to center on hybrid systems that preserve emollience while reducing perceived heaviness.
By Distribution Channel
Supermarkets/Hypermarkets generated USD 1.90 billion in 2025 and are projected to account for 22.1% of revenue by 2035. These outlets remain important for mass-market accessibility and repeat purchase, particularly for household-recognized hair and body oil brands. Their declining relative weight reflects the faster expansion of channels better suited to education-led premium products.
Online/E-Commerce held a 20.3% share in 2025 and is anticipated to grow at an approximately ~9.1% CAGR (2026–2035). Digital channels give brands an efficient route to demonstrate ingredient provenance, application methods, and before-and-after routines. They also accelerate new-product testing and enable specialty brands to reach consumers beyond established beauty retail centers.
Specialty Stores generated USD 1.40 billion in 2025 and are projected to generate USD 2.60 billion by 2035. Natural retailers, beauty boutiques, and dedicated skin care chains remain important for high-consideration products. Their staff expertise and curated assortments can reinforce the trust required for higher-priced botanical and treatment-oriented oils.
Professional Salon held a 14.9% share in 2025 and is projected to generate USD 1.90 billion by 2035. The salon channel supports higher-value oil systems through service integration and professional endorsement. Stylist or aesthetician recommendation helps translate technical treatment benefits into repeat consumer purchasing.
Pharmacy Stores generated USD 900 million in 2025 and are anticipated to expand at an approximately ~5.9% CAGR (2026–2035). Pharmacy distribution supports oil products associated with sensitive skin, barrier care, and dermatology-adjacent routines. The setting can lend credibility to formulations where safety, gentleness, and ingredient transparency are central to purchase decisions.
By End Use
Individual Consumers generated USD 4.50 billion in 2025 and are projected to account for 61.8% of revenue by 2035. At-home beauty routines, specialty retail access, and social-commerce education make individual consumers the market's primary demand base. Product formats that simplify usage and communicate visible benefits are best positioned to maintain engagement.
Professional Users held a 25.7% share in 2025 and are projected to generate USD 3.60 billion by 2035. Salon operators, aestheticians, and independent practitioners use cosmetic oils within treatment protocols where product performance and repeatability matter. Their demand supports premium formats with stronger technical-service and training requirements.
Industrial/B2B buyers generated USD 1.00 billion in 2025 and are anticipated to grow at an approximately ~4.8% CAGR (2026–2035). Bulk buyers remain essential to the supply chain, but value is increasingly concentrated in certified, branded, functional, and specialty formulations. This shifts competitive emphasis from commodity supply toward product development support and differentiated ingredient platforms.
GMI Analyst View
We see formulation technology as the segment architecture's key fault line. Single-origin oils retain strong emotional and commercial appeal, but scalable growth increasingly favors systems that solve stability, texture, and delivery constraints while preserving the natural-origin signals that underpin consumer willingness to pay.
Cosmetic Oil Market Regional Analysis
Asia Pacific Cosmetic Oil Market Analysis
The Cosmetic Oil Market in Asia Pacific generated USD 2.80 billion in 2025 and is projected to account for 39.0% of global revenue by 2035. The region combines scale in beauty consumption, dense digital ecosystems, established oil-use traditions, and substantial botanical supply capabilities. Its advantage is not solely volume; it also stems from the close interaction among ingredient sourcing, product development, manufacturing, and fast-moving consumer trends.
China
China generated USD 1.26 billion in 2025 and is projected to represent 44.9% of Asia Pacific revenue by 2035. Premiumization, e-commerce penetration, and sophisticated consumer engagement with ingredient claims support demand. The market's manufacturing base also gives local and international brands a pathway to integrate regional supply chains with rapid product iteration.
India
India held a 13.9% share of Asia Pacific revenue in 2025 and is projected to generate USD 740 million by 2035. Longstanding hair and skin oiling practices give cosmetic oil brands a culturally familiar use case. Value creation increasingly depends on translating traditional oils into modern formats with improved sensorial performance, targeted benefits, and credible premium cues.
Japan
Japan generated USD 500 million in 2025 and is projected to generate USD 950 million by 2035. Japanese demand favors refined, lightweight formulations and carefully substantiated product benefits. This creates an opening for highly stable botanical oils and biotechnology-derived materials that can meet elevated expectations around texture and consistency.
South Korea
South Korea held a 10.0% share of Asia Pacific revenue in 2025 and is projected to generate USD 530 million by 2035. South Korea remains an influential source of product-format innovation, particularly in cleansing oils and layered skin care routines. Its impact extends beyond domestic consumption because local formats often diffuse into global beauty product development.
North America Cosmetic Oil Market Analysis
North America held a 21.6% share of global revenue in 2025 and is projected to generate USD 2.80 billion by 2035. The market is shaped by mature premium beauty retail, high consumer familiarity with clean-label claims, and a strong digital purchasing environment. Suppliers compete on certification, sensory performance, ingredient traceability, and the ability to support differentiated branded formulations.
United States
The United States generated USD 1.30 billion in 2025 and is projected to generate USD 2.30 billion by 2035. Demand is supported by specialty retail, prestige beauty, natural product channels, and a highly developed online beauty ecosystem. Retailer ingredient requirements can function as practical market-access filters, increasing the importance of documentation and formulation transparency.
Europe Cosmetic Oil Market Analysis
The Cosmetic Oil Market in Europe generated USD 1.40 billion in 2025 and is projected to account for 19.1% of global revenue by 2035. Europe pairs an ingredient-conscious consumer base with demanding regulatory and sustainability expectations. These conditions reward suppliers that can combine natural-origin claims with traceable sourcing, stable quality, and clear technical support for reformulation.
Germany
Germany generated USD 320 million in 2025 and is anticipated to grow at an approximately ~6.5% CAGR (2026–2035). Germany's importance extends beyond its direct demand base because of its role in natural ingredients sourcing, distribution, and certification-led product development. Consumer interest in transparent, certified botanical products continues to influence broader European private-label and branded portfolios.
United Kingdom
The United Kingdom generated USD 290 million in 2025 and is projected to generate USD 540 million by 2035. The market's trajectory will be influenced by how regulatory alignment develops alongside consumer demand for clean, premium, and transparent formulations. Suppliers serving both UK and EU markets benefit from formulation strategies that can accommodate potentially divergent compliance requirements.
France
France remains strategically important to cosmetic oils because prestige fragrance and luxury beauty influence ingredient narratives and product positioning far beyond the domestic market.
High-end brands use botanical oils and refined oil-based systems to support sensorial differentiation, provenance stories, and elevated price points. This gives the French market relevance disproportionate to a narrow revenue-only view.
Latin America Cosmetic Oil Market Analysis
Latin America held a 12.8% share of global revenue in 2025 and is projected to generate USD 1.70 billion by 2035. The region combines strong consumer affinity for hair oils with access to distinctive botanical resources such as buriti, andiroba, açaí, and maracuja. Commercial opportunity depends on turning biodiversity into repeatable, traceable, and scalable ingredient platforms rather than relying only on origin narratives.
Brazil
Brazil generated USD 570 million in 2025 and is projected to generate USD 1.02 billion by 2035. Brazil benefits from domestic botanical diversity, a large salon economy, and substantial consumer engagement with hair and body care. Its market is particularly attractive to suppliers that can connect local natural-ingredient stories with professional-quality performance and dependable industrial supply.
Middle East & Africa Cosmetic Oil Market Analysis
The Cosmetic Oil Market in Middle East & Africa generated USD 590 million in 2025 and is anticipated to expand at an approximately ~7.4% CAGR (2026–2035). The region's growth is supported by fragrance-forward beauty traditions, expanding retail and professional-service infrastructure, and a strong cultural familiarity with aromatic and treatment oils. Demand is likely to remain differentiated by country, income profile, and the relative development of prestige and mass-market channels.
Saudi Arabia
Saudi Arabia generated USD 150 million in 2025 and is projected to generate USD 300 million by 2035. Beauty infrastructure expansion and demand for aromatic, conditioning, and premium personal care products support the market. Retail modernization and professional-service growth create further opportunities for brands able to localize product and fragrance propositions.
UAE
The UAE generated USD 120 million in 2025 and is anticipated to grow at an approximately ~7.2% CAGR (2026–2035). The UAE acts as a regional premium beauty hub, supported by high consumer spending, international retail exposure, and demand for both prestige global brands and culturally relevant fragrance oil products. Its role as a commercial gateway also strengthens its importance to regional distribution strategies.
South Africa
South Africa generated USD 90 million in 2025. Demand is supported by professional and mass-market hair care, alongside rising interest in indigenous botanical oils such as marula and baobab. The opportunity for suppliers lies in balancing locally resonant ingredients with dependable quality and affordable product formats.
GMI Analyst View
We expect regional performance to be determined by the interaction of beauty culture, supply-chain capability, and channel maturity rather than by income growth alone. Asia Pacific has the strongest integrated ecosystem, while Middle East & Africa offers a compelling premium and professional-service opportunity as beauty infrastructure broadens.
Cosmetic Oil Market Share & Competitive Landscape
The Cosmetic Oil Market share structure is moderately fragmented, with the five largest companies collectively accounting for approximately 27.2% of global revenue in 2025. Competition spans large-scale vegetable-oil processing, botanical specialization, branded consumer products, and research-intensive biotechnology-derived ingredients, limiting the ability of any single business model to dominate the category.
BASF SE held a 6.5% market share in 2025.
BASF competes through its Care Chemicals capabilities, broad formulation support, and portfolio spanning emollients, surfactants, emulsifiers, and bio-derived personal care materials. Its scale in renewable-feedstock sourcing and technical services strengthens its relevance to multinational formulators seeking global supply assurance.
Givaudan held an approximately 6.0% market share in 2025.
Givaudan's position is supported by its Fragrance & Beauty platform, specialty natural extracts, active cosmetic ingredients, and relationships with prestige beauty customers. Its strength lies in translating fragrance, sensoriality, and botanical ingredient innovation into higher-value personal care propositions.
Croda International PLC remains an important formulator-focused participant in plant oil-based emollients, esters, and delivery systems. Its focus on sustainable ingredients and technical performance positions the company well where customers require both natural-origin credentials and advanced formulation functionality.
doTERRA International held an approximately 4.8% market share in 2025.
doTERRA's direct-selling model, essential-oil specialization, and sourcing relationships provide a differentiated route to end consumers and wellness practitioners. Its commercial model emphasizes provenance and customer engagement, which can support loyalty in premium aromatic and carrier-oil formats.
L'Oréal S.A., Unilever PLC, Shiseido Co., Ltd., The Estée Lauder Companies Inc., and Clarins Group influence demand principally through branded finished products and formulation choices. Specialist suppliers including Olvea Vegetable Oils, AAK AB, Henry Lamotte Oils GmbH, Sophim SAS, Marico Ltd., Jojoba Desert (A.C.S.) Ltd., Provital Group, Farsali LLC, and NOW Health Group, Inc. compete through raw-material expertise, regional relevance, functional positioning, and niche product innovation.
Recent Industry Developments
Givaudan SA to acquire a majority stake in Eurofragance SLU. Givaudan announced an agreement to acquire a majority interest in Eurofragance, strengthening its fragrance and beauty presence across Europe, the Middle East, Asia, Africa, and Latin America. The transaction reinforces the strategic importance of regional fragrance and personal care capabilities in markets relevant to cosmetic oil demand.
Marico Ltd. launches Parachute Advansed Olive Enriched Coconut Hair Oil. Marico introduced an olive-and-coconut oil superblend through an e-commerce-led launch, illustrating the continued convergence of hair oil premiumization, natural ingredient positioning, and digital-first distribution.
Need a specific section of this report?
Purchase regional analysis, country-level analysis, company profiles, or any other segment-level insights separately
based on your research needs.